Half Year Earning Update
Date: 22/2/2024
*** GENERAL AVICE ONLY***
Highlight
- Efficient operations and project expansion for increased spodumene production.
- Commenced commissioning at the POSCO Pilbara Minerals’ JV chemical plant in South Korea.
- Maintained strong EBITDA margin amidst moderated lithium pricing environment.
- Reduced capital expenditure to preserve capital and withheld interim dividend.
- Increased total material mined and completed key expansion projects on schedule and budget.
- Advanced mid-stream demonstration plant project with Calix.
Financial Performance
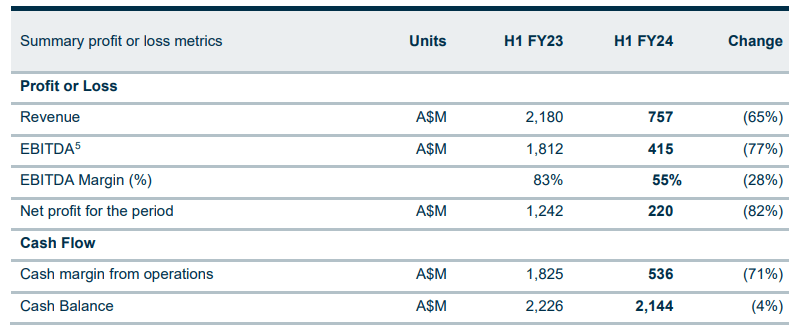
- Revenue: Decreased by 65% to $757.2 million, primarily due to a 67% decrease in the average estimated realized price, despite a 7% increase in sales volume.
- EBITDA: Strong EBITDA margin of 55% was delivered, indicating efficient operational performance despite the decrease in lithium prices.
- Net Profit After Tax (NPAT): Decreased significantly to $220.2 million from the previous period’s $1,241.9 million.
- Earnings Per Share (EPS): Decreased to 7.3 cents from 41.6 cents in the previous corresponding period.
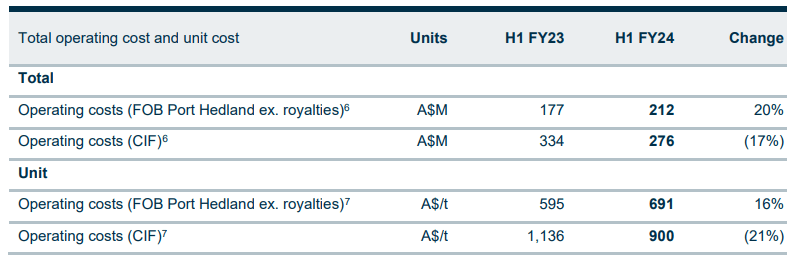
- Operating Costs: Increased by 16% to $691 per tonne due to investments in operating costs to support increased production capacity.
- Cash Balance: Ended the period at $2,144.2 million, including significant tax payments.
- Dividends: No interim dividend was declared for the half-year ended 31 December 2023.
Business Operations
Total Ore Mined and Processed: There was a significant increase in total material mined and ore processed across the reporting period, with ore processed increasing from 1,704,892 dry metric tons (dmt) to 1,834,176 dmt. The average grade of product sold was approximately 5.3% Li2O.
Production and Shipments:
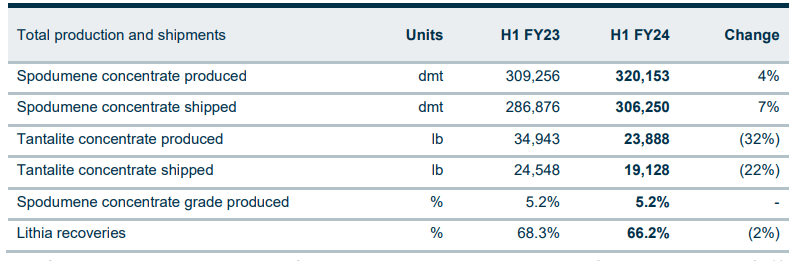
- Spodumene concentrate production increased by 4% to 320,153 dmt.
- Spodumene concentrate shipped increased by 7% to 306,250 dmt.
- Tantalite concentrate production and shipments saw a decrease, with production down by 32% and shipments by 22%.
- Lithia recoveries decreased by 2%.
Operating Costs:
- The Free On Board (FOB) operating costs increased by 16% to $691 per tonne, reflecting investments in operating costs to support increased production volumes enabled by the P680 project.
- Total operating costs (excl. depreciation and amortisation) decreased by 17% due to planned pre-investment expenses and inflationary pressures offset by lower royalties.
Developments and Acquisitions:
- P680 Expansion Project: Includes the construction of a new Primary Rejection circuit and a company-owned crushing facility. The Primary Rejection Facility has been commissioned, marking a milestone in the ramp-up of the facility.
- P1000 Expansion Project: Focuses on increasing the annual nameplate production run rate from the Pilgangoora Operation to approximately 1Mtpa. Detailed design and bulk earthworks have been completed, with significant progress made during the half-year.
- Mid-Stream Project: In partnership with Calix, Pilbara Minerals decided to construct the Mid-Stream Demonstration Plant Project to produce a mid-stream lithium enriched product using patented electric kiln technology.
- Downstream Joint Venture with POSCO: Construction of the Lithium Hydroxide Monohydrate (LHM) Chemical Facility in Gwangyang, South Korea, has seen significant progress, including the completion of Train 1 construction and commencement of commissioning.
FY24 Outlook
Expanding Production: Focused on expanding production through the P680 and P1000 projects, which are expected to yield increased production capacity and reduced unit costs. These expansions are fully funded from existing cash reserves, aiming to capitalize on the expected increased demand for lithium.
Managing Costs: Rationalizing non-essential spend that does not impact expansion or further improve unit operating costs. The company has increased its focus on unit-cost efficiency and conducted a review of capital spend to ensure optimal operation and strong balance sheet.
Maximizing Value from Lithia Units: Amended several offtake agreements to expand medium-term supply to leading customers and reduce exposure to spot markets. Continues to advance partnering process for additional potential downstream partnering opportunities to maximize shareholder returns per lithia unit.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.