GENERAL ADVICE ONLY
Overview
- Megaport Limited, a leading provider in Network-as-a-Service (NaaS) connectivity, reported robust financial performance for FY25, showcasing significant growth in Annual Recurring Revenue (ARR) and total revenue.
- The company successfully deployed its extensive 400G backbone across 597 data centers, reinforcing its position as the largest 100G NaaS connectivity platform globally.
- Key impact news includes increased revenue across all regions and stabilization of Net Revenue Retention, indicating the positive outcomes of ongoing product innovation and go-to-market strategies.
Revenue & Growth Trends
- Annual Recurring Revenue (December 2024): $226.6M, up by 18% from $191.7M in December 2023.
- Total Revenue (H1 FY25): $106.8M, reflecting a 12% increase compared to $95.1M in H1 FY24.
- Full Year Revenue Guidance (FY25): Projected between $216M and $222M, marking an 11% to 14% growth from FY24’s $195.3M.
- Revenue Growth: Achieved across all regions in H1 FY25, driven by enhanced connectivity infrastructure and market expansion.
Margin & Profitability Metrics
- Gross Profit (H1 FY25): $74.7M, a 12% increase from $66.6M in H1 FY24.
- EBITDA (FY25 Guidance): Projected between $57M and $65M.
- Net Cash Flow (H1 FY25): $15.7M, up by $3.2M from $12.5M in H1 FY24.
Notable Year-over-Year (YoY) Changes
- ARR grew by 18% YoY, indicating strong recurring revenue streams.
- Total revenue increased by 12% YoY in H1 FY25, surpassing previous performance.
- Gross profit and net cash flow also saw consistent YoY growth, reflecting improved operational efficiency.
Guidance and Expectations
- Revenue Guidance for FY25: Updated to a range of $216M to $222M, assuming an AUD/USD exchange rate of 0.668.
- EBITDA Guidance: Remains unchanged, with expectations between $57M and $65M.
- Capital Expenditure (CapEx): Maintains a steady forecast of $27M to $30M for FY25.
- Currency Impact: A $0.01 move in AUD/USD by December 2024 is expected to annualize revenue impact by $2.0M to $2.2M and EBITDA impact by $0.6M to $0.8M.
- Net Revenue Retention: Improved to 107% since June 2024 from 106%, suggesting stabilization post product and market initiatives.
Strategic Considerations
- Capital Allocation: Capital expenditure remains unchanged, allowing sustained investment in core infrastructure and strategic roles.
- Operational Initiatives: Incremental investments in key go-to-market roles have been enabled by the improved ARR growth, particularly in The Americas.
- Product & Market Strategy: One and a half years of product innovation and go-to-market transformation initiatives are yielding positive results, contributing to stabilized Net Revenue Retention.
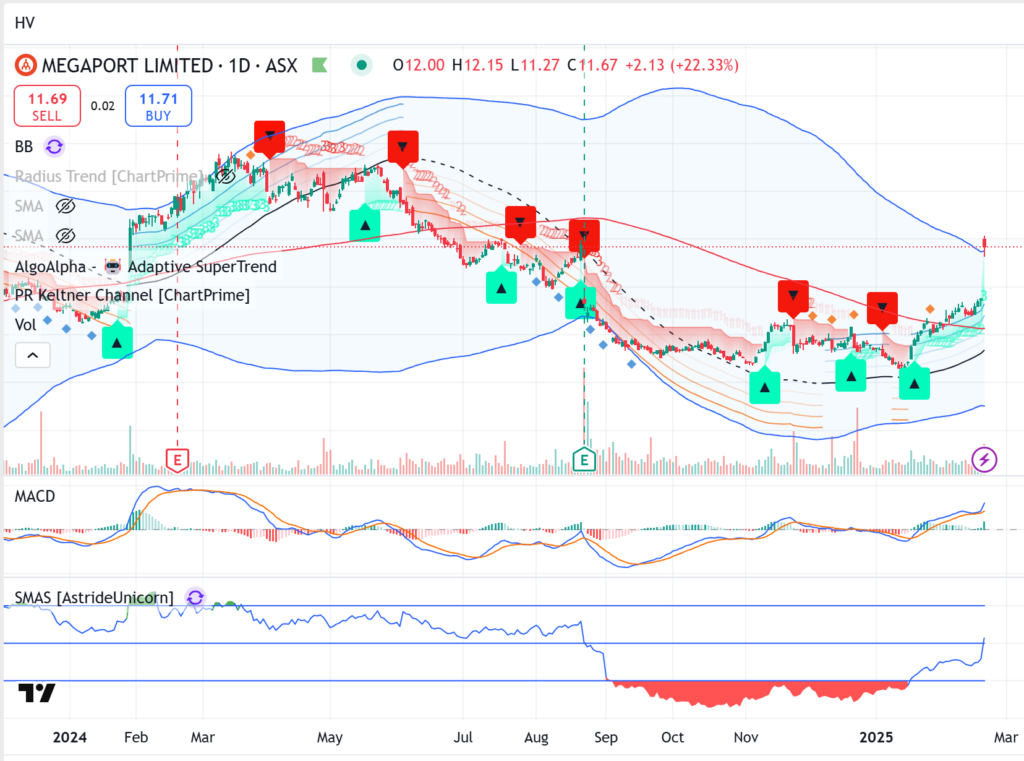
Trade Strategy:
Sell Megaport (MP1)
Entry: $11.30
Exit: $11.8
Profit: 4.4%
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.