MAAS Group Holdings (MGH) - 1H25
***GENERAL ADVICE ONLY ***
Financial Results:
- Revenue & EBITDA:
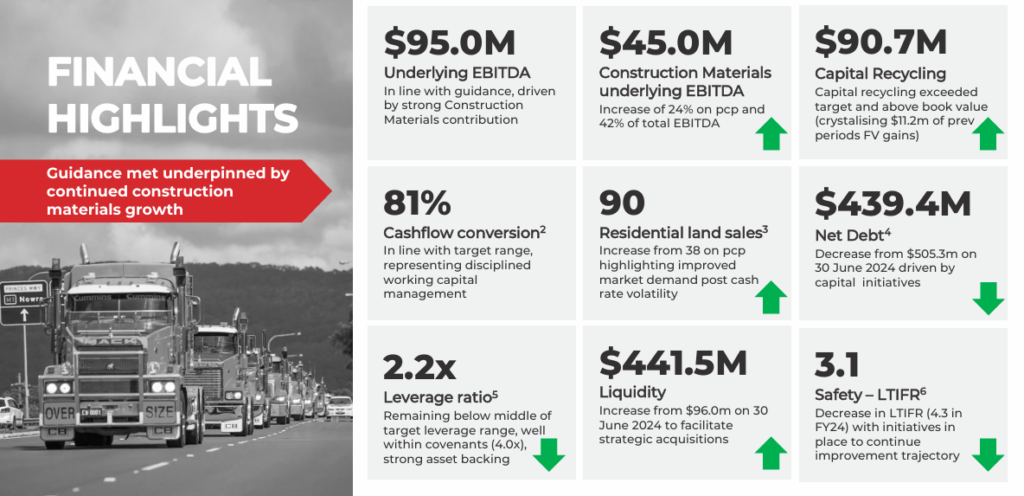
- Underlying revenue came in at approximately $458.6M (down 1% from 1H24), with underlying EBITDA reported at $95.0M—nearly in line with guidance expectations (around 40% of the annual target for 1H25).
- Profitability & Margins:
- EBIT fell by 9% (from $71.2M to $65.0M) and net profit after tax declined by 16% (from $38.5M to $32.2M).
- Earnings per share dropped by roughly 18% (from 11.8 cents to 9.7 cents).
- Cash Conversion & Liquidity:
- Operating cash flow conversion was 81%, down from 110% in the prior period.
- Liquidity improved dramatically, with cash rising from $96.0M to $441.5M and net debt reduced from about $505.3M to $439.4M, keeping the leverage ratio at a healthy 2.2x.
Guidance & Strategic Initiatives:
- Forward Guidance:
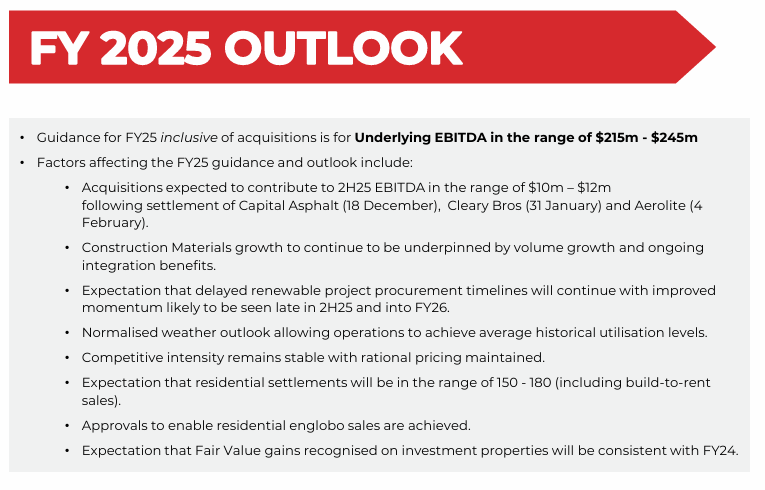
- Management expects FY25 underlying EBITDA to be in the range of $215M to $245M, inclusive of acquisitions.
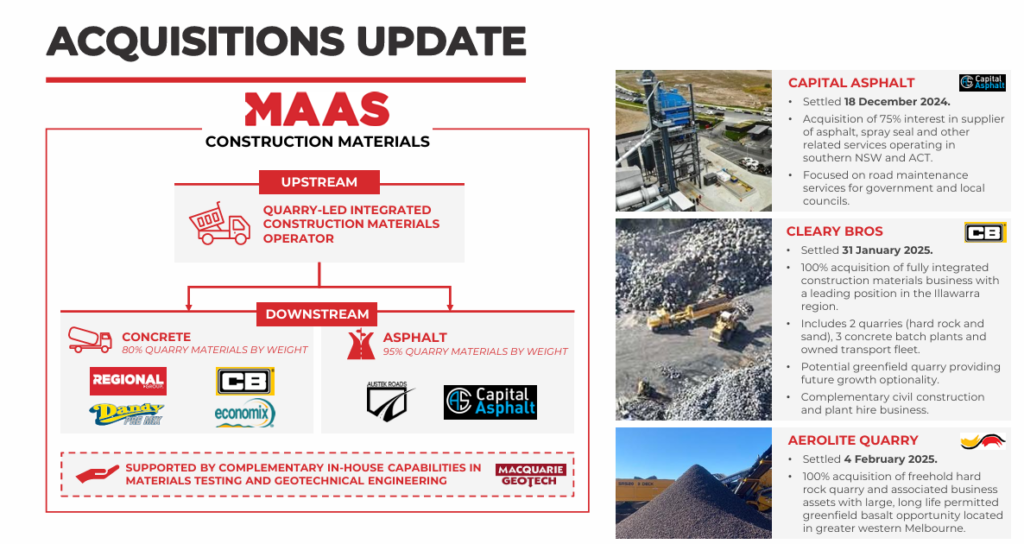
- The recent strategic acquisitions (Capital Asphalt, Cleary Bros, and Aerolite Quarries) are anticipated to contribute an additional $10M–$12M of EBITDA in 2H25.
- Capital Recycling:
- The company exceeded its target with capital recycling proceeds of $90.7M, which has strengthened its balance sheet and positioned it well for future acquisitions.
- Operational Focus:
- Growth in the Construction Materials segment remains a key highlight, while the Civil Construction and Hire (CC&H) division experienced significant project delays and isolated project losses—factors that are expected to improve in later periods.
- Forward Guidance:
Analyst Forecasts & Ratings:
- Morgans:
- Outlook: Forecast FY25 earnings around $234.5M, with acquisitions contributing roughly $9M in EBITDA.
- Rating & Target Price: Maintained an “Add” rating with a target price of $5.30.
- Macquarie:
- Guidance & Observations: Expects FY25 earnings between $215M and $245M. They noted that project delays in the Civil Construction and hire segments have resulted in a skewed EBITDA split (approximately 39% in 1H25 and 61% in 2H25).
- Capital Recycling & Valuation: Highlighted the strength of the capital recycling program, forecasting proceeds of over $100M and raised their target price to $5.06 (up from $4.95) while retaining an “Outperform” rating.
- Investor Concerns:
- Market sentiment was dampened by the significant decline in the Civil Construction and Hire segment, which saw a 47% drop in EBITDA due to project delays and losses.
- The softness in overall profitability (notably the decline in EBIT, net profit, and EPS) and the lower-than-expected cash conversion further contributed to the negative market response.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns