Pilbara Minerals Ltd (PLS) - 1H25
***GENERAL ADVICE ONLY ***
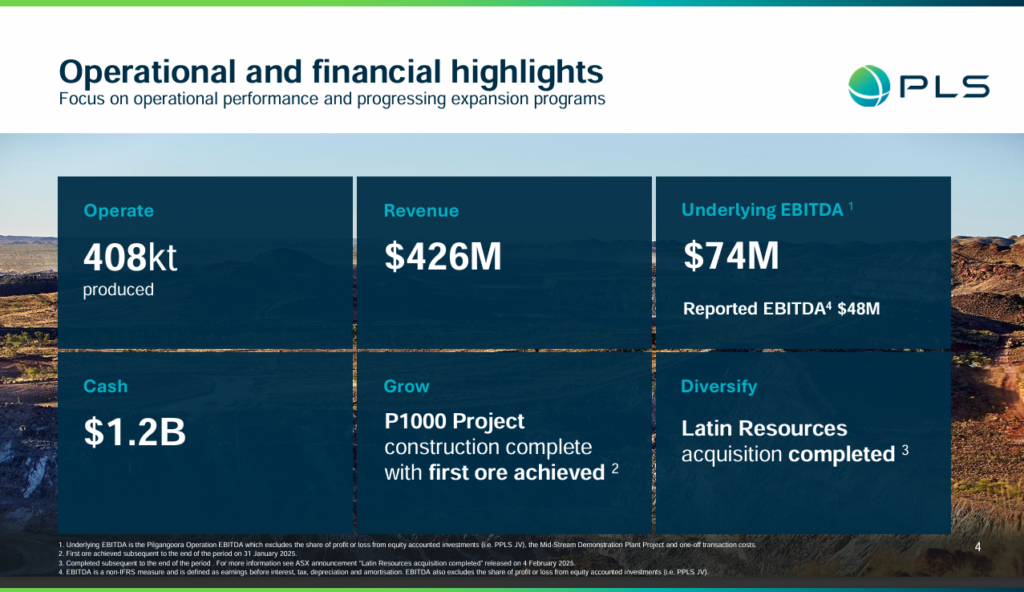
Pilbara Minerals reported a challenging half‐year where – despite record production and higher sales volumes – lower average realized prices put significant downward pressure on revenues and margins. Key milestones included the completion of the P680 Crushing and Sorting Facility, progress on the P1000 expansion (with first ore achieved post–period on 31 January 2025), and the completion of its first international acquisition – Latin Resources, which adds the Colina Project in Brazil to its portfolio.
- Production & Sales:
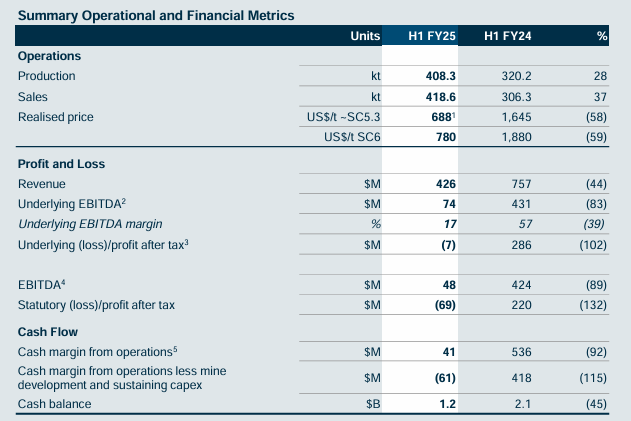
- Production increased by 28% from 320.2 kt to 408.3 kt.
- Sales volume rose by 37% from 306.3 kt to 418.6 kt, driven by higher production and improved ore recovery.
- Realized Prices:
- The average estimated realized price on a ~SC5.3 basis fell 58% to US$688/t (with a similar 59% drop on an SC6 basis).
- Process Enhancements:
- The commissioning of the P680 Project allowed for improved throughput at the Pilgangoora Operation, while the implementation of the P850 operating model – alongside placing the higher‐cost Ngungaju plant into care and maintenance – delivered lower unit operating costs (FOB costs fell 11% to A$/t 614 and CIF costs 20% to A$/t 724).
- Additional Production Details:
- Spodumene concentrate production increased by 28% (408,334 dmt vs 320,153 dmt in H1 FY24).
- There were notable improvements in recovery rates (e.g. lithia recovery improved from 66.2% to 73.8%).
- Revenue & Profitability:
- Revenue declined 44% year‐on‐year to $426 million, largely due to the 58% drop in the average realized price despite higher volumes.
- Underlying EBITDA for the Pilgangoora Operation fell 83% to $74 million (with an underlying EBITDA margin dropping from 57% to 17%).
- Statutory figures show a net loss after tax of $69 million (a swing from a $220 million profit in H1 FY24), while the underlying loss (excluding non‑cash and one‑off adjustments) was a modest $7 million.
- Cost Management:
- Operating costs (excluding depreciation) increased by around 10–21% in total, but effective operating leverage led to lower unit costs.
- General and administration expenses were trimmed slightly (a 7% decrease), reflecting the company’s focus on operational efficiencies.
- Non‑IFRS Metrics:
- Adjustments include non-cash items (such as the reduction in the carrying value of the call option related to the PPLS JV) and specific costs for growth projects (e.g. Mid‑Stream Demonstration Plant costs of approximately $24 million).
Outlook
- Operational Optimization:
- Implementation of the P850 operating model and repositioning of the Ngungaju plant (into care and maintenance with a restart capability within four months) have been critical in containing costs.
- Supply Chain Integration:
- Joint ventures with international partners like POSCO and Ganfeng are strengthening Pilbara’s integration into the battery materials supply chain.
- Long-Term Positioning:
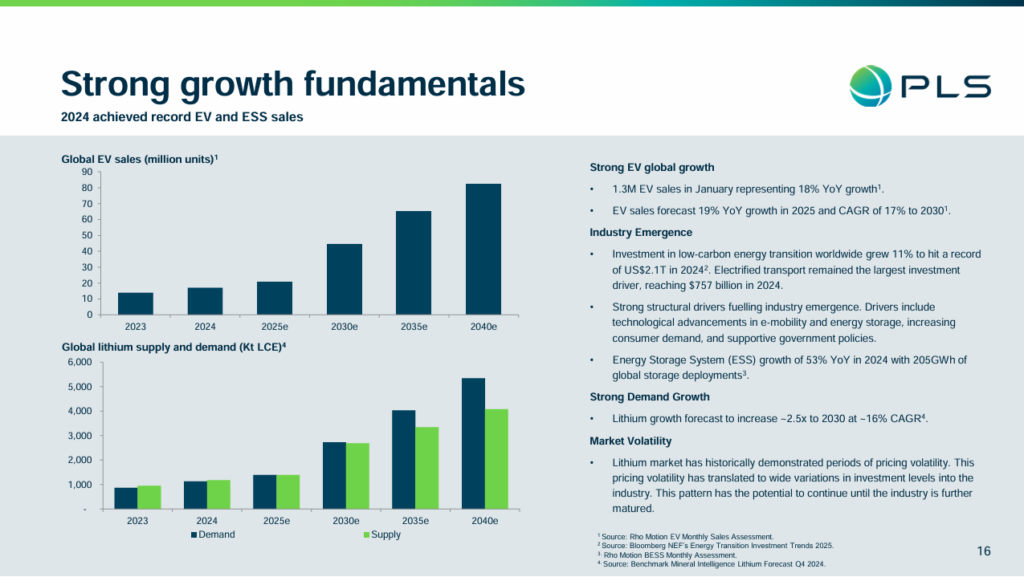
- The combination of operational efficiency improvements, ongoing expansion projects, and the diversification provided by the Latin Resources acquisition positions Pilbara Minerals to capitalize on the expected growth in the global lithium market.
- Guidance:
- While the near-term focus is on ramping up P1000 and integrating new assets, management remains committed to disciplined capital allocation and cost management to navigate current market volatility.
- Operational Optimization:
Market Sentiment
Analyst views remain mixed, reflecting the tension between near-term challenges and long-term strategic positioning:
- Macquarie:
- Neutral rating; target price of $2.30. The broker sees the acquisition as accretive but has trimmed FY25 EPS forecasts by 16%, expecting a 28% rebound in FY26.
- Morgan Stanley:
- Overweight rating; target price of $2.70 with forecasts of FY25 EPS at 1.00 cent and FY26 EPS jumping to 9.00 cents.
- Citi & Ord Minnett:
- Both maintain a Neutral/Hold stance with modest target prices around $2.40–$2.50, noting that operational disruptions and short-term cost pressures are offset by steady project progress.
- Bell Potter & Morgans (another note):
- More bullish with Buy/Add recommendations and targets ranging from $3.00 to $3.15, driven by confidence in the ramp-up of P1000 and improving operational metrics.
- UBS:
- Maintains a Sell rating, highlighting short-term concerns around operational integration post-acquisition and potential headwinds from lower average realized prices.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns