Earnings Polynovo PNV:ASX
- Overview
PolyNovo Limited has demonstrated robust financial performance in the first half of FY25, marked by significant revenue growth and strategic advancements in product development and infrastructure. Key highlights include the successful launch of NovoSorb MTX in the U.S., expansion of the product pipeline, and substantial investments in new manufacturing and innovation facilities in Port Melbourne. The company continues to strengthen its market position through increased sales, enhanced R&D efforts, and strategic financial initiatives.
- Financial Performance
Key Metrics
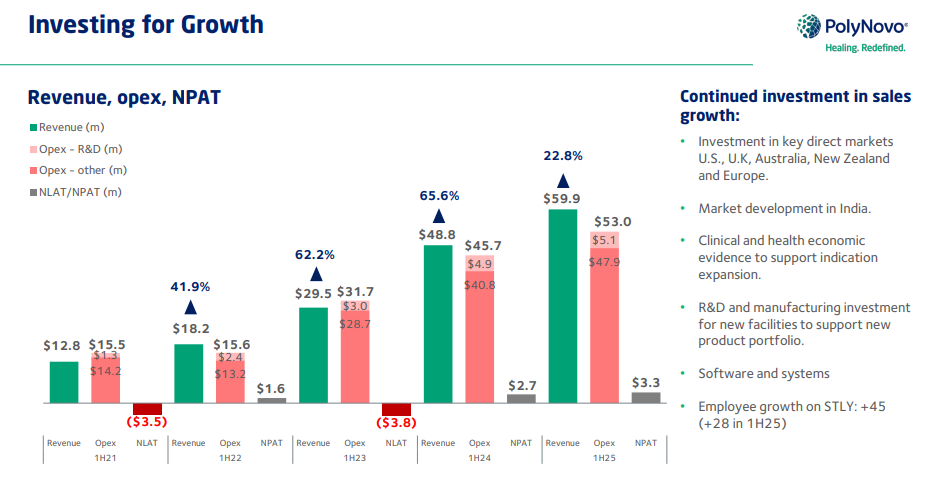
- Total Group Revenue (1H FY25): A$59.9 million, up 22.8% compared to 1H FY24.
- Sales Growth (H2 2024): 28% year-over-year increase.
- Net Profit After Tax (1H FY25): A$3.3 million, a 23.9% increase from the previous year.
- Employee Count: Increased by 19.0% to 282 in 1H FY25.
- Capital Expenditure (1H FY25): A$5.1 million, a 361.2% increase from 1H FY24.
- Revenue from Indian Operations (H2 2024): A$544,000, up 73.1% year-over-year.
- Basic Earnings Per Share (H2 2024): $0.48 vs $0.39 in 1H FY24.
Revenue & Growth Trends
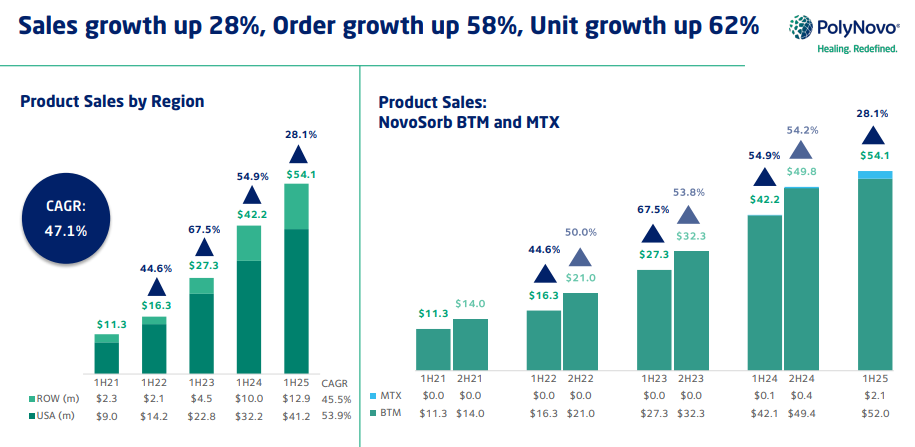
- Overall Sales: A$54.1 million in 1H FY25, representing a 28.1% increase from A$42.2 million in the same period last year.
- U.S. Sales: A$41.2 million, up 27.9% year-over-year.
- Rest of World (ROW) Sales: A$12.9 million, reflecting a 28.6% increase.
- BARDA Revenue: A$5.4 million in 1H FY25, a 10.2% increase from A$4.9 million.
Profitability Metrics
- Net Profit After Tax: A$3.3 million in 1H FY25, up 23.9% from A$2.7 million in 1H FY24.
- EBITDA: $7.251 million in FY25 vs $1.927 million in FY24, showcasing substantial improvement.
- Basic Earnings Per Share: Increased to $0.48 from $0.39.
- Guidance and Expectations
- The company plans to continue capturing market share by introducing new products and expanding into new markets.
- Ongoing discussions with the FDA for pediatric third-degree burn indications signal potential future revenue streams.
- Construction of the new manufacturing facility and Innovation Centre in Port Melbourne is on track, expected to be operational by December 2025 and June 2025, respectively.
- Management remains focused on balancing efforts between the U.S. and ROW to drive market development and expand treatment areas.
- Competitive Landscape
- PolyNovo is positioning itself strongly within the plastic and reconstructive surgery sector, leveraging the NovoSorb platform to differentiate its product offerings.
- The successful launch of NovoSorb MTX in the U.S. and the expansion of product sizes and thicknesses enhance the company’s competitive edge.
- Strategic investments in R&D and new manufacturing capabilities support sustained growth and innovation, crucial for maintaining market leadership.
- Strategic Considerations
Operational Initiatives
- Expansion of the sales force and customer base has resulted in increased market penetration, particularly in the U.S.
- Multiple clinical advisory councils have been held to drive innovation and new product development.
Capital Allocation Plans
- Significant capital expenditure on new manufacturing facilities and the Innovation Centre to support future growth.
- Issued share capital amounting to $157k and increased share-based payments as part of strategic financing measures.
Impact on Outlook
- Investments in infrastructure and R&D are expected to bolster long-term growth prospects by enabling the company to treat millions more patients and expand its product offerings.
- The new facilities will enhance production capabilities and foster innovation, positioning PolyNovo for sustained competitive advantage.
- Reporting Period: 07/2024-12/2024
Key Activities and Developments
- Launched NovoSorb MTX in the U.S., generating A$2.1 million in sales during 1H FY25.
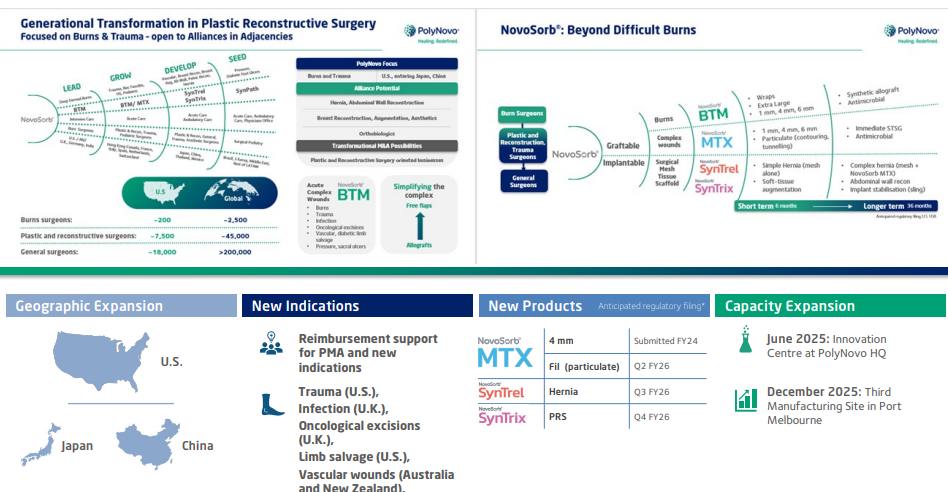
- Advanced the product pipeline for NovoSorb BTM and MTX with additional sizes and thicknesses.
- Entered the pre-clinical stage for hernia repair and plastic reconstructive mesh products.
- Achieved pivotal trial enrollment for full thickness burns indication and began FDA discussions for pediatric applications.
- Constructed and finalizing the design of new manufacturing and Innovation Centre facilities in Port Melbourne.
- Received a $2,000,000 Industry R&D Infrastructure grant to support R&D and construction projects.
- Engaged Spencer Stuart for board skills and succession planning, including sourcing a replacement for Bruce Rathie.
- Initiated leasing of an Innovation Centre with a term of 5 years and 5 months, plus two renewal options.
Results versus Analyst/Broker expectation
Revenue Growth
The company’s revenue growth has exceeded broker expectations. While Morgans projected a 18.4% increase to $125.2m for FY25, the actual results show a 22.8% increase in total group revenue for 1H FY25, reaching A$59.9 million. This suggests PolyNovo is on track to surpass the more conservative broker estimates.
Profit
The company reported a Net Profit After Tax of A$3.3 million for 1H FY25, a 23.9% increase from the previous year. This aligns with Bell Potter’s expectation of continued profitability following the maiden profit in FY24.
Sales Growth
While Macquarie forecasted 43% sales growth for FY25, the actual results show a 28% year-over-year increase in H2 20241. Although lower than Macquarie’s projection, this growth rate is still substantial and aligns more closely with Morgans’ expectation of 20% annual growth over the next three years.
Overall, PolyNovo’s performance appears to be meeting or exceeding most broker expectations. The company’s strong revenue growth, improved profitability, and strategic expansions in both product development and manufacturing capacity suggest a positive trajectory that aligns with the optimistic outlook presented by the brokers.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns