The threat of U.S. tariffs on Australian pharmaceutical exports, particularly those produced by major companies like CSL has seen the stock reach 52-week lows. The Trump administration’s proposed tariffs aim to bolster domestic manufacturing but are expected to increase costs for American consumers due to limited short-term alternatives for certain medical products.
The headlines have triggered panic in stocks like CSL, which are misguided and a strong buying opportunity.
BUY under $240
Key points include:
- Tariff Impact:
The headline “Australian pharmaceutical exports, valued at $1.6 billion annually, could face significant disruptions. CSL, a major exporter of blood and plasma products, is particularly vulnerable”
The reality: the lack of viable short-term substitutes for many pharmaceutical products suggests that consumers are not highly price-sensitive in this sector
- Investor Confidence:
The Headline: “The uncertainty surrounding tariffs and global trade tensions has negatively affected investor confidence in biotech firms, with share prices for companies like CSL, Cochlear, and Mesoblast declining”
The reality: the Healthcare sector is an “essential” and far less effected by economic cycles, just because the index is falling, doesn’t mean every sector is a sell
- Pharmaceutical Benefits Scheme (PBS):
The Headline: U.S. pharmaceutical companies have long criticized Australia’s PBS for subsidizing cheaper generics and delaying access to cutting-edge drugs. While Australian officials aim to streamline approval processes, they remain committed to preserving the PBS’s core structure.
The reality: The US can impose tariffs, but they will only be hurting themselves and their citizens, not Australian Biotechs.
Business Overview & Fundamentals
CSL operates in the biopharmaceutical sector with three key segments: CSL Behring (plasma products), CSL Seqirus (influenza vaccines), and CSL Vifor (iron deficiency and nephrology). The company demonstrated solid FY2024 performance with 11.2% revenue growth to $14.80B and healthy margins (52.1% gross profit, 17.9% net income).
Key Metrics | Value | YoY Change | Comment |
Revenue | $14.80B | +11.2% | Strong growth trajectory 💪 |
Operating Income | $3.90B | – | Solid profitability |
Net Margin | 17.9% | – | Healthy profit conversion |
ROE | 15.9% | – | Good capital efficiency |
Debt/Equity | 70.2% | – | Manageable leverage 👍 |
Investment Thesis
CSL offers a compelling long-term investment case based on:
- Strong competitive position in plasma products and vaccines
- Consistent profitability with 15.9% ROE
- Significant analyst confidence with 41% upside potential
- Low beta (0.35) offering defensive characteristics
- Consecutive dividend increases for 3 years with 32-year payment history
The recent price weakness appears disconnected from fundamentals, potentially offering a buying opportunity for long-term investors despite near-term technical weakness.
Valuation & Market Sentiment
CSL currently trades at a P/E of 37.2x, which appears expensive at first glance. However, this premium valuation reflects CSL’s quality business model and growth potential. The stock has underperformed with a -10.9% 1-year return, creating a potential entry point.
Valuation Metric | Current | Analyst Target | Gap |
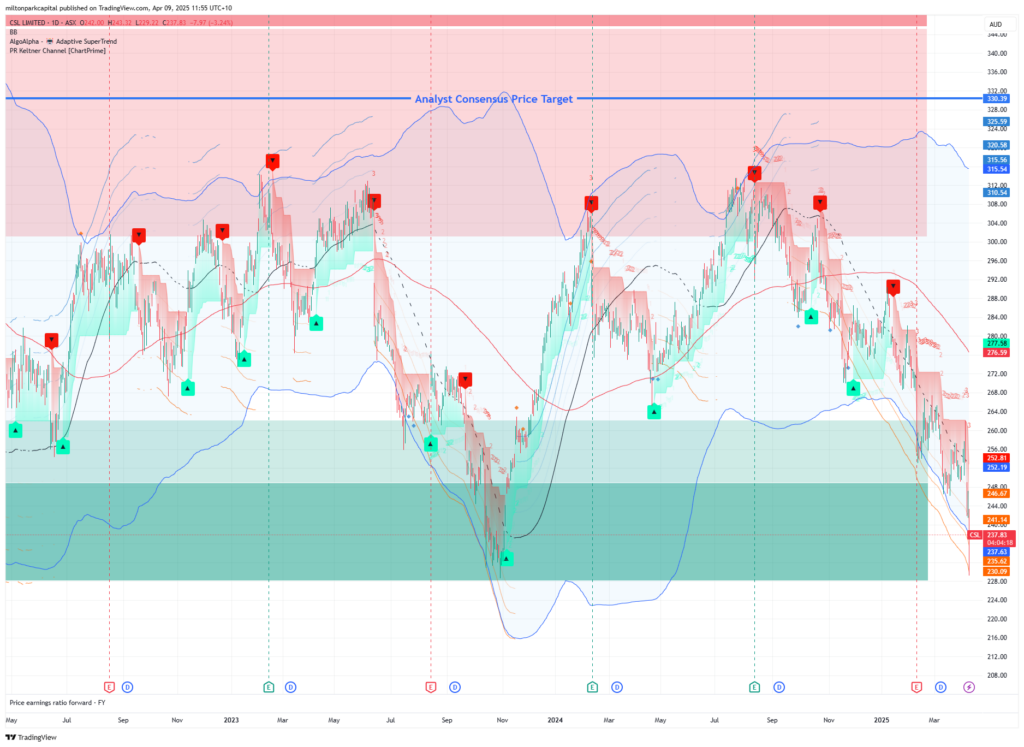
Current Price | A$230 | A$327 | +42% upside 🔑 |
52-Week Range | A$229- A$313.55 | – | Trading at bottom ⚠️ |
Analyst Sentiment & Technical Signals
The stock has overwhelming analyst support with a “Strong Buy” consensus. Price targets range from A$310 to A$360 with a mean of A$327, suggesting significant upside potential.
Recent Broker Updates
UBS (02/04/2025)
- Recommendation: Buy with a target price of $310.00 (26.12% upside).
- Key Points:
- Biotech stocks have been under pressure, partly linked to the resignation of Peter Marks (US FDA).
- UBS remains confident in the sector and continues to see opportunities in Telix Pharmaceuticals and CSL.
- Concerns about flu vaccine demand in the US are noted but do not deter UBS’s positive outlook on CSL.
- No changes to the Buy rating or target price.
Morgan Stanley (31/03/2025)
- Recommendation: Overweight with a target price of $313.00 (27.34% upside).
- Key Points:
- Analyzes potential impact of US tariffs on pharmaceutical products, but current share price already reflects downside risks.
- Tariffs would apply to US sales from non-US markets, but most manufacturing and plasma collection occur within the US.
- Scenario analysis suggests valuations between $256 and $282, all above the current price.
- No changes to the Overweight rating or target price.
Technical indicators show bearish momentum across multiple timeframes, with “Strong Sell” signals on hourly, daily, weekly, and monthly charts.
RSI of 32.83 indicates the stock is approaching oversold territory.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.