Telix Pharmaceuticals Q1 2025 Results and Business Update – Summary
Financial Performance
Telix Pharmaceuticals reported unaudited Q1 2025 revenue of US$186 million, a 62% increase year-over-year (Q1 2024: US$115 million) and a 31% rise quarter-over-quarter (Q4 2024: US$142 million).
Revenue breakdown:
US$151 million from global sales of Illuccix®, up 35% year-over-year and 9% quarter-over-quarter.
US$33 million from RLS Radiopharmacies, reflecting two months of contribution since the January 2025 acquisition.
The company reaffirmed its full-year 2025 revenue guidance of US$770–800 million, including Illuccix® sales in approved markets and 11 months of RLS revenue.
R&D expenditure is expected to increase 20–25% over FY 2024.
Operational and Strategic Highlights
Illuccix® continues to gain market share and maintain price stability. Telix is now the only company with two FDA-approved PSMA-PET imaging agents (Illuccix® and Gozellix®), broadening its reach in prostate cancer imaging.
The RLS acquisition has expanded Telix’s U.S. manufacturing footprint, supporting further growth and mitigating risks from global trade dynamics.
Gozellix® received FDA approval in March 2025, offering a longer shelf life and broader distribution for prostate cancer imaging. U.S. commercial launch is set for Q2 2025, with Cardinal Health and RLS as distribution partners.
Illuccix® received positive regulatory decisions in the EU, UK, and Brazil, with launches commencing in these markets in Q2 2025.
Therapeutics and Pipeline Progress
The Phase 3 ProstACT™ Global trial (TLX591 for prostate cancer) continues recruitment, with a Part 1 readout expected in H1 2025.
The Phase 2 IPAX-Linz trial (TLX101 for brain cancer) reported positive preliminary results, with good tolerability and no serious adverse events.
IND submissions for pivotal trials of TLX101 (brain cancer) and TLX250 (kidney cancer) are on track for 2025, pending regulatory approval.
The first patient was dosed in the Phase 1 ZOLAR trial (TLX300-CDx for soft tissue sarcoma).
Telix acquired FAP-targeting radiopharmaceutical candidates (lead compound now TLX400) and the therapeutics assets of ImaginAb, Inc., adding next-generation candidates and a biologics research facility.
The company developed a new generator technology for lead-212, enhancing isotope supply for targeted alpha therapy.
Manufacturing and Supply Chain
The Brussels South (Seneffe) facility received GMP accreditation, enabling commercial radiopharmaceutical production.
Telix expects no material impact from recent U.S. trade tariffs or Chinese export controls, given its U.S.-based manufacturing and lack of reliance on rare earth elements used in semiconductors.
Board Changes
H Kevin McCann AO will retire as Board Chair in May 2025, succeeded by Tiffany Olson.
Marie McDonald and Anne Whitaker joined as Non-Executive Directors, with committee appointments as part of board renewal.
Guidance and Risks
Revenue guidance is subject to economic and regulatory factors, including product approvals, reimbursement decisions, and competitive developments.
Investors are cautioned about forward-looking statements due to inherent risks and uncertainties.
Company Overview
Telix is a global biopharmaceutical company specializing in radiopharmaceuticals for oncology and rare diseases, with operations in Australia, the U.S., Brazil, Canada, Europe, and Japan.
Key products include Illuccix® (prostate cancer imaging), Gozellix® (next-generation PSMA-PET agent), Scintimun® (bone infection imaging), and SENSEI® (surgical gamma probe).
Key Points of Comparison
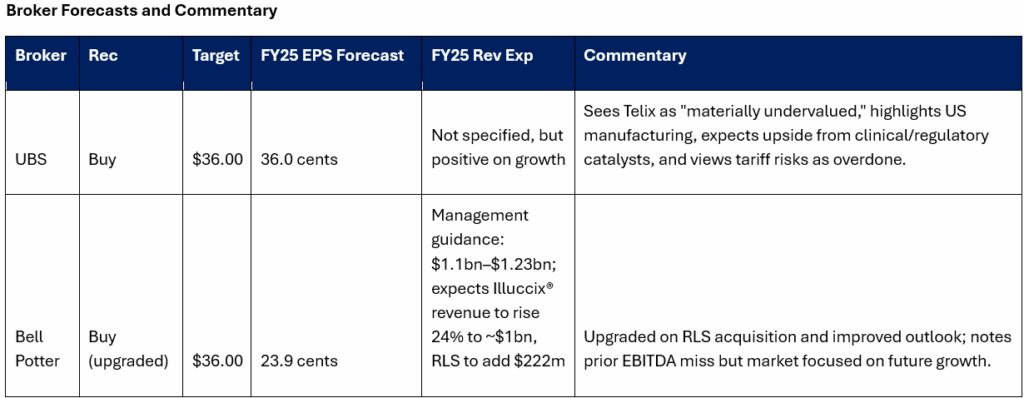
- Revenue Guidance: Telix’s reaffirmed FY2025 guidance of US$770–800 million is below the management guidance referenced by Bell Potter ($1.1–1.23 billion) and the broker’s implied expectations for Illuccix® plus RLS revenue. This suggests Telix is taking a conservative approach, possibly not yet including upside from new product launches (e.g., Gozellix® reimbursement in the US, Illuccix® in new ex-US markets).
- Q1 Run Rate: The Q1 revenue of US$186 million annualizes to US$744 million, which is at the lower end of Telix’s full-year guidance. This indicates that either further growth is expected in subsequent quarters (from new launches, expanded approvals, or RLS integration), or that management is being cautious in its outlook.
- Broker Sentiment: Both UBS and Bell Potter maintain Buy recommendations with a target price of $36, citing undervaluation, strong US manufacturing, and pipeline catalysts. UBS notes the market is pricing in excessive risk of pipeline failure, and both brokers see the RLS acquisition as a key growth driver.
- Earnings Estimates: Broker EPS forecasts for FY25 (UBS: 36c, Bell Potter: 23.9c) are based on higher revenue assumptions than Telix’s current public guidance, reflecting confidence in further upside from pipeline and commercial expansion.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.