
Buy Recommendation: Findi Limited (ASX: FND)
Findi Limited (ASX: FND) is well positioned for significant share price appreciation, underpinned by two major catalysts: the upcoming IPO of its Indian subsidiary on the Bombay Stock Exchange and the company’s strong FY25 results.
Indian IPO as a Value Catalyst
Findi has appointed DAM Capital and Ambit as lead managers for the IPO of Transaction Solutions International (India) Pvt Ltd (TSI), targeting completion by the end of 2026. The indicated pre-money IPO valuation range for TSI is INR 4,000–5,112 crore (A$727–$926 million), which is a substantial premium to Findi’s current market capitalisation on the ASX. This is supported by the fact that comparable Indian fintech and ATM companies typically trade at much higher valuation multiples than their Australian counterparts. Listing TSI in India is expected to unlock significant value for Findi shareholders, as the Indian market is willing to pay a premium for high-growth, technology-driven financial services companies. The IPO will also provide a direct liquidity event and is a clear step in Findi’s strategy to close the valuation gap between the ASX and Indian exchanges.
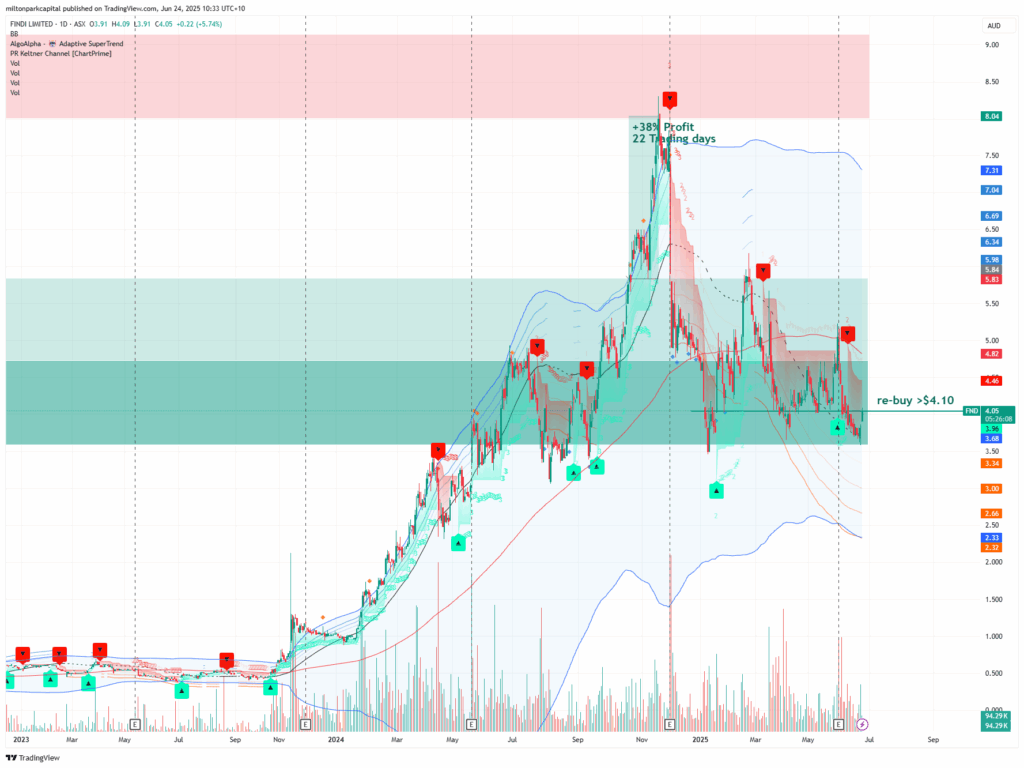
Recommendation: Re-Buy on India IPO Catalyst
Trade: BUY under 4.10 (small allocation)
Target: $>$7.00
Strong FY25 Results and Operational Momentum
Findi delivered record financial performance in FY25, with revenue of $75.5 million (exceeding guidance), EBITDA of $31.4 million, and NPBT of $6.0 million. The company achieved significant operational milestones, including:
Awarded major new ATM contracts with the State Bank of India, Central Bank of India, and Union Bank of India, expected to deliver strong recurring revenue and EBITDA over multi-year contract lives.
Completed the strategic acquisition of Tata’s ATM business and BankIT, expanding both its physical and digital financial services footprint.
Increased digital revenue streams, now representing approximately 25% of total revenue.
Maintained a strong balance sheet with $115.9 million in total cash reserves and $30.2 million in net cash as of March 2025.
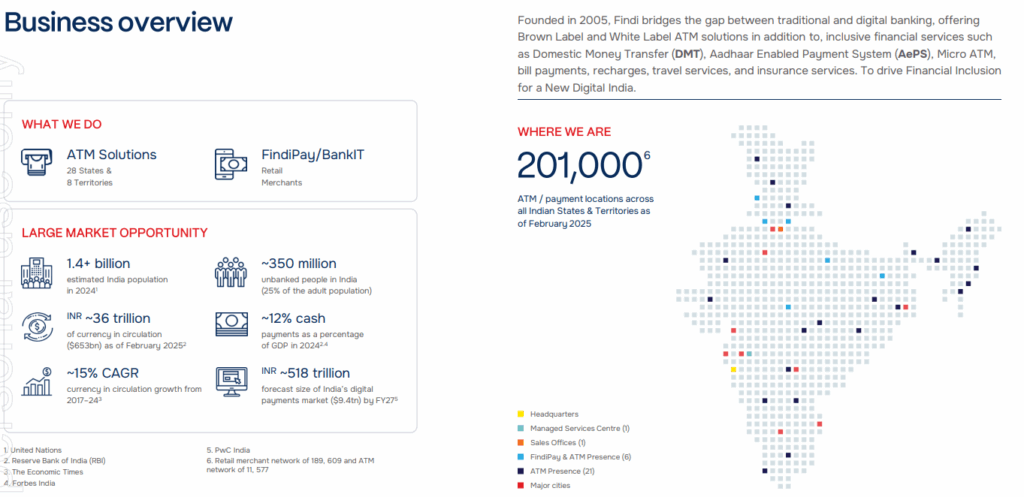
These achievements demonstrate Findi’s ability to scale profitably, execute on strategic acquisitions, and diversify its revenue base. The company is also benefiting from favourable industry tailwinds, with India’s large underbanked population, strong government support for financial inclusion, and rapid growth in both cash and digital payments.
Valuation and Upside
Findi currently trades at a significant discount to Indian-listed peers on an EV/EBITDA basis. The upcoming IPO is expected to drive a re-rating as the market begins to price Findi in line with Indian fintech valuations. Recent capital raisings and institutional support further validate the company’s growth prospects and valuation.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.