Xero has announced it has entered into a binding agreement to acquire 100 per cent of US company Melio, with $3.9 billion in cash and scrip in upfront consideration.
While Xero’s acquisition of Melio is a high-conviction, long-term strategic play to supercharge its US growth, it comes with short-term earnings dilution, integration risks, and heightened exposure to a competitive and evolving US fintech landscape.
Melio brings a world-class platform with high customer satisfaction (NPS 45), a syndication network reaching 18 million SMBs, and a 127% revenue CAGR (FY21–25)
The acquisition is materially dilutive to EPS in the near term but Xeros balance sheet is strong enough to handle the short-term turnaround of Melio. Xero said they will apply their “Rule of 40” to target sustainable growth by FY28, with expected FY28 synergies of ~US$70 million in revenue and ~US$20 million in costs
In many ways, the acquisition show Xero’s frustration at the pace and lack of penetration of the US SMB market, and they are paying at the high end compared to other deals in the space in the last few years, but the strategic fit justifies the premium
We are likely to see short term pain for the share price, but this is likely to be a good long-term buying opportunity due to the disciplined track record of the current management team and CEO
Rationale
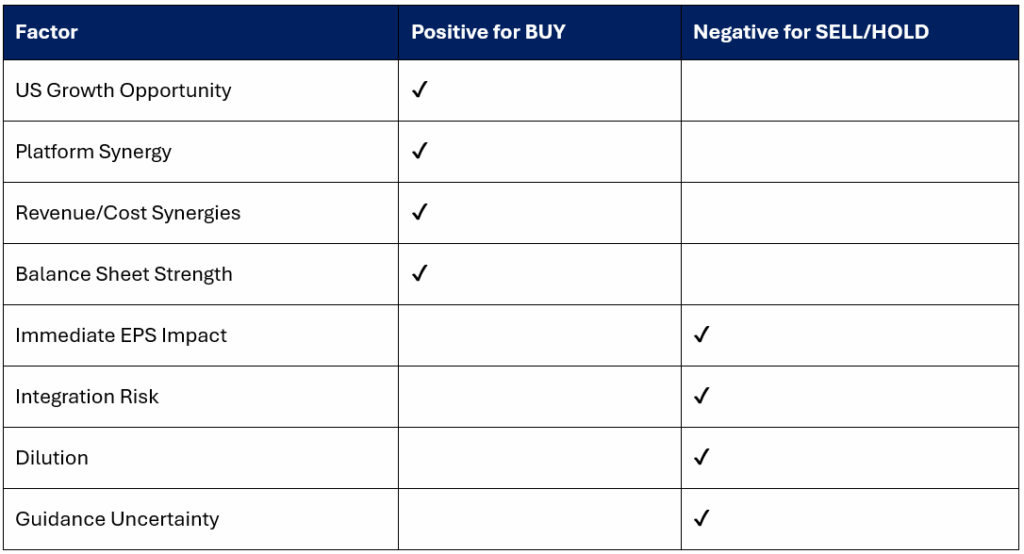
- Transformational US Growth: Xero’s acquisition of Melio is a strategic move to accelerate its US expansion, immediately tripling its North American revenue and average revenue per user. The deal positions Xero to more than double its group revenue by FY28, driven by access to a US$29 billion addressable market and a strong payments platform with proven customer traction and high growth rates.
- Integrated Platform Advantage: By combining Xero’s accounting software with Melio’s payments capabilities, Xero can offer a seamless, integrated solution highly valued by US small businesses. This supports a compelling long-term growth profile and aligns with Xero’s 3×3 strategy to win across accounting, payments, and payroll in its core markets.
- Synergy and Scale: The acquisition is expected to deliver significant revenue (US$70 million) and cost (US$20 million) synergies by FY28, with further upside from cross-selling, expanded reach, and operational efficiencies. Melio’s syndication network, powering 3,500 financial institutions and reaching 18 million SMBs, provides scalable, cost-effective distribution.
- Financial Strength: Xero maintains a strong balance sheet post-acquisition, with pro forma net debt/EBITDA at 2.3x and ongoing positive cash flow supporting deleveraging.
Key Risks and Short-Term Considerations
- Immediate EPS Dilution: The deal is dilutive to earnings per share in the near term due to Melio’s current loss-making operations (FY25 pro forma EBITDA -NZ$127m, FCF margin -60%). The combined entity’s FY25 pro forma EBITDA and free cash flow margin are both lower than Xero standalone.
- Execution and Integration: Realising the full value of the acquisition depends on successful integration, retention of key Melio talent, and delivery of projected synergies. There are also risks from increased exposure to the competitive US payments market and macroeconomic volatility.
- Dilution and Accounting: The capital raise and scrip consideration dilute existing shareholders. Acquisition accounting (goodwill, intangibles) may further impact reported profits in the near term.
- No Updated FY26 Guidance: Xero has not updated its FY26 outlook to reflect the acquisition, so near-term earnings visibility is limited.
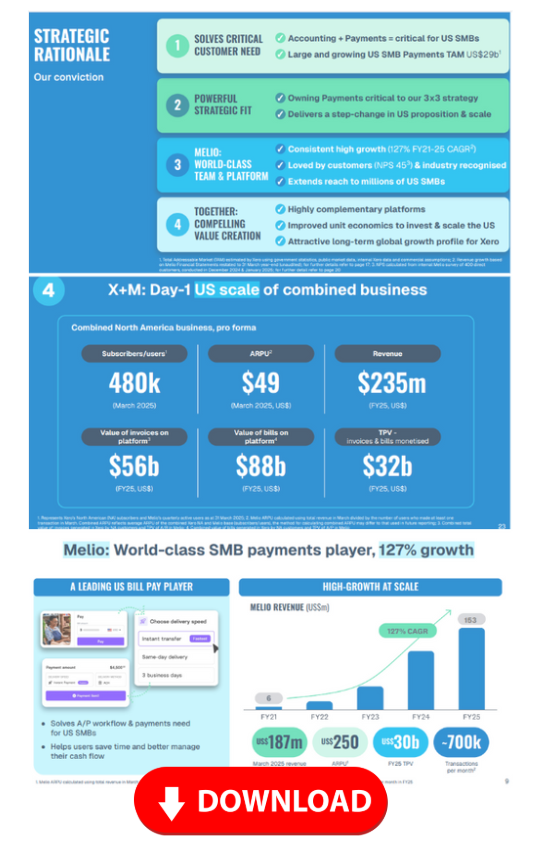
Xero is paying an upfront US$2.5 billion for Melio, which equates to about 13.4 times Melio’s March 2025 annualised revenue, or 9.7 times if you include the expected FY28 revenue synergies. This is a high multiple, especially for a company that is not yet profitable and has a gross margin (19%) well below Xero’s (89%) and some listed peers. However, Melio is growing rapidly (127% revenue CAGR FY21–25) and provides Xero with a strategic entry into the US SMB payments market, which is a large, underpenetrated, and fast-growing segment.
When compared to recent transactions and trading multiples in the SaaS and payments sector, Xero’s price is within the range for high-growth, high-potential platforms. For example, leading vertical SaaS and payments companies like Toast and Fortnox have traded at next-twelve-month revenue multiples of 11.4x to 19.6x. Melio’s multiple is at the upper end of this range, but not out of line for a business with its growth profile and strategic value.
In summary, Xero is paying a full price—possibly a premium—for Melio, but the valuation is consistent with recent deals for high-growth payments and SaaS companies in the US. The premium reflects Melio’s rapid growth, its unique US distribution network, and the strategic fit with Xero’s long-term US ambitions. Whether the price proves justified will depend on Xero’s ability to deliver the expected revenue growth, synergies, and successful integration. If those are achieved, the acquisition price could be validated; if not, the high multiple could weigh on returns.
Buy Xero for long-term growth if you are willing to accept short-term earnings dilution and execution risk. The acquisition is a bold, strategic step to capture a large, underpenetrated US market and transform Xero’s global growth profile. Short-term or risk-averse investors may prefer to hold or wait for evidence of successful integration and margin recovery, but the long-term upside is compelling for growth-oriented shareholders.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.