
Northern Star Resources (NST:ASX) stands out as a high-quality gold producer with a proven track record of growth, disciplined capital management, and a clear path to future expansion. While recent market sentiment has been cautious due to higher cost and capital expenditure guidance, the long-term investment case remains compelling.
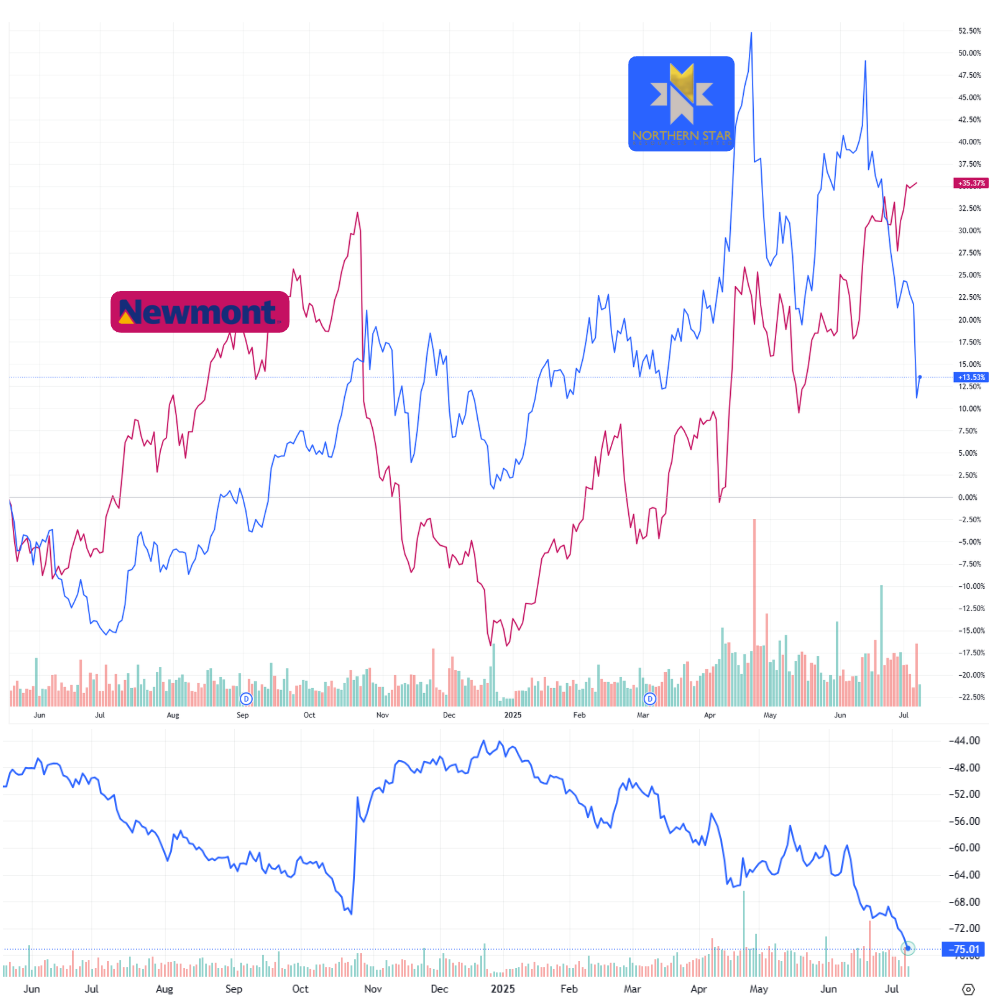
Trade Plan: Sold Newmont to buy Northern Star on the 17th of June @ $21. due to poor price action we only Bought 50% of intended allocation
BUY the remaining 50% <$17.20 (20% saving)
Target >$24.00 (+26%)
Growth and Value Opportunity
- Undervalued Stock: NST trades nearly 17% below the average analyst target, offering significant upside potential.
- Strong Historical Returns: Delivered over 160% total return in three years and more than 35% in the past year, outperforming many peers.
- Earnings Growth: EPS is forecast to nearly double in FY25, with further growth in FY26, despite sector headwinds.
Operational Strength
- FY25 Delivery: Achieved 1.634 million ounces of gold sold, within revised guidance, demonstrating operational reliability.
- FY26 Guidance: Management projects 1.7–1.85 million ounces of gold sold, with production weighted toward the second half as major projects come online.
- Major Projects: The KCGM Mill Expansion and Hemi Development Project are set to drive step-change growth from FY27, positioning NST as a global leader in low-cost gold production.
Financial Health and Shareholder Returns
- Solid Balance Sheet: Low debt/equity and strong liquidity support ongoing investment and resilience.
- Consistent Dividends: 14 consecutive years of payments, a 2.4% yield, and a robust five-year dividend growth rate.
- Free Cash Flow: Healthy free cash flow generation underpins both dividends and growth capital.
Analyst and Broker Support
- Positive Ratings: Most major brokers maintain “Buy” or “Outperform” ratings, even after trimming targets to reflect higher costs and capex.
- Sector Leadership: NST remains a preferred value play in the gold sector for investors seeking growth and income.
Risks and Timing
- Short-Term Volatility: The share price has dropped recently due to higher cost guidance and heavy capex, with technical indicators still weak. However, this may present a rare entry point for patient investors.
- Execution Required: Delivery on new projects and cost control will be critical to unlocking value.
Bottom Line:
Northern Star offers a rare blend of growth, value, and income in the gold sector. For investors willing to look past near-term volatility and cost inflation, NST provides exposure to a high-quality miner with a clear path to future upside. The company’s disciplined approach to capital, strong project pipeline, and commitment to shareholder returns make it a compelling long-term buy at current levels.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.