TRIM 1/3 of CSL Holding
We have been overweight CSL since April, buying at $260, $240 & $230 (for an average price of $243) and we recommend lightening to our normal allocation size, taking an 11% profit and switch to Sigma Healthcare
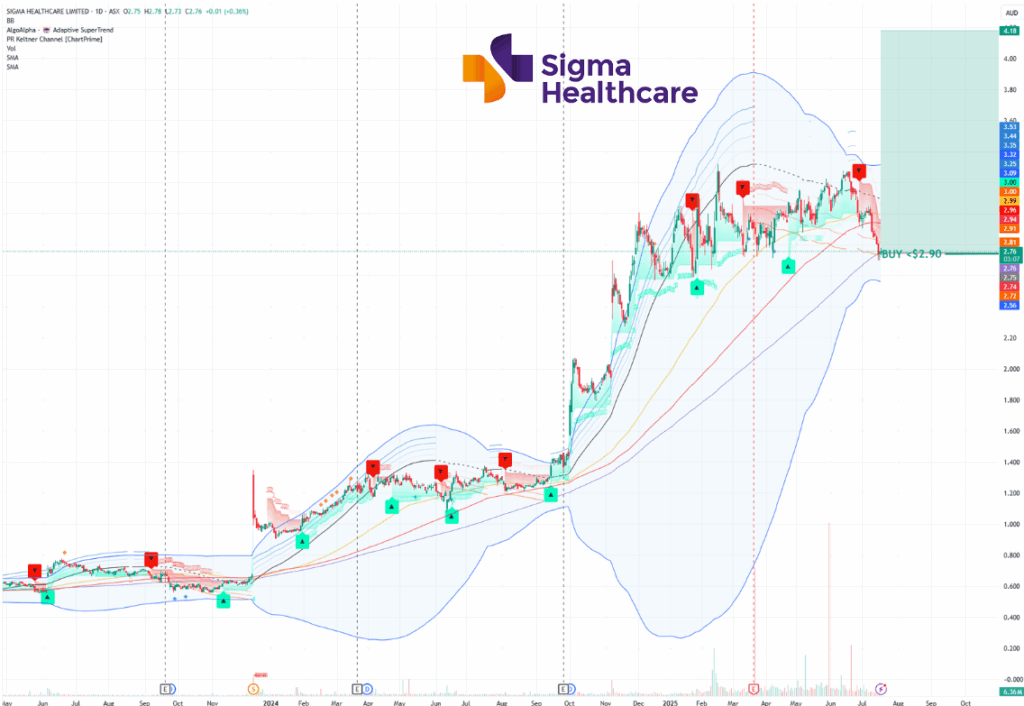
Buy Recommendation: Sigma Healthcare (ASX:SIG)
Investment Thesis
Sigma Healthcare (ASX:SIG) is the dominant force in Australia’s pharmacy sector and after the recent merger with Chemist Warehouse, we expect to see solid earnings results from the merged entity in September.
The recent merger with Chemist Warehouse positions Sigma as a central player in both retail and wholesale pharmacy, underpinned by major operational and strategic advantages.
Key Drivers for a Buy Rating
- Transformational Growth from Chemist Warehouse Merger
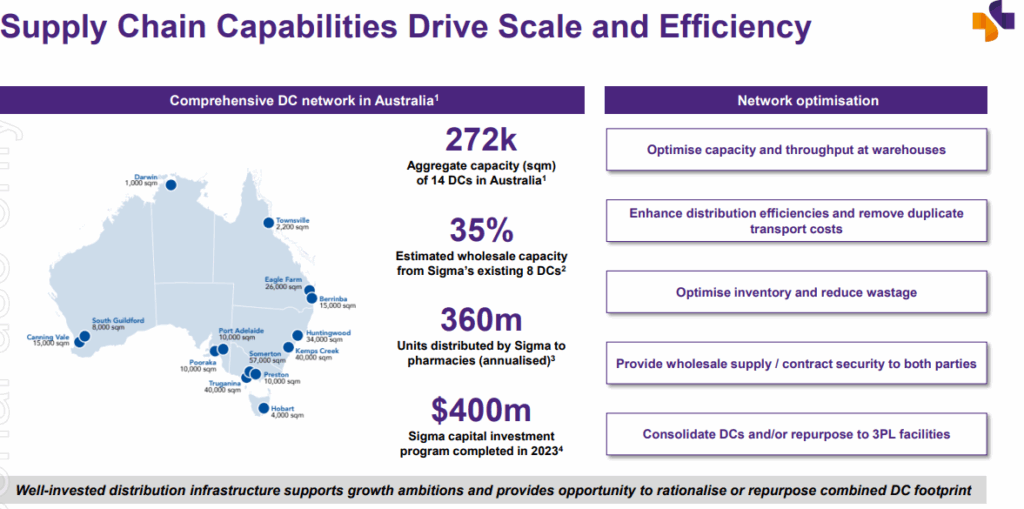
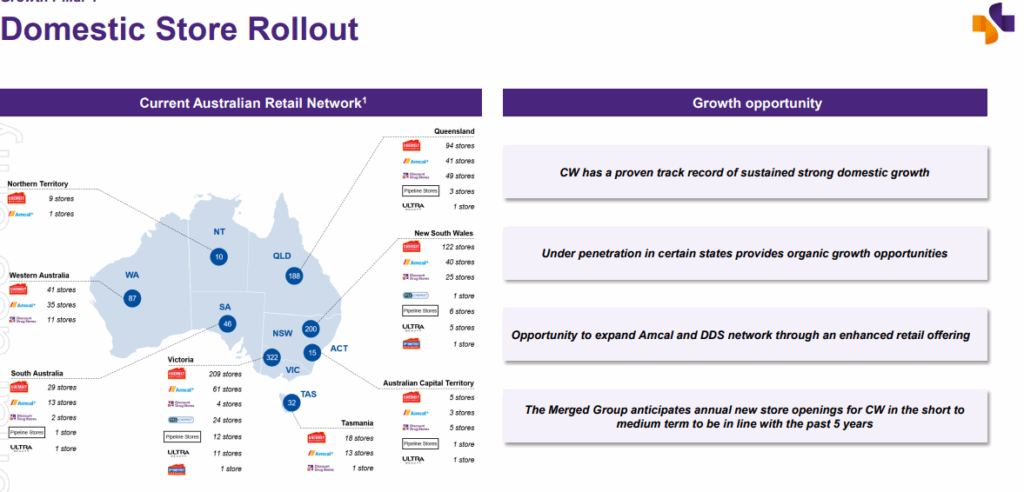
- Sigma is now Australia’s largest retail pharmacy franchisor, with nearly 880 domestic and over 80 international stores, supported by a vast wholesale customer network and 15 distribution centers.
- Chemist Warehouse brings a strong track record, achieving almost two decades of continuous sales growth, with network sales reaching $9.6 billion in the last twelve months and double-digit like-for-like sales growth.
- The merger projects annual cost synergies of $60 million, with active management driving support center integration and distribution network optimization.
- Robust Financial Momentum
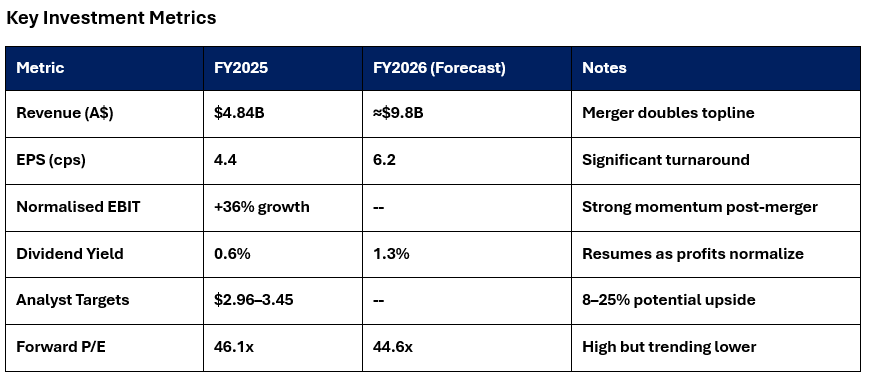
- Sales surged 45.7% to $4.84 billion in FY2025, with forecasts pointing to a doubling of revenues amid full merger impact.
- Financial turnaround is anticipated, with future EPS projected to rise sharply and profits expected to return to positive territory following recent net losses.
- Dividend payments are forecast to resume, providing shareholders with attractive yield growth as profits normalize.
- Valuation Upside
- Analyst price targets range between $2.96–3.45 per share, representing solid upside from current levels.
- Market signals suggest the shares are oversold with relatively low volatility, indicating limited near-term downside.
Risks and Mitigating Factors
- Margins remain thin, with an EBITDA margin below 1% and elevated leverage post-merger. However, significant cost synergies and operational improvements are expected to drive margin recovery.
- The integration and execution of cost-saving initiatives carry some risk, but a highly experienced management team with a history of successful retail integrations adds confidence.
- FY25 financials may be complex due to the transition period and partial inclusion of legacy Sigma results, but this is a short-term accounting issue.
Bottom Line: Sigma Healthcare offers strong medium-term potential for investors who can look past short-term margin pressure and transition-related complexity. The newly combined group’s unrivaled market position, aggressive sales growth, and a clear pathway to profitability and dividend resumption support a Buy recommendation, with upside toward $3.10–3.45 over the next 12 months.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns