
Shares have dropped on a routine SEC enquiry after the company disclosed earlier this morning that they were on track for guidance.
While an SEC subpoena on drug development disclosures (disclosed July 22) may have contributed to the price dip, such inquiries are common in biotech (e.g., Biogen, CytoDyn precedents) and often resolve without action;
ADD >$22.50
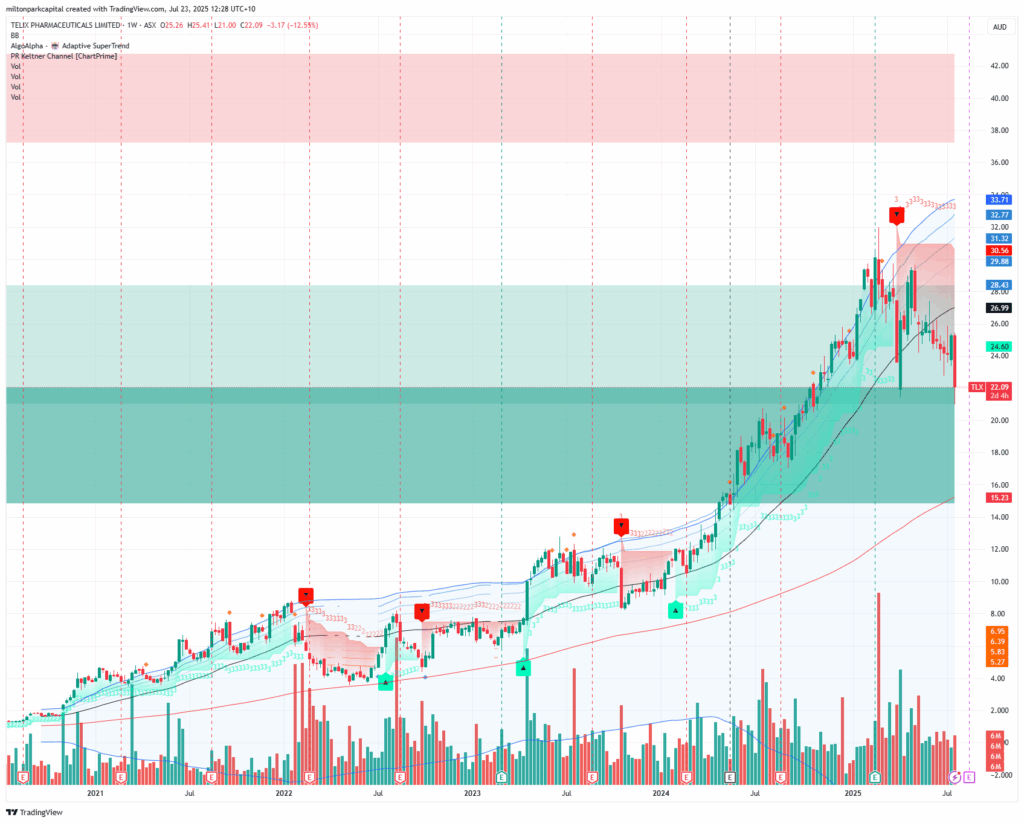
ADD Recommendation: Telix Pharmaceuticals (TLX:ASX)
ADD (Target Price: $32)
Based on the November 2024 MPC Markets analysis, we maintain a Growth recommendation for TLX, highlighting its undervalued position at a 5.5x multiple on 2024 estimated revenue (vs. peers at 7.9x) amid strong Illuccix performance and a deep radiopharmaceutical pipeline. With the share price now down to $22—likely pressured by recent market volatility—this presents an attractive entry point for accumulation, implying ~45% upside to a justified 8x multiple target. Telix’s experienced leadership, robust Q3 2024 revenue growth (+55% YoY to ~US$135M), and reaffirmed FY2024 guidance (US$490-510M) underscore its commercial momentum and M&A potential in the consolidating sector.
Context from Today’s Update (July 23, 2025):
TLX reported record Q2 2025 revenue of $204M (+63% YoY), reaffirming FY2025 guidance at $770-800M USD, driven by Gozellix U.S. launch (first doses delivered) and sustained demand for core products like Illuccix. Pipeline advances include ProstACT Phase 3 enrollment milestone and Zircaix FDA decision expected August 27, 2025. While an SEC subpoena on drug development disclosures (disclosed July 22) may have contributed to the price dip, such inquiries are common in biotech (e.g., Biogen, CytoDyn precedents) and often resolve without action; TLX reaffirmed guidance, signaling no material impact.
Analyst Consensus:
Brokers remain bullish, with Bell Potter (Buy, $34 TP) emphasizing Zircaix as a FY2026 revenue catalyst and UBS (Buy, $36 TP) highlighting Gozellix diversification. Consensus EPS forecasts support growth: FY2025 at 23.8-36.0c, FY2026 at 56.9-76.0c. Near-term catalysts (Zircaix approval, Gozellix reimbursement from Oct 1) outweigh risks like regulatory delays or competition, reinforcing ADD stance for long-term holders.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns