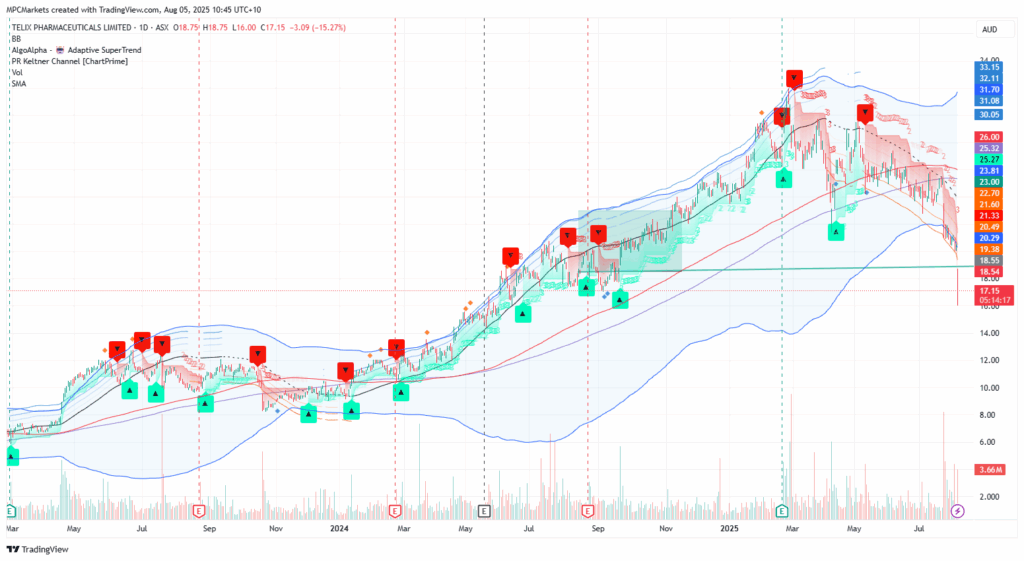
As of August 5, 2025 (mid-morning AEST), Telix Pharmaceuticals (TLX) is trading around A$16.84–16.75, down approximately 17% from its previous close of A$20.24. This sharp intraday decline aligns closely with your noted price of $17 (assuming AUD). Below, I’ll address the reasons for this correction based on recent developments and why it still represents a strong buying opportunity to add to positions.
Why the Recent Correction?
The current drop appears to be an extension of investor concerns stemming from a U.S. Securities and Exchange Commission (SEC) subpoena disclosed on July 22, 2025, rather than any new fundamental setback. Here’s a breakdown:
- Trigger: Lingering SEC Subpoena Uncertainty: The subpoena relates to disclosures around Telix’s prostate cancer therapeutic candidates (specifically, investigational disclosures that may have been misinterpreted as promotional). While Telix has emphasized full cooperation, no formal allegations or charges, and that the probe does not impact its core operations or pipeline, the issue remains unresolved. Recent analyst notes and media coverage (e.g., Motley Fool article from today) highlight this as a key factor in today’s plunge, with the market viewing it as a regulatory overhang that could lead to potential fines, delays, or reputational risks. This initially caused a 16% drop on July 23, and today’s move seems like renewed selling pressure, possibly amplified by the company’s August 5 announcement recasting historical financials into USD—which explicitly references reviewing risk factors in recent SEC filings, reminding investors of the ongoing probe.
- Broader Market Context: Today’s decline coincides with a volatile ASX session, where the S&P/ASX 200 is down amid global economic jitters (e.g., U.S. recession fears, interest rate speculation). However, TLX’s outsized drop (17% vs. ~2–3% for the index) suggests company-specific sensitivity. Biotech stocks like Telix are particularly prone to sentiment swings due to their reliance on regulatory approvals and pipeline progress. Earlier in 2025, Telix experienced smaller dips (e.g., 6% in April after an FDA application rejection for a different product, and ~5% in June post-platform launch), but the SEC issue has been the dominant narrative since July.
- No New Negative Fundamentals: The August 5 recast announcement itself is neutral-positive, shifting reporting to USD (effective January 1, 2025) to better reflect ~75% USD-denominated revenue/costs and reduce FX volatility. It includes unaudited recasts for 2023–2024 and H1 2025 but doesn’t reveal adverse data—OPEX was efficient at 36% of revenue in H1 2025. If anything, this enhances transparency ahead of the full H1 results on August 21. However, the market may be overreacting to the reminder of SEC-related risks mentioned in the legal notices.
In summary, this isn’t driven by operational failures (e.g., revenue misses or pipeline halts) but by regulatory uncertainty and broader sentiment, leading to an exaggerated sell-off.
Why It’s Still a Good Buying Opportunity
Despite the correction, Telix’s fundamentals are intact, and the current price represents a discounted entry point for long-term growth in the high-potential radiopharmaceutical sector. Here’s why adding to positions makes sense:
- Robust Financial Momentum: Telix reaffirmed FY25 revenue guidance of US$770–800 million (A$1.18–1.23 billion) after strong H1 results (US$388 million, beating expectations) and Q2 growth of 63% YoY to US$204 million. The USD shift simplifies global comparisons and minimizes FX distortions, positioning Telix favorably against peers. With a healthy cash position and efficient scaling, the company is well-equipped to weather short-term noise.
- Near-Term Pipeline Catalysts: Key milestones could quickly shift sentiment:
- Zircaix (TLX591-CDx) FDA approval expected in August 2025, expanding prostate imaging.
- Gozellix pricing decision by October 2025, with HCPCS code already assigned.
- TLX101 glioblastoma trials advancing with Australian ethics approval. These align with rising demand for targeted cancer diagnostics/therapeutics, where Telix’s flagship Illuccix continues to drive revenue.
- Attractive Valuation Post-Dip: At ~A$17, TLX trades at a forward P/E of around 47x based on FY25 EPS consensus (~36 cents from analysts like Bell Potter and UBS), down from higher multiples pre-subpoena. This undervalues its 50%+ expected revenue CAGR. Analyst targets remain A$21.79–23.41 (implying 28–38% upside), with some pre-drop targets at A$34–36. The sell-off appears overdone, especially as the SEC probe is disclosure-focused, not product-related.
- Risk Mitigation and Upside Potential: While the subpoena warrants monitoring (potential for resolution without material impact), Telix’s diversified pipeline and U.S.-centric operations provide resilience. Upcoming H1 2025 results (August 21) and investor webcast could act as positive catalysts, potentially tightening consensus and driving a rebound. No dividends are expected (focus on R&D), but this supports growth in a sector with strong tailwinds.
Recommendation: This correction creates a favorable opportunity to add 15–20% to positions for growth portfolios. Target a 12-month price of A$25 (47% upside), assuming SEC resolution and pipeline execution. Monitor the August 21 earnings for confirmation.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns