
Pilbara Minerals (PLS) stands out as a high-conviction opportunity for those seeking exposure to a recovering lithium sector, with a clear recommendation to switch from Liontown Resources (LTR) into PLS at current levels.
Why Switch to Pilbara Minerals?
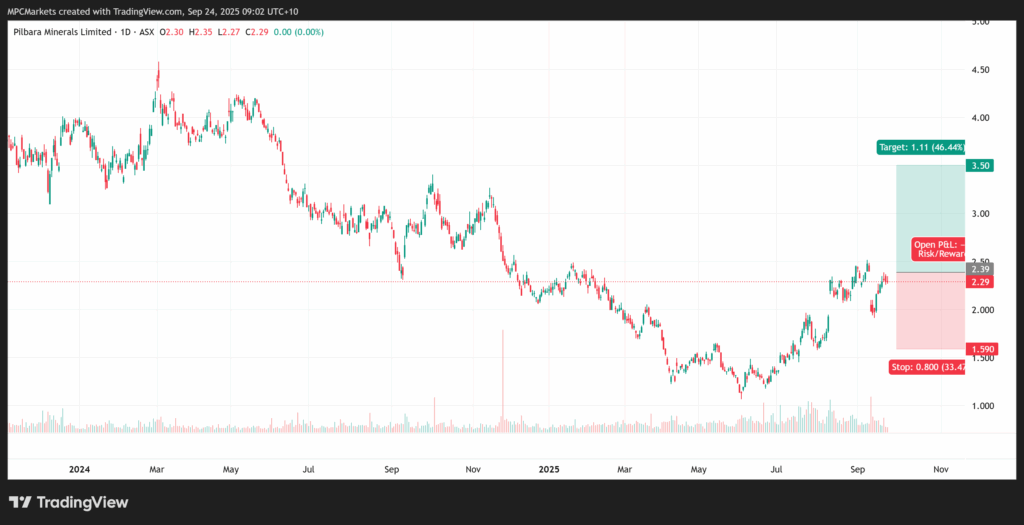
MPC Markets recommends entering PLS at $2.40, targeting $3.50, and using a $1.60 stop loss.
The recommendation is based on technical and fundamental analysis emphasizing Pilbara’s stability, operational resilience, and strong asset base that uniquely position it to benefit from increasing electric vehicle demand amid sector volatility.
PLS operates Australia’s largest hard-rock lithium mine and has proven profitability, generating over $100 million in quarterly operational cash flows, backed by more than $1 billion in cash reserves.
What Makes PLS a Superior Pick?
Cost Leadership: PLS maintains exceptionally low production costs at around $578 per tonne, significantly below industry averages, offering greater margin protection during downturns.
Financial Strength: Unlike emerging players such as Liontown, which are spending heavily to ramp up operations, PLS’s balance sheet strength provides stability and allows it to weather market cycles with minimal funding risks.
Market Position: PLS controls about 50% share of Australian spodumene concentrate supply, with diversified and long-term offtake agreements with leading global battery manufacturers—giving it competitive leverage in a consolidating market.
Technical Momentum: The case is reinforced by the stock recently breaking above its 200-day moving average, signaling clear bullish momentum.
Outlook and Risk/Reward
Lithium spot prices have rebounded approximately 20% from mid-year lows, driven by Chinese production cuts and anticipated restocking for batteries.
PLS’s phased expansions could boost annual output by 20% by 2025, further enhancing growth prospects.
Even in the case of prolonged price softness, PLS’s cost leadership and liquidity offer strong downside protection, with the set stop loss providing risk management.
Overall, PLS is seen as undervalued and well-positioned for reliable returns, offering safer exposure to sector upside compared to speculative, high-cash-burn emerging peers like Liontown.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.