Date: 29/11/2024
*** GENERAL ADVICE ONLY***
Findi Limited (ASX: FND) has reported a solid 1H25 performance, demonstrating positive operational and strategic momentum.
Financial Performance
- Revenue: $33.9 million (up from $31.8 million in 1H24)
- EBITDA: $12.9 million (up from $12.6 million in 1H24)
- Statutory net loss: $3.9 million
- Adjusted profit: $860k (after adding back $1.6 million in growth initiatives and $3.16 million in Convertible Debenture costs)Key Highlights
- On track to meet FY25 guidance
- Secured new merchant deal with Central Bank of India
- FindiPay expansion: acquiring 3,000 merchants per month
- Strategic investments in growth initiatives: $1.6 million
Operational Updates
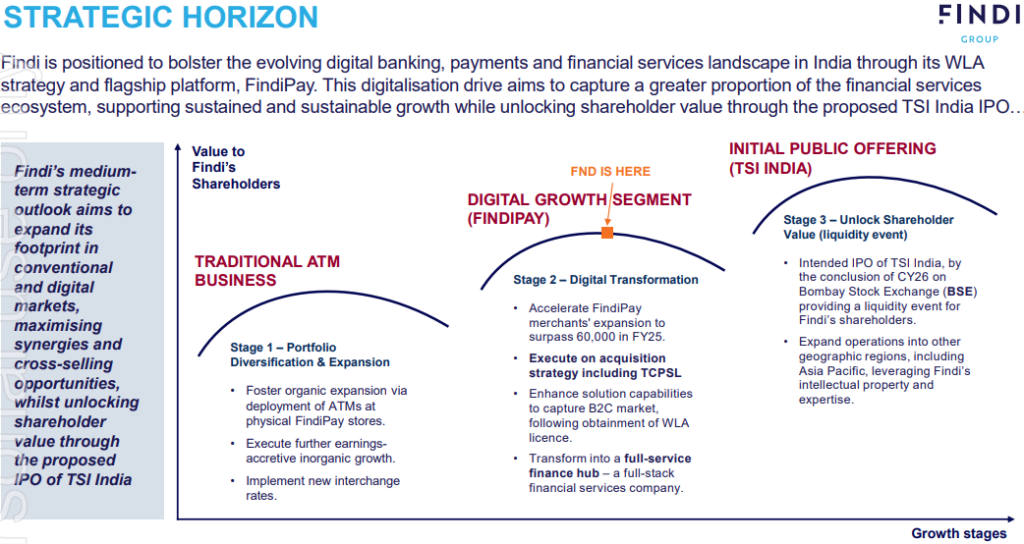
- State Bank of India (SBI) contract rollout commencing in December 2024
- White Label ATMs (WLA) deployment expected in early 2025
- Acquired Tata Communications Payment Solutions Ltd (TCPSL) for $75.7 million, adding 4,600 Indicash ATMs
Outlook
- FY25 Guidance reaffirmed:
- Revenue: $80-90 million
- EBITDA: $30-35 million
- TCPSL acquisition expected to contribute in FY26:
- Revenue: $28-30 million
- EBITDA: $5-7 million
- NPAT: $2-4 million
Findi shows promising growth potential with its strategic acquisitions and expansion plans. The company’s focus on diversifying its services and increasing its footprint in India positions it well for future growth. However, investors should monitor the integration of TCPSL and the execution of the SBI contract rollout, as these will be crucial for meeting FY25 guidance.
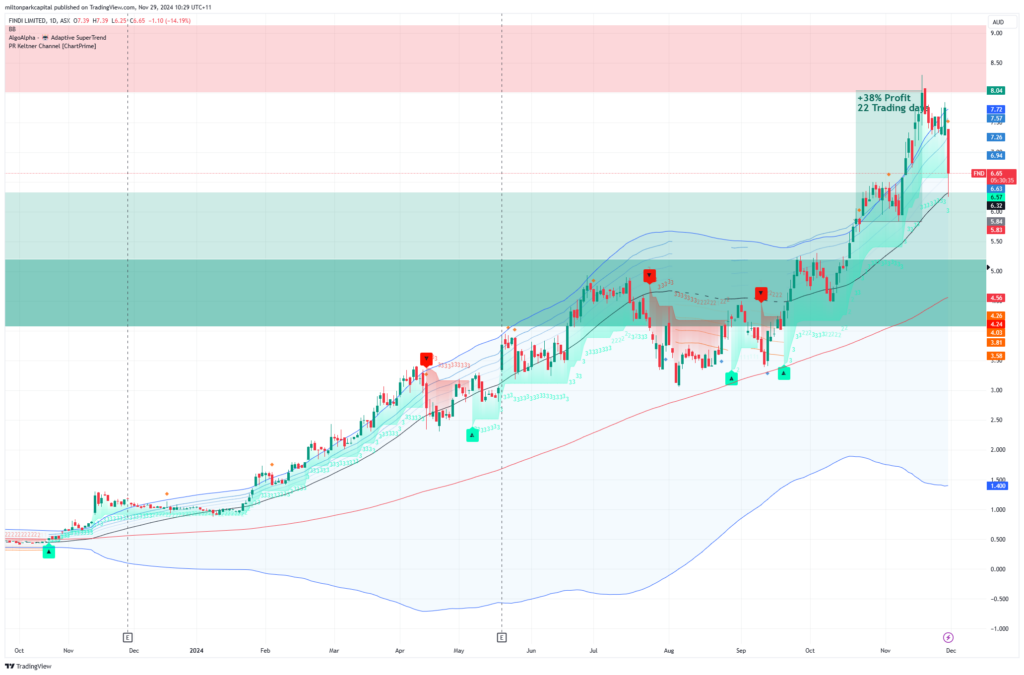
Approaching BUY ZONE
After Trimming Findi on the Approaching the 19th of November, we are approaching the BUY ZONE around $6.50
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.