Date: 24/12/2024
*** GENERAL ADVICE ONLY***
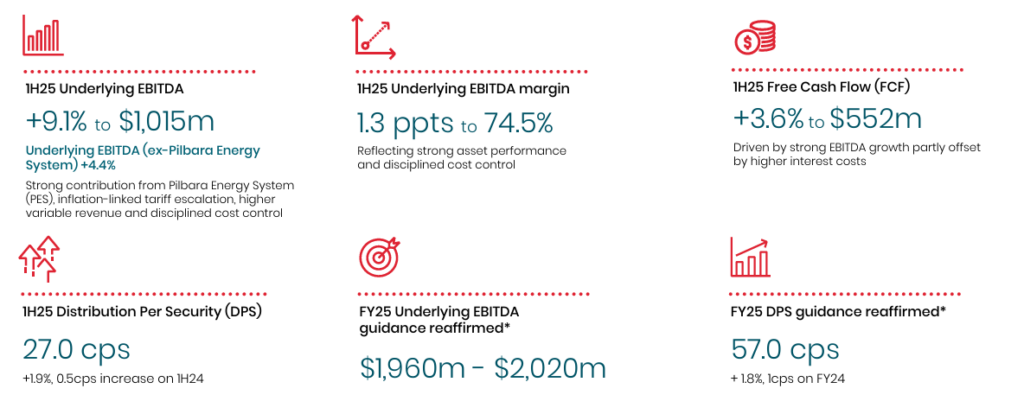
APA Group reported an increase in underlying EBITDA of 9.1% to $1,015 million compared to 1H24. This improvement was driven by strong new asset performance, notably from the Pilbara Energy System, alongside inflation-linked tariff escalations and disciplined cost control. Total statutory revenue (excluding pass-through) rose by 7.1% to $1,364 million. Free cash flow grew by 3.6% to $552 million, reflecting improved operating earnings and lower tax outlays despite increased interest interim distribution increased by 1.9% from 26.5 cents to 27.0 cents per security, underscoring the company’s commitment to returning value to shareholders.
Financial Performance Details
Earnings and EBITDA:
- Underlying EBITDA: Up 9.1% to $1,015 million, with a margin improvement of about 1.3 percentage points (from 73.2% to 74.5%).
- Reported EBITDA: Increased by 15.6% to $971 million.
- Statutory NPAT: Fell to $34 million (down from $1,049 million in 1H24) due to significant items in the previous period related to the Pilbara acquisition.
Cost Management:
- Corporate cost growth has been restrained to below inflation as a result of comprehensive cost-reduction initiatives.
- Increased depreciation and amortisation were partly attributable to the Pilbara Energy System acquisition.
Interest and Finance Costs:
Higher net interest expense—driven by increased net debt, foreign exchange losses on discontinued hedges, and contributions from hybrid securities—has put pressure on reported earnings, although core performance remains strong.
Investment and Growth Initiatives
Capital Investment:
Approximately $339 million has been deployed in growth projects, including:- Completion of the Port Hedland Solar and Battery project
- Construction of the Kurri Kurri lateral pipeline
- Early works on the East Coast Gas Grid expansion
Growth Pipeline:
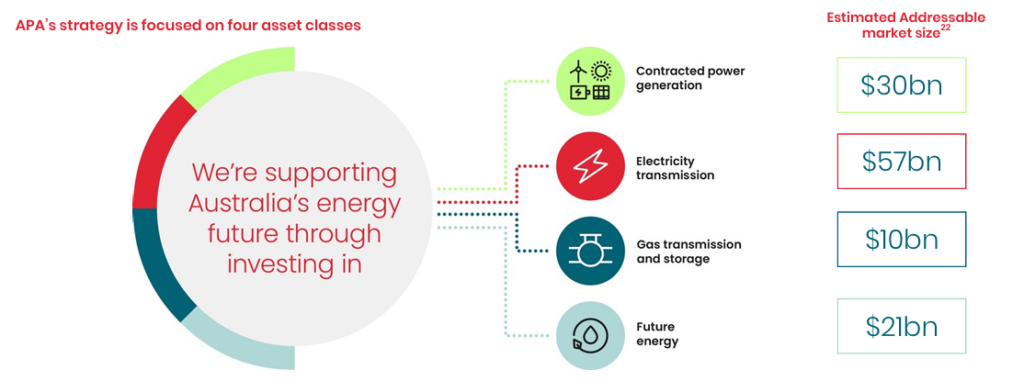
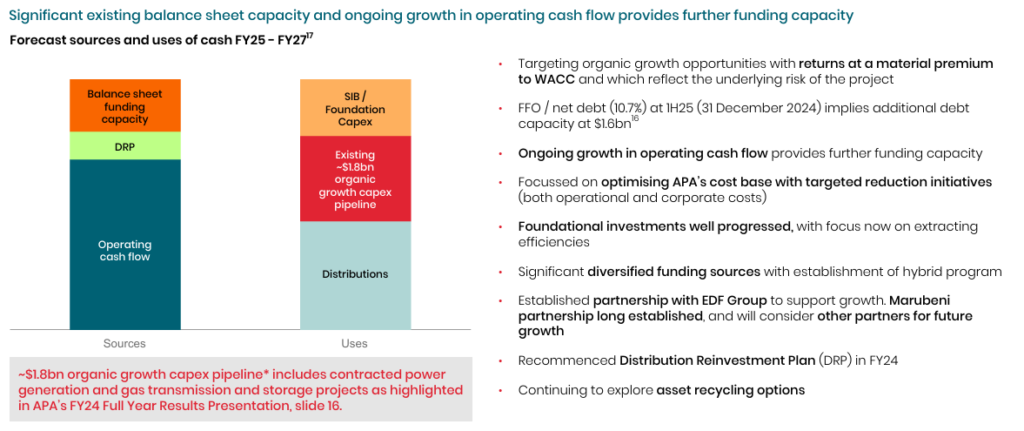
APA maintains a robust organic growth pipeline estimated at around $1.8 billion for FY25–FY27, supported by a strong balance sheet and ample funding capacity.Strategic Projects & Expansion Plans:
The company is advancing several strategic initiatives, including securing Priority Project status for key transmission corridors and executing a five-year East Coast Gas Grid Expansion Plan to increase north-to-south transport capacity. These projects are expected to drive long-term earnings growth and reinforce APA’s role in Australia’s energy infrastructure.
Outlook and Guidance
FY25 Guidance:
- Distribution: The FY25 distribution is reaffirmed at 57.0 cents per security, marking a continued commitment to shareholder returns.
- Underlying EBITDA: The guidance for FY25 remains in the range of $1,960 million to $2,020 million.
Balance Sheet & Funding:
The company reported an FFO/net debt ratio of 10.7% and has no drawn debt maturities until 2027. This strong balance sheet provides the flexibility to finance further growth and operational investments.CEO Commentary:
APA’s CEO emphasized the successful integration of the Pilbara Energy assets and highlighted the company’s ongoing focus on operational excellence, cost optimization, and a disciplined approach to funding its growth pipeline internally.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.