Earnings IPD Group (IPG)
IPD Group reported record half‐year results for the period ended 31 December 2024 (1H FY25). The Group, which recently expanded its capabilities through acquisitions (EX Engineering on 21 July 2023 and CMI Operations on 31 January 2024), posted significant revenue and earnings improvements despite some pressure on margins from complex orders and a challenging commercial construction environment.
Financial Highlights
Revenue Growth:
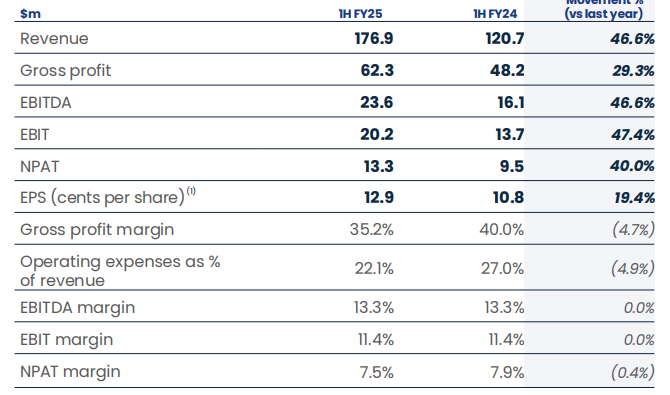
- Statutory revenue reached $176.9 million, a 46.6% increase compared to the previous corresponding period (pcp).
- On a pro-forma basis—accounting for the acquisitions—revenue grew modestly by 2.3%, reflecting a transition from daily trade orders to larger, more complex orders.
Profitability Metrics:
- EBITDA rose to $23.6 million (up 46.6% pcp), while EBIT increased to $20.2 million (up 47.4% pcp).
- Net Profit After Tax (NPAT) improved by 40.0% to $13.3 million, delivering an earnings per share (EPS) of 12.9 cents—a 19.4% increase from 10.8 cents in the prior period.
Margins:
- Gross profit margins were slightly impacted, declining from around 40.0% pcp to 35.2% due to the increased complexity and longer lead times of new orders.
- Operating expense as a percentage of revenue improved slightly on a pro-forma basis, which helped maintain stable EBITDA and EBIT margins.
Segment Performance
IPD Group’s operations are broadly divided into two key segments:
Products Division:
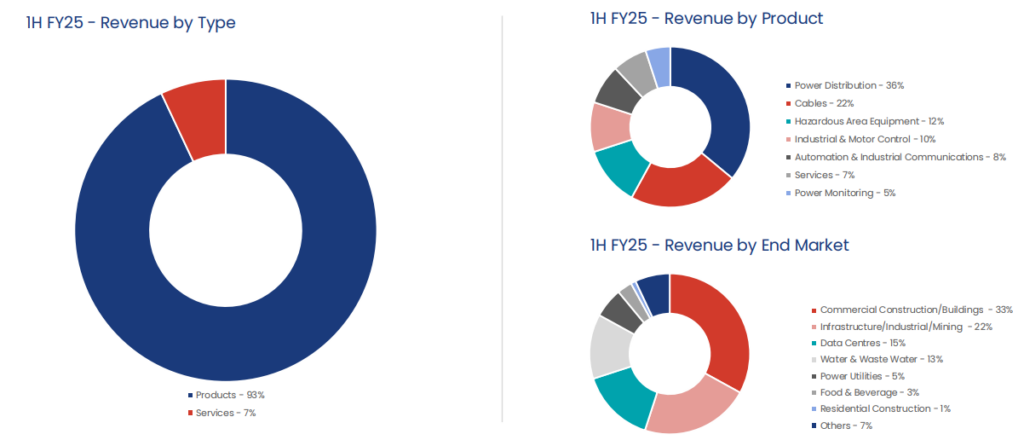
- Focuses on the distribution of electrical infrastructure products including power distribution, industrial and motor control, automation, power monitoring, hazardous area equipment, and electrical cables.
- This division has benefited from growth in niche sectors such as data centres and water & wastewater, posting a 5.2% revenue increase on a pro-forma basis despite overall market challenges.
Services Division:
- Provides installation, commissioning, calibration, testing, maintenance, repairs, and refurbishment services.
- While the core IPD business showed robust growth, the cable business under the CMI Operations banner—primarily serving the commercial construction sector—saw a decline of 3.3% on a pro-forma basis due to broader macroeconomic pressures.
Dividend and Shareholder Return
- Dividend Announcements:
- The Group paid a final dividend of 6.2 cents per share at the end of FY24.
- For 1H FY25, a fully franked interim dividend of 6.4 cents per share was declared, corresponding to a total payout of approximately $6.6 million and a payout ratio of 50%. This highlights management’s commitment to returning value to shareholders while maintaining strong reinvestment for growth.
Strategic Outlook and Future Growth Initiatives
Market Positioning:
- IPD’s diverse product range and integrated service offering have allowed it to capitalize on emerging opportunities in renewable energy, data centres, and public infrastructure electrification.
- The opening of a new Brisbane office supports the expansion of Queensland operations and positions the Group for further regional growth.
Growth Strategy:
- Continued focus on strategic acquisitions is expected to drive long-term earnings and operational synergies.
- Investments in operational efficiencies and digital transformation are planned to bolster the Group’s competitive position, despite challenging market conditions in certain sectors such as commercial construction.
Outlook:
- While some end markets remain challenging, management remains confident in sustaining growth through its robust order book, diversified revenue streams, and strategic initiatives aimed at long-term value creation.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns