Date: 13/03/2025
*** GENERAL AVICE ONLY***
Helia Delivers Sustainable Double-Digit Dividend Yield Amid Challenging Market Conditions
Helia (ASX: HLI), formerly known as Genworth Mortgage Insurance, has once again demonstrated its ability to sustain a double-digit dividend yield, a rare feat in the current market environment. Despite a decline in insurance revenue and underlying net profit after tax, Helia’s strong capital position has enabled it to maintain robust shareholder returns.
2024 Full-Year Results Highlights
- Revenue and Profit: Insurance revenue decreased by 9% to $389.2 million, exceeding Goldman Sachs estimates by 3.8%. Underlying net profit after tax fell by 11% to $220.9 million, beating estimates by 4.6%.
- Dividend Payments: The company declared a final ordinary dividend of 16 cents per share, surpassing estimates by 6.6%. Additionally, a special dividend of 53 cents per share was announced, significantly exceeding expectations by 112%.
- On-Market Buyback: Helia increased its on-market buyback program to $200 million, doubling the initial allocation of $100 million.
- Return on Equity: The underlying return on equity decreased by 120 basis points to 19.9%.
Capital Position and Dividend Sustainability
Helia’s ability to maintain high dividend payouts is largely attributed to its strong capital position. The company’s prescribed capital amount (PCA) coverage ratio, which measures available capital against regulatory requirements, stood at 2.23x as of the third quarter of 2024. This translates to approximately $460 million in surplus capital, providing ample room for shareholder returns. Even after the distribution of dividends and completion of the buyback program, the PCA ratio is expected to remain robust at around 2.10x.
Earnings Outlook and Market Risks
Macquarie analysts forecast a decline in Helia’s earnings over the next two years, with underlying net profit after tax expected to decrease from $208.2 million in FY24 to $87.2 million in FY26. However, the company’s strong capital base supports its ability to sustain market-leading dividends. A key risk factor is the potential loss of the Commonwealth Bank’s LMI contract, which expires on December 31, 2025. This contract accounted for approximately 53% of Helia’s gross written premiums in FY23.
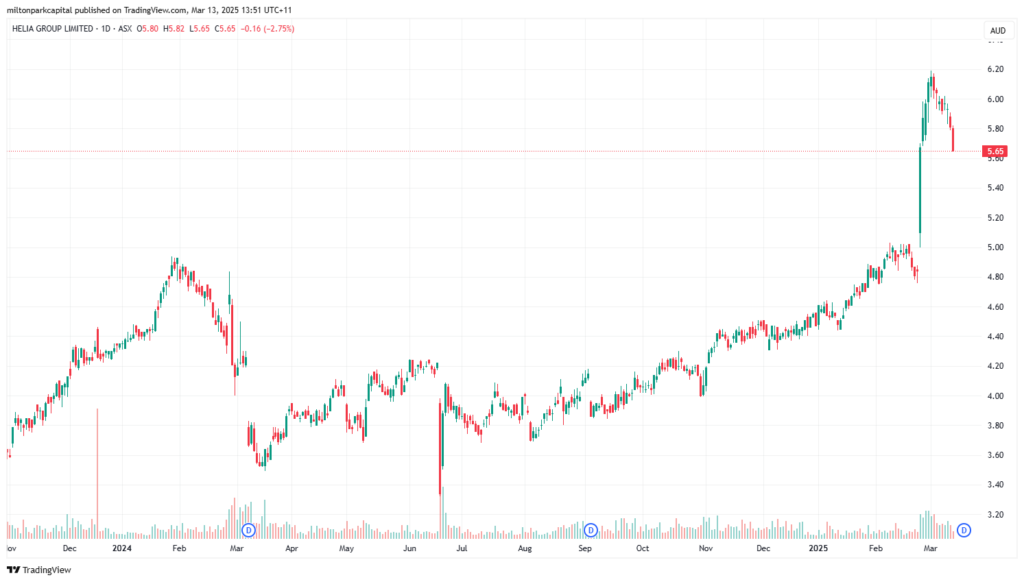
Helia’s stock is currently trading around $5.70, implying a dividend yield of approximately 12.1% (for 6 months). The company’s shares will trade ex-dividend for both the final and special dividends on March 19th, with payment scheduled for April 3rd. Despite the challenges ahead, Helia’s robust capital position and dividend strategy continue to attract investor interest.
Trade Rationale
HLI is going to pay a great fully franked dividend next week. So this trade is more for investors who are looking for yield and franking credits. That being said HLI is very cheap, its been managed very well and in a sector that has some great fundamental tailwinds. Market got excited by this dividend and sent HLI all the way up to $6.15, its now fallen back under $5.70, which is much better entry. So buy HLI by the 18th March at the latest to get the dividend
Trade Strategy:
Buy HLI up to $5.70 and before close of business on 18th March 2025
Total Dividend is 69c
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.