******* General Advice Only *******
16th September 2025
Upside Catalysts
Our investment thesis is based on a powerful macro catalyst: a structural, multi-year increase in uranium demand driven by the insatiable power requirements of AI datacenters. Recent US policy shifts, including a $2.7 billion domestic uranium procurement plan and a pivotal US-UK nuclear pact, are accelerating this trend, creating a highly favourable outlook for the entire uranium sector.
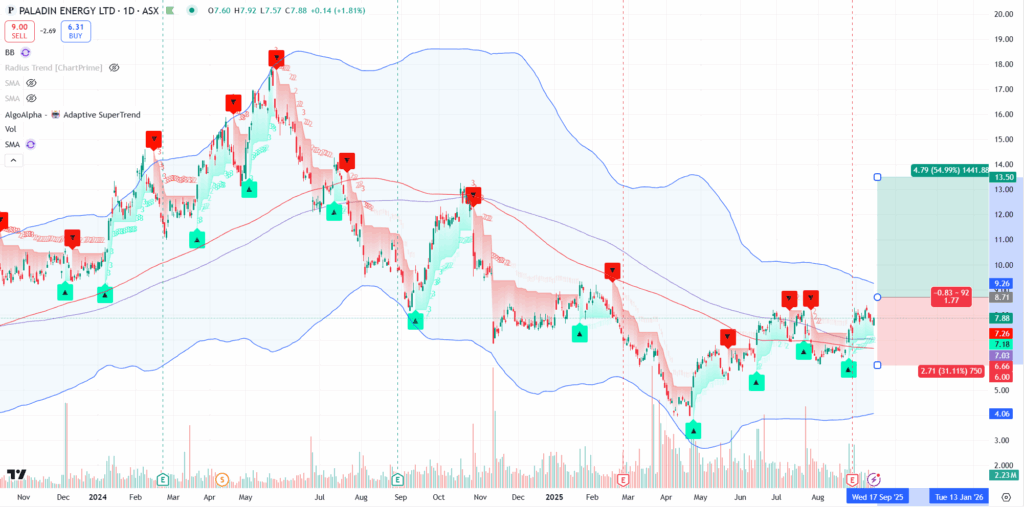
PDN is a well-positioned pure-play to capitalise on this cycle. As one of the ASX’s larger uranium producers with quality assets and a stable operational history, it offers direct leverage to rising spot prices. Our analysis indicates the stock is currently undervalued relative to the underlying commodity, presenting a compelling entry point compared to its re-rated North American peers.
We believe this valuation gap will close as the market fully appreciates the sector’s strengthened fundamentals. The company offers an attractive opportunity to gain exposure to a sustained uranium bull market, driven by geopolitical tailwinds and a definitive policy pivot towards nuclear power as the foundation for reliable, base-load energy.
Rationale
Our analysis at MPC Markets identifies a powerful macro-geopolitical tailwind for uranium, driven by the urgent energy demands of AI datacentres. The recent US policy shift, committing $2.7 billion to domestic uranium enrichment and forging a new US-UK nuclear pact for up to 12 SMRs, directly addresses a projected 165 percent surge in global datacentre power demand by 2030. This structural shift away from Russian supply and towards nuclear baseload power creates a sustained, multi-year demand cycle for uranium, underpinning our bullish sector view.
Within this favourable landscape, Paladin Energy represents a compelling investment case. As a proven producer with the Langer Heinrich mine now ramping up, PDN offers direct exposure to the rising uranium spot price. Crucially, our modelling indicates the company is trading at a significant discount to the net asset value of its reserves compared to its North American-listed peers, which have already re-rated sharply on the US news. This valuation gap presents a clear opportunity on the ASX.
PDN’s competitive position is strengthened by its tier-one asset base in stable jurisdictions, Namibia and Canada. This provides a distinct operational advantage over many junior explorers. The company’s return to production demonstrates execution capability, and its cost structure is positioned to generate substantial operational leverage as production scales into a rising price environment. This leverage is a key differentiator from pure-play exploration companies.
The primary catalyst is the immediate market repricing of ASX uranium equities to catch up with their North American counterparts following the transformative US policy announcement. This provides a near-term revaluation trigger. Longer-term, PDN is poised to benefit from increased offtake agreement interest and rising spot prices, directly translating into strong cash flow generation. Key risks include execution ramp-up and uranium price volatility, though these are mitigated by the company’s production status and the strengthening long-term fundamental outlook.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.