Balanced Portfolio & Growth Recommendation
Date: 13/11/2024
*** GENERAL ADVICE ONLY***
Johns Lyng Group’s (JLG:ASX) Annual General Meeting presents a positive outlook for the company:
Financial Performance:
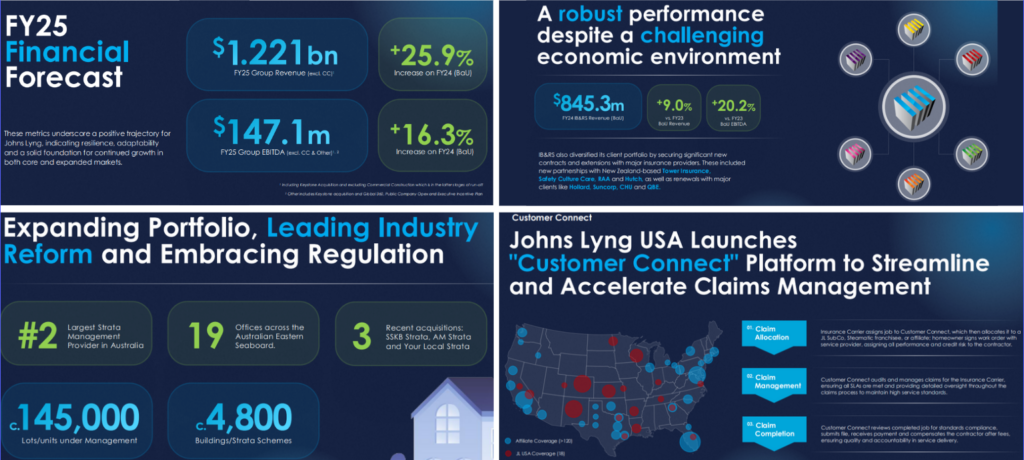
- FY24 Group Revenue reached $1.159 billion
- FY25 Group Revenue forecast at $1.221 billion, indicating a 16.3% increase from FY24
- FY25 Group EBITDA projected at $147.1 million, a 25.9% increase from FY24
Key Strengths:
- Diversified Growth: Strong performance across multiple segments, including Insurance Building and Restoration Services (IB&RS), Strata Services, and Essential Home Services
- Strategic Expansion: Successful integration of acquisitions and launch of new services, particularly in the US market
- Customer Connect Platform: New technology implementation to streamline claims management, potentially improving operational efficiency
- Robust IB&RS Performance: 9.0% BaU revenue increase and 20.2% EBITDA growth, supported by geographic expansion and new contracts
- Keystone Acquisition: Expected to contribute over $100 million in revenue and $9 million in EBITDA for FY25, immediately earnings accretive
- Strata Services Growth: Now the second-largest strata management provider in Australia
- Government Partnerships: Strengthened relationships for disaster recovery services
Tone: The tone of the AGM presentation is optimistic and confident, highlighting strategic growth initiatives and strong financial forecasts. The company appears well-positioned for continued growth, with a focus on expanding its service offerings and geographical presence.
Risks: Potential risks to consider include the cyclical nature of catastrophe-related revenues and integration challenges from recent acquisitions. Overall, Johns Lyng Group presents an attractive investment proposition with its diversified business model and strong growth trajectory.
Based on the Annual General Meeting (AGM) presentation and the broker expectations, we can draw the following comparisons:
Financial Performance and Outlook
AGM Guidance:
- FY25 Group Revenue forecast: $1.221 billion (16.3% increase from FY24)
- FY25 Group EBITDA projection: $147.1 million (25.9% increase from FY24)
Broker Expectations:
- Macquarie: Maintains Outperform rating with a $4.90 target price
- Bell Potter: Hold rating with a $4.40 target price
- Morgan Stanley: Overweight rating with a $4.40 target price
The AGM guidance appears to be in line with or slightly exceeding broker expectations, given the positive ratings and maintained or increased target prices.
Key Points of Interest
- US Performance:
- AGM: Highlights strategic expansion in the US market, including new services and partnerships
- Macquarie: Forecasts around 12% US revenue growth, noting minimal potential upside from hurricane CAT impacts
- Acquisitions:
- AGM: Emphasizes the Keystone acquisition, expecting over $100 million in revenue and $9 million in EBITDA for FY25
- Morgan Stanley: Specifically notes this acquisition in their commentary, aligning with the company’s guidance
- Business-as-Usual (BaU) Performance:
- AGM: Reports 9.0% BaU revenue increase and 20.2% EBITDA growth in IB&RS
- Bell Potter: Highlights potential risks in domestic BaU margins, projecting a bottom in FY26
- Dividend Forecasts:
- Brokers generally forecast dividends between 7.90 to 10.00 cents per share for FY25 and FY26
Tone and Outlook
The AGM presentation conveys a positive and confident tone, emphasizing strategic growth initiatives, diversification, and strong financial forecasts.
This optimistic outlook appears to be largely in line with broker expectations, particularly with Macquarie and Morgan Stanley maintaining positive ratings.
However, Bell Potter’s more cautious stance, highlighting potential risks in domestic business-as-usual margins, provides a counterpoint to consider against the company’s optimistic projections.
Overall, the AGM presentation seems to meet or slightly exceed broker expectations, with a focus on growth strategies and positive financial forecasts that align with the more bullish analyst views.
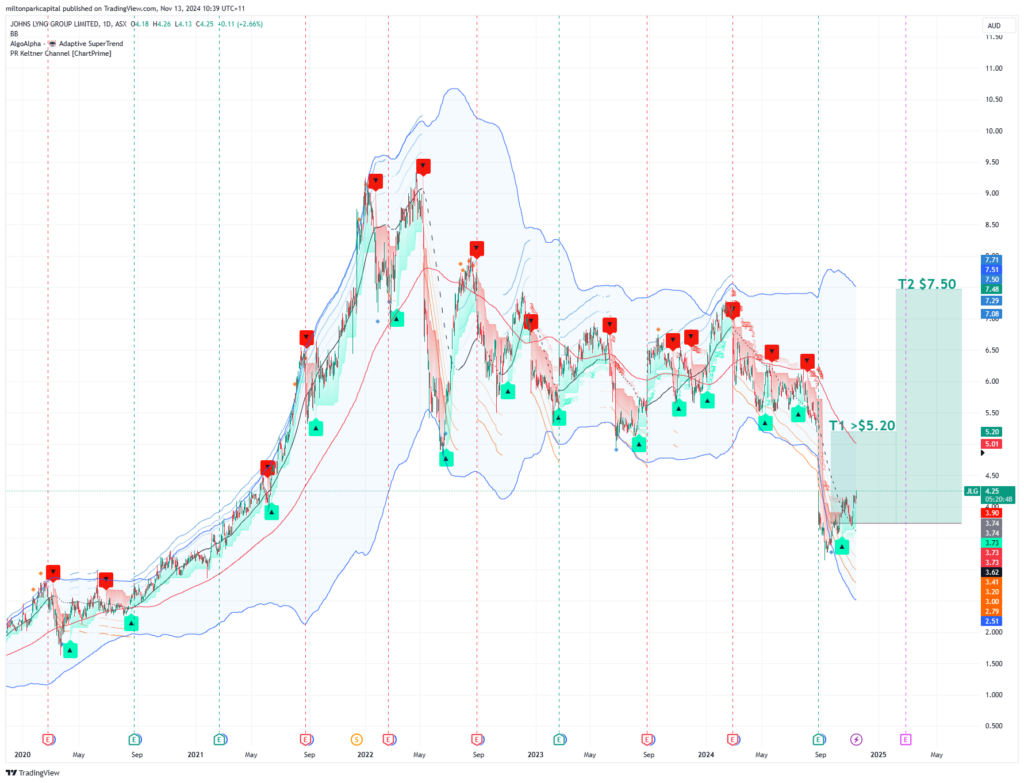
Johns Lyng Group JLG:ASX – Trade Plan
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.