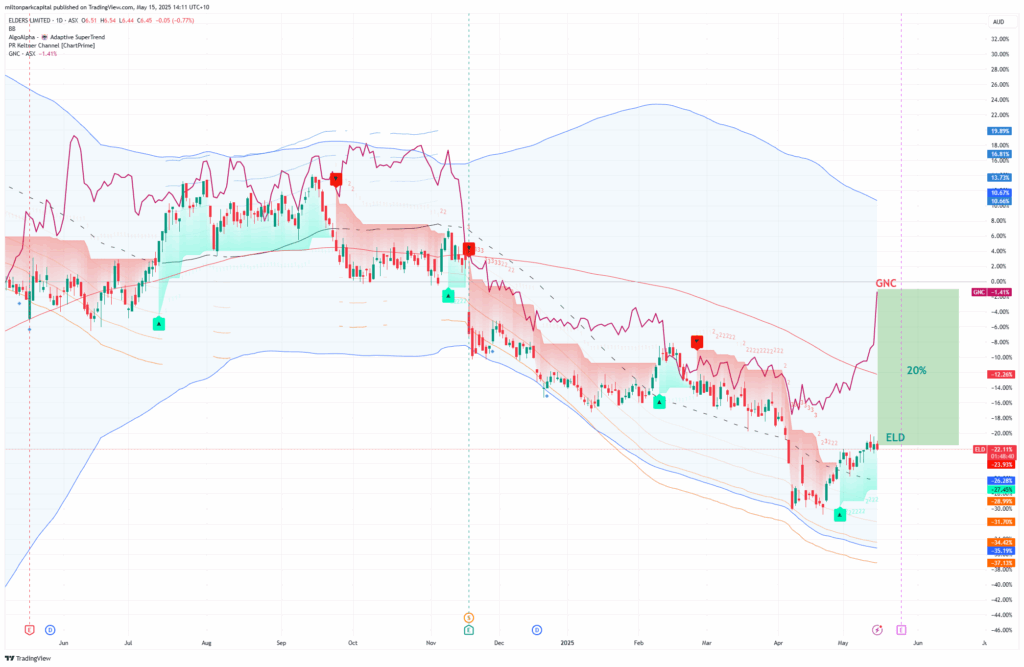
As per our recommendation on 15th of May, we initiated a short-term switch from GNC to Elders due to positivity from GrainCorp CEO and Agri-Bank, Rabo Bank about agricultural conditions.
”Short term: BUY Elders <$6.60, looking for a positive earnings catalyst on the 26th of May. We are not looking to hold Elders long-term, so we would look to take profit or sell on a stop-loss on the day of earnings”
Elders HY25 Earnings Summary
Summary of HY25 Performance vs Expectations
| Metric | HY25 Result | Consensus / Forecast | Outcome |
|---|---|---|---|
| Underlying EBIT | $64.3m | $75m (Citi), $73m (Consensus) | Miss |
| Underlying EPS | 21.4 cents | 23.0c (TradingView) | Miss |
| Underlying NPAT | $38.2m | Not specified | Beat YoY, but not standout |
| Operating Cash Flow | $31.2m | Prior year $48.7m | Weaker |
| Return on Capital | 12.7% | 15% Target | Below target |
| Interim Dividend | 18.0c (50% franked) | 18.0c | In line |
Key Points:
Earnings Miss: Underlying EBIT came in at $64.3m vs. Citi’s $75m forecast – a meaningful miss of ~14%, highlighting that recovery is slower than anticipated.
EPS Miss: HY EPS of 21.4c vs. expected 23c. With full-year guidance ranging from 58–66 cents from brokers, a strong 2H is now essential, which hinges on a seasonal turnaround and post-emergent AgChem demand.
Retail Weakness: Gross margin in Retail Products fell 6%, led by crop protection – confirming prior fears about dry conditions in SA/VIC and competitive pricing pressures.
Cash Flow and Return Deterioration: Operating cash flow dropped -36% YoY and cash conversion of 82% remains below the company’s 90% target, reflecting higher working capital tied to livestock.
Transformation Drag: Return on capital (12.7%) is below the 15% target, weighed by ongoing investments and the delayed payoff from acquisitions and modernisation projects.
Dividend Flat, Yield Under Pressure: Interim dividend was maintained at 18c, 50% franked – but without clear EPS growth, future dividend upgrades are unlikely.
Upon further research, we have identified Treasury Wine Estates as deep value in the Consumer Staples sector, with little tariff effect and high Growth at a Reasonable Yield (GARY)
BUY Treasury Wine Estates TWE:ASX
Summary Recommendation:
We recommend a Buy on Treasury Wine Estates (TWE:ASX), with a 12-month price target range of A$11.54–A$14.00, implying 38–67% upside from the current price of A$8.37. This view is underpinned by strong analyst consensus, accelerating China demand, ongoing premiumization, and robust financial health, despite near-term headwinds in the US and a recent leadership transition.
Trade Plan:
Sell ELD > $6.6
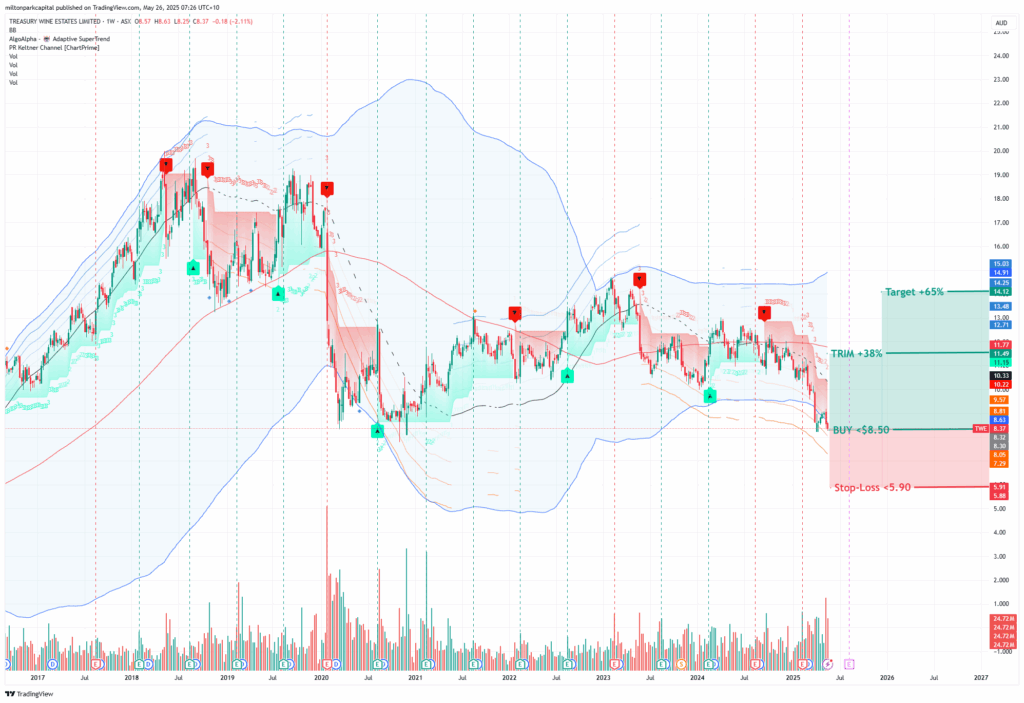
To Buy TWE <$8.40
Trim price: $11.50 (+38%)
Target Price: >$14.00 (+65%)
Treasury Wine Estates TWE:ASX
Investment Thesis
- China Reopening & Premiumization Drive Growth
- The removal of Chinese tariffs in March 2024 has reignited TWE’s key growth engine. Australian wine exports to China surged from $200 million to $1.03 billion in a year, with Penfolds—a flagship TWE brand—leading the premiumization trend.
- Penfolds’ luxury positioning is further validated by its supply-constrained status in China, supporting pricing power and margin expansion.
- Diversified Global Footprint and Resilience
- TWE demonstrated resilience during the China tariff period by reallocating volumes to the US and other Asian markets, cementing its global reach.
- The DAOU Vineyards acquisition in the US is delivering above-expectation synergies, with DAOU now the top luxury Cabernet in the US market.
- Ongoing investments in luxury assets and the acquisition of Ningxia Stone & Moon Winery in China reinforce TWE’s commitment to global premium wine leadership.
- Strong Earnings Recovery and Attractive Valuation
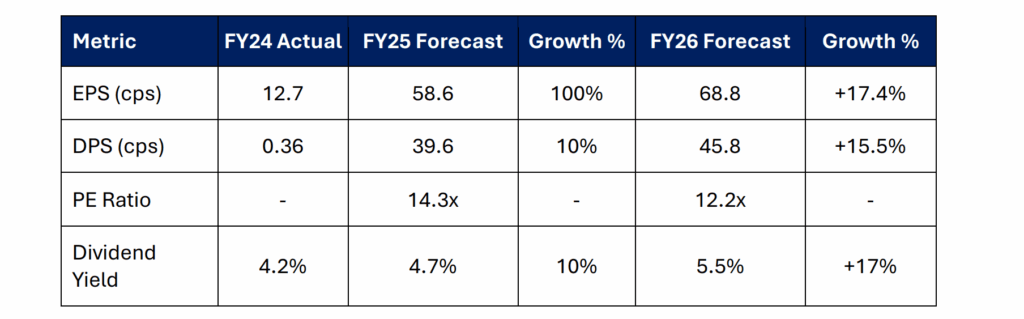
- Consensus forecasts call for a sharp EPS rebound in FY25 (to 58.6 cps, +100% y/y), with double-digit growth through FY27.
- The stock trades at 14.3x FY25 earnings and yields 4.7%, attractive for a global luxury brand portfolio with strong asset backing and cash generation.
- Financial health is robust, with an Altman Z-Score of 6.8 (well above distress thresholds) and cash conversion at 90%.
- Positive Analyst and Technical Sentiment
- Analyst sentiment is overwhelmingly positive: 11 Buy, 3 Hold, 0 Sell.
- Price targets cluster around A$12.30–A$12.91, with UBS and Morgan Stanley at A$14.00 and A$12.90, respectively, and Morgans at A$13.43.
- The stock trades near its 52-week low, offering an attractive entry point as sentiment is expected to improve with China sales ramping up.
Recent Developments
- Leadership Transition: Sam Fischer, with deep luxury and beverage experience (ex-Lion, Diageo, Burberry), will become CEO in October 2025. While some brokers cite near-term uncertainty, his track record in premium brands is a long-term positive.
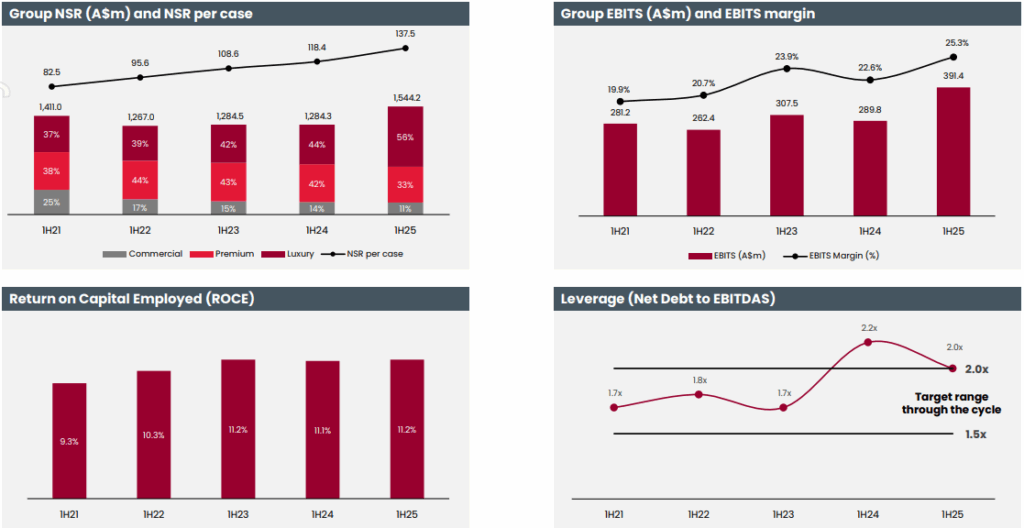
- 1H25 Results: Luxury-led growth drove EBITS up 35% to $391m, with luxury now 56% of group sales. Net operating cash flow rose 56%.
- Dividend: Interim dividend up 18% to 20c/share (70% franked), reflecting strong cash generation.
- US Tariffs: Minimal impact expected, as most US earnings are from locally produced wines.
Risks
- Execution risk in recapturing Chinese market share and balancing growth across regions.
- US market weakness and shifting alcohol consumption patterns may weigh on the Americas division.
- Currency and geopolitical risks remain, particularly regarding trade policy.
- Leadership transition may introduce short-term uncertainty, especially regarding the Penfolds strategy.
TWE is a global wine leader at an inflection point: the China market is reopening, premiumization is accelerating, and the company is executing well on its luxury-led strategy. While US market softness and a CEO transition introduce some risk, the overwhelming analyst consensus, robust financials, and upside to fair value make TWE a compelling buy at current levels. We see 38–67% upside over the next 12 months, with a strong dividend yield and further potential as premiumization and China recovery continue
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns