Investment catalysts
Long-Term Financial Trends
Despite today’s pullback, Spotify’s financial transformation remains impressive:
- Profitability Surge: Net income margin reached 8.7% in Q4 2024, with full-year 2024 margin at 7.3%
- Revenue Growth: 15.6% year-over-year in Q4 2024, 18.3% for full year 2024
- Cash Generation: €2.28B in levered free cash flow for 2024
- Return on Equity: Strong 28.3% ROE for 2024
Market Sentiment & Valuation
The stock remains richly valued at 94.5x trailing P/E and 50.1x forward P/E, reflecting high growth expectations. Despite today’s drop, SPOT is still up 101.6% over the past year, significantly outperforming the broader market.
Analysts remain overwhelmingly bullish with a consensus “Strong Buy” rating (1.94872) and a mean price target of $666.48, suggesting 14.8% upside from current levels. However, some analysts have begun trimming price targets, with Evercore ISI lowering from $700 to $650 and Raymond James reducing from $650 to $635.
What’s Behind the Numbers?
The earnings miss and guidance appear related to:
- Higher payroll taxes impacting operating profit forecasts
- Slight slowdown in user growth momentum
- Challenges in ad-supported revenue
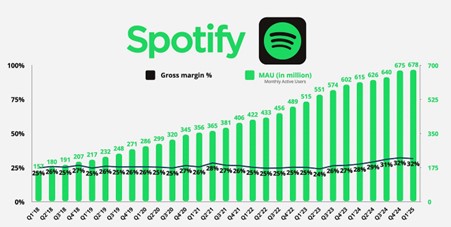
However, Spotify continues expanding its AI Playlist feature to over 40 new markets and maintains robust gross margins around 30.25%.
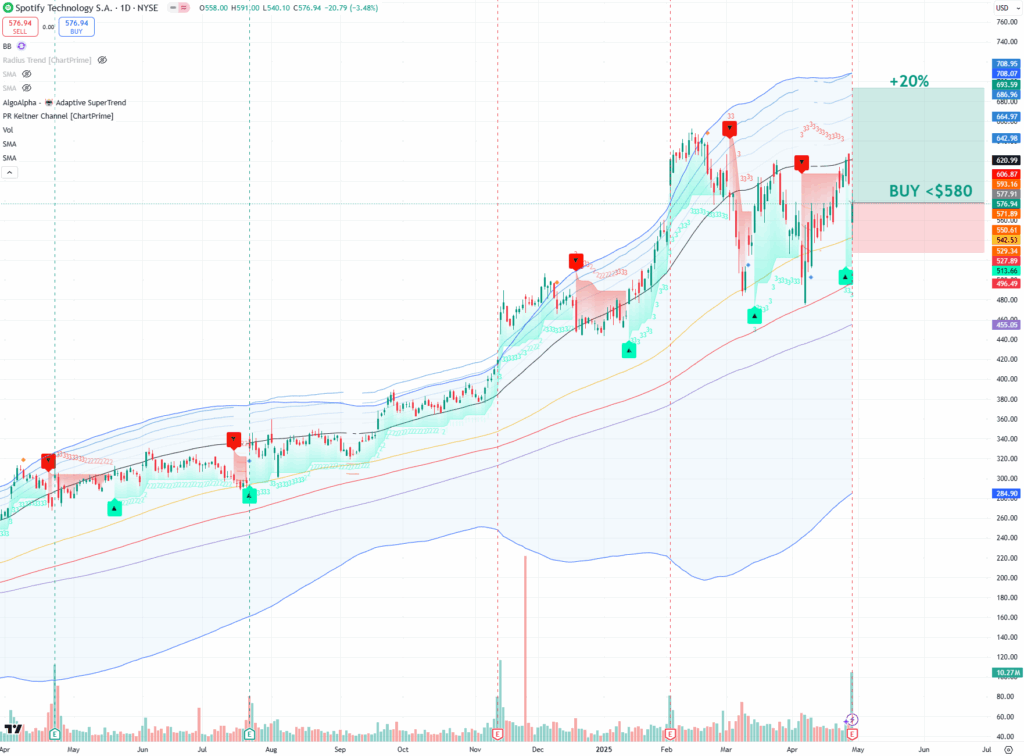
Trade Plan:
- Expected Timeframe: 1-month to 6-months
- Entry: Under $585
- Stop-loss: Under $525
- Trim Zone: (optional) $655 (+10%)
- Target: Above $700
Bottom Line
While today’s reaction seems negative, Spotify’s fundamental growth story remains intact. The company continues to grow subscribers at a healthy clip while maintaining strong margins. The question for investors is whether the current valuation already prices in this growth trajectory, leaving little room for execution missteps.
Most Recent Financials and recent Earnings
🎧 Price Hikes Pay Off
Spotify’s Q1 revenue grew 15% Y/Y to €4.2 billion (in-line), with EPS rising 10% Y/Y to €1.07, continuing its profitable momentum. Monthly active users grew 10% Y/Y to 678 million, and Premium subscribers rose 12% to 268 million (3 million beat). Price hikes boosted subscription ARPU by 4%, while ad-supported revenue grew 8% as Spotify expands into video podcasts and audiobooks. Gross margin improved to 31.6%, slightly above guidance, reflecting stronger podcast ads performance.
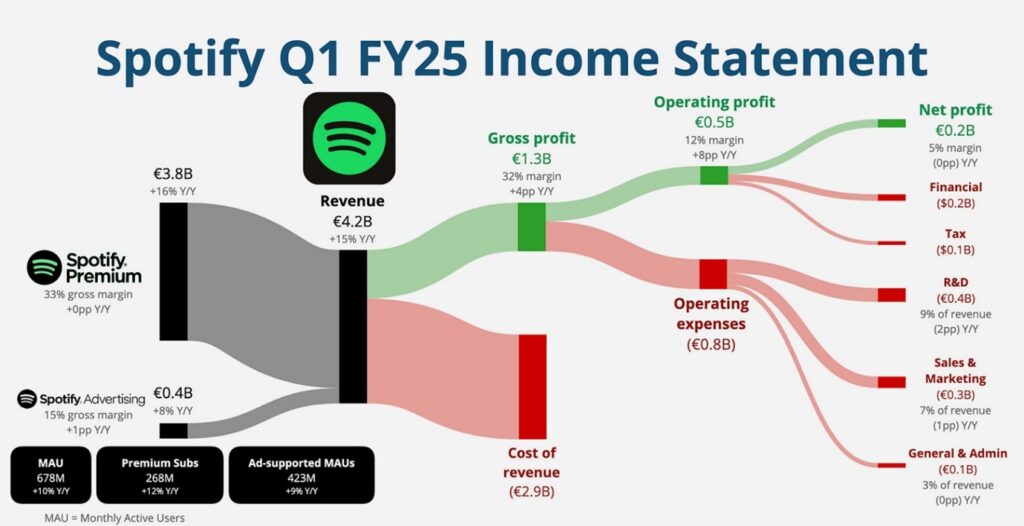
ooking ahead, Spotify guided to 689 million MAUs and 273 million premium subscribers for Q2, with revenue of €4.3 billion and a 31.5% gross margin. While some analysts flagged a softer MAU forecast, management remains bullish on long-term expansion, citing resilient consumer demand and deeper engagement from initiatives like video podcasts and a new creator revenue-sharing program. The roadmap includes further price increases, a premium “Music Pro” tier, and a bigger push into advertising, positioning Spotify for continued profitable growth.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.