***GENERAL ADVICE ONLY***
Financial Highlights
- Total revenue: $381.0m, up 17% year-over-year (YoY)
- CargoWise revenue: $331.7m, up 21% YoY
- EBITDA: $192.3m, up 28% YoY
- EBITDA margin: 50%, up 5 percentage points YoY
- Underlying NPAT: $112.1m, up 34% YoY
- Free cash flow: $124.1m, up 22% YoY
Key Takeaways
Strong Revenue Growth
WiseTech Global delivered robust revenue growth in 1H25, with total revenue increasing 17% YoY to $381.0m. The company’s core CargoWise platform continued to be the primary growth driver, with revenue up 21% YoY to $331.7m.
Expanding Profitability
EBITDA grew 28% YoY to $192.3m, outpacing revenue growth. The EBITDA margin expanded by 5 percentage points to 50%, demonstrating improved operational efficiency.
Customer Wins and Product Development
The company secured two new Top 25 global rollouts from Large Global Freight Forwarders (LGFFs) since July 2024: Nippon Express and LOGISTEED. WiseTech also launched new breakthrough products ComplianceWise and CargoWise Next.
Strategic Acquisitions
WiseTech continues to pursue strategic tuck-in acquisitions, adding BSM Global and signing ImpexDocs to expand its digital documentation capabilities.
Outlook
For FY25, WiseTech Global expects:
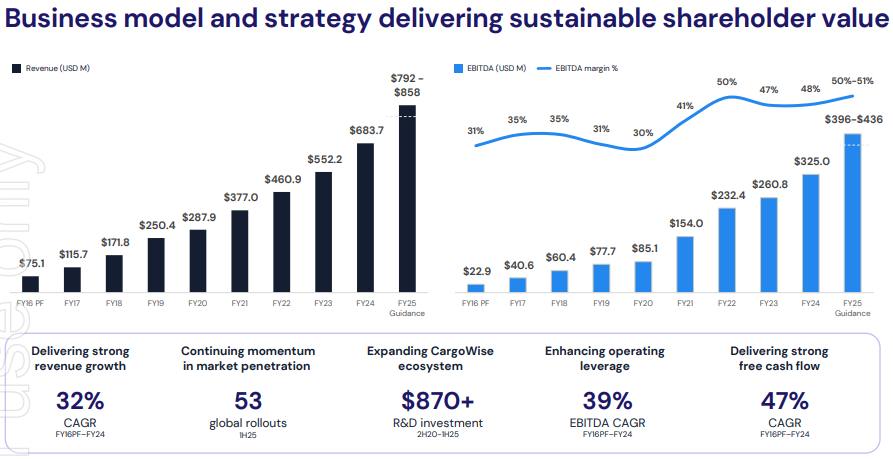
- Revenue: $792m – $858m (16% – 26% growth YoY)
- EBITDA: $396m – $436m (22% – 34% growth YoY)
- EBITDA margin: 50% – 51% (2-3 percentage points increase YoY)
The company now expects revenue to be at the bottom end of the guidance range due to delays in rolling out three announced Breakthrough Products. However, EBITDA margin is expected to be towards the top of the previously announced range, driven by stronger results from a company-wide efficiency program.
Analysis
WiseTech Global continues to demonstrate strong financial performance and strategic execution. The company’s focus on its CargoWise platform and ongoing product development is yielding results, as evidenced by the robust revenue growth and margin expansion.
The acquisition strategy appears to be paying off, with Envase and Blume (acquired in FY23) now delivering combined EBITDA margin >20% in 1H25, compared to being loss-making in 1H24.
While the delay in rolling out new breakthrough products may impact short-term revenue growth, the company’s ability to improve profitability through operational efficiencies is encouraging. The continued success in securing global rollouts from large freight forwarders provides a solid foundation for future growth.
WiseTech Global’s 1H25 results generally met or exceeded broker expectations, with some key points of comparison:
Revenue Performance
- Total revenue of $381.0m, up 17% year-over-year, was in line with expectations
- CargoWise revenue of $331.7m, up 21% YoY, slightly exceeded some analyst forecasts
- The company now expects FY25 revenue to be at the bottom end of the $792m – $858m guidance range, consistent with the recent downgrade noted by brokers
Profitability
- EBITDA of $192.3m, up 28% YoY, was at the high end of expectations
- EBITDA margin of 50%, up 5 percentage points YoY, exceeded most broker forecasts
- FY25 EBITDA margin guidance of 50% – 51% is now expected to be at the top end of the range, aligning with the upgraded margin outlook noted by analysts
Key Drivers and Challenges
- Two new Top 25 global freight forwarder wins (Nippon Express and LOGISTEED) support the growth narrative highlighted by brokers
- Delays in rolling out three breakthrough products (CargoWise Next, Container Transport Optimization, and ComplianceWise) confirm the product timing concerns raised by some analysts
- The company-wide efficiency program exceeded its target, delivering stronger cost savings than initially expected, supporting the improved margin outlook
Governance and Management
- The results presentation did not directly address the recent board resignations and governance concerns raised by several brokers
- No specific comments were made regarding Richard White’s role or the CEO appointment process
Outlook
- The updated FY25 guidance aligns with the recent downgrade noted by brokers, with revenue at the lower end but margins at the upper end of the previous range
- The company maintains a positive long-term outlook, consistent with most broker views, despite near-term challenges
Overall, WiseTech Global’s 1H25 results largely met or exceeded broker expectations, particularly in terms of profitability and margin expansion. However, the revenue outlook and product delays confirm some of the concerns raised by analysts. The lack of commentary on recent governance issues may leave some questions unanswered for investors.