Date: 13/1/2025
*** GENERAL ADVICE ONLY***
Telix Pharmaceuticals Limited (ASX: TLX, Nasdaq: TLX) has released its Q4 2024 and FY2024 financial update, along with key business developments. Here’s a summary:
Financial Performance
- Q4 2024 unaudited revenue: US$142 million (AU$218 million), up 46% year-over-year and 5% quarter-over-quarter
- FY2024 unaudited revenue: US$517 million (AU$783 million), exceeding guidance of US$490-510 million
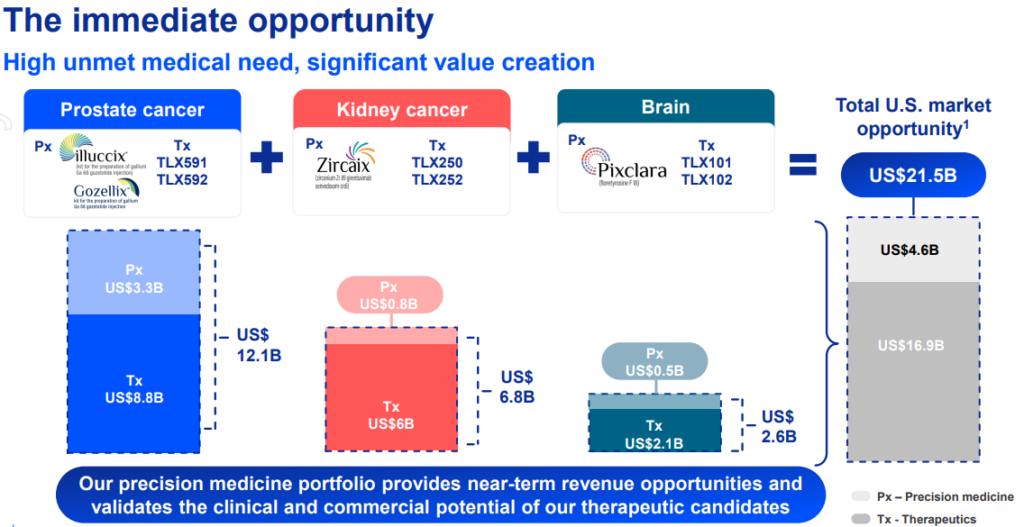
- Revenue primarily driven by sales of Illuccix®, a diagnostic radiopharmaceutical for prostate cancer PET imaging
Strategic Developments
- Nasdaq listing achieved on November 14, 2024, under the symbol ‘TLX’
- Acquisition of FAP-targeting assets, expanding the product pipeline
- Entered agreement to acquire ImaginAb Inc.’s platform technology and drug discovery capability
Pipeline Progress
- BLA submitted for TLX250-CDx (Zircaix®) for renal cancer imaging on December 27, 2024
- FDA granted Priority Review for TLX101-CDx (Pixclara®) with PDUFA date of April 26, 2025
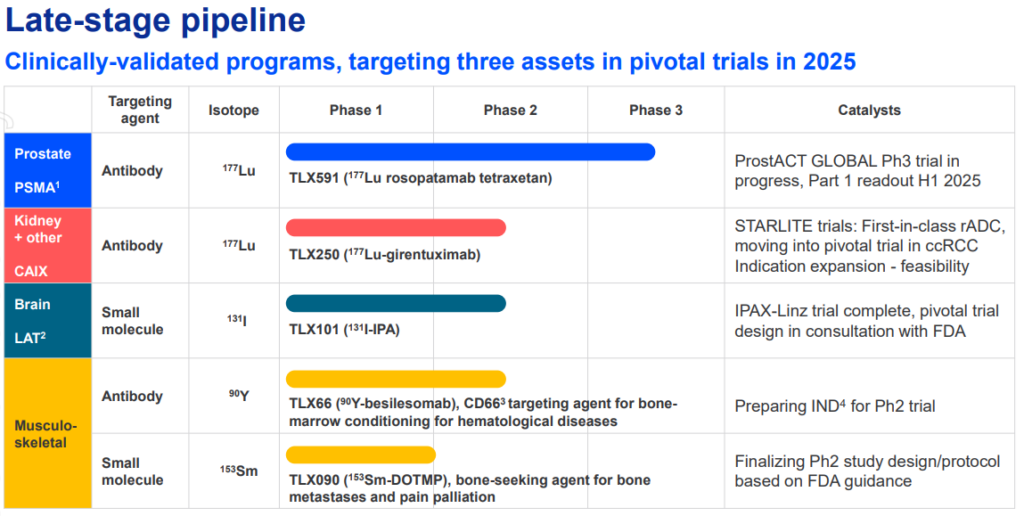
- Progressed ProstACT GLOBAL trial for TLX591 in prostate cancer therapy
- Advanced plans for pivotal trials of TLX250 (kidney cancer) and TLX101 (glioblastoma)
Manufacturing and Partnerships
- Nearing completion of RLS (USA) Inc acquisition, expected to close in Q1 2025
- Installed two new cyclotrons at Brussels South facility, awaiting GMP accreditation
- Partnered with Subtle Medical for AI-powered PET imaging with Illuccix
- Acquired rights for Scintimun® from Curium Pharma
Outlook
Telix is well-positioned for growth in 2025, with multiple product launches planned and advancement of late-stage therapeutic assets. The company’s strong revenue performance, expanded pipeline, and strategic acquisitions indicate potential for significant market expansion. Investors should watch for the FY2025 guidance to be provided with the audited FY2024 results on February 20, 2025
Analyst Expectations
- UBS analysts had maintained a Buy rating with a target price of $32.00, citing management’s “busy-mode” for catalysts in 2025
- The consensus forecast for FY2024 EPS was 22.4 cents, with a PE ratio of 107.2
Key Highlights vs Expectations
- Revenue Growth: The 46% year-over-year growth in Q4 and 55% growth for FY2024 likely exceeded most analyst projections
- Product Pipeline: The company made significant progress across its product pipeline, aligning with UBS’s expectation of multiple potential US product launches
- Strategic Acquisitions: Telix’s acquisition of FAP-targeting assets and the ImaginAb transaction were not explicitly factored into previous analyst forecasts, potentially providing upside to future projections
- Regulatory Milestones: The submission of BLA for TLX250-CDx and FDA acceptance of NDA for TLX101-CDx with Priority Review status align with the positive outlook analysts had for the company’s regulatory progress
- Manufacturing Capabilities: Progress on the RLS acquisition and Brussels South facility buildout supports the company’s growth trajectory, which analysts were anticipating
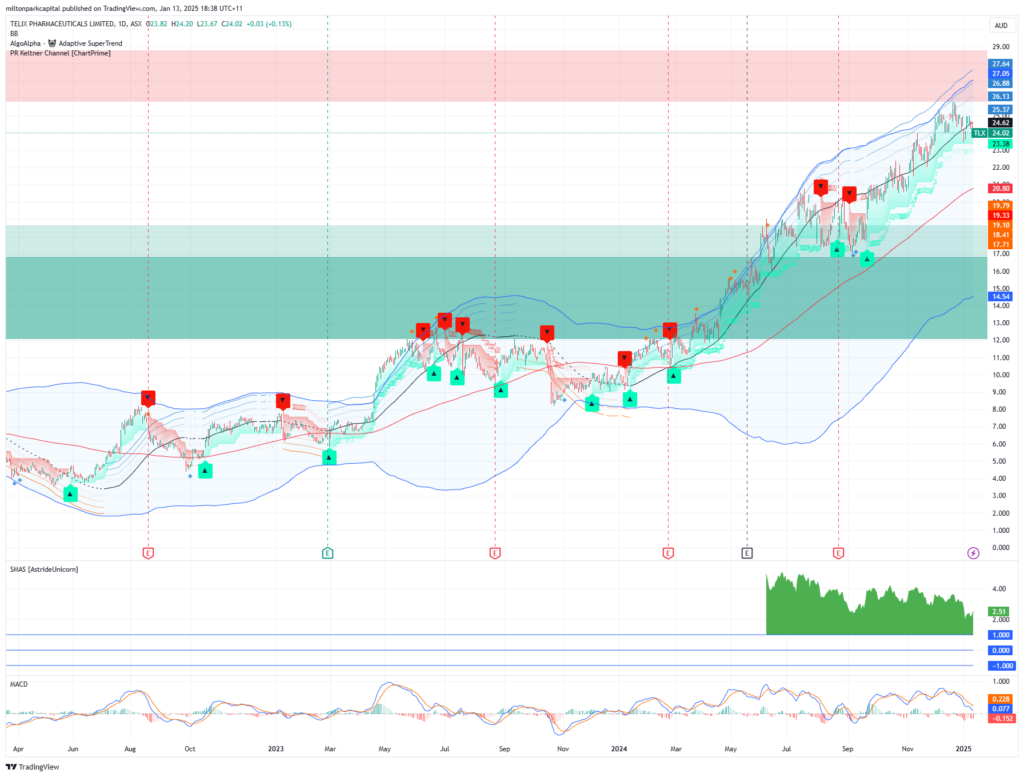
Trim zone increased to $26-$29
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.