
Add to Existing Holding: GQG Partners Inc. (GQG:ASX)
Recommendation: ADD
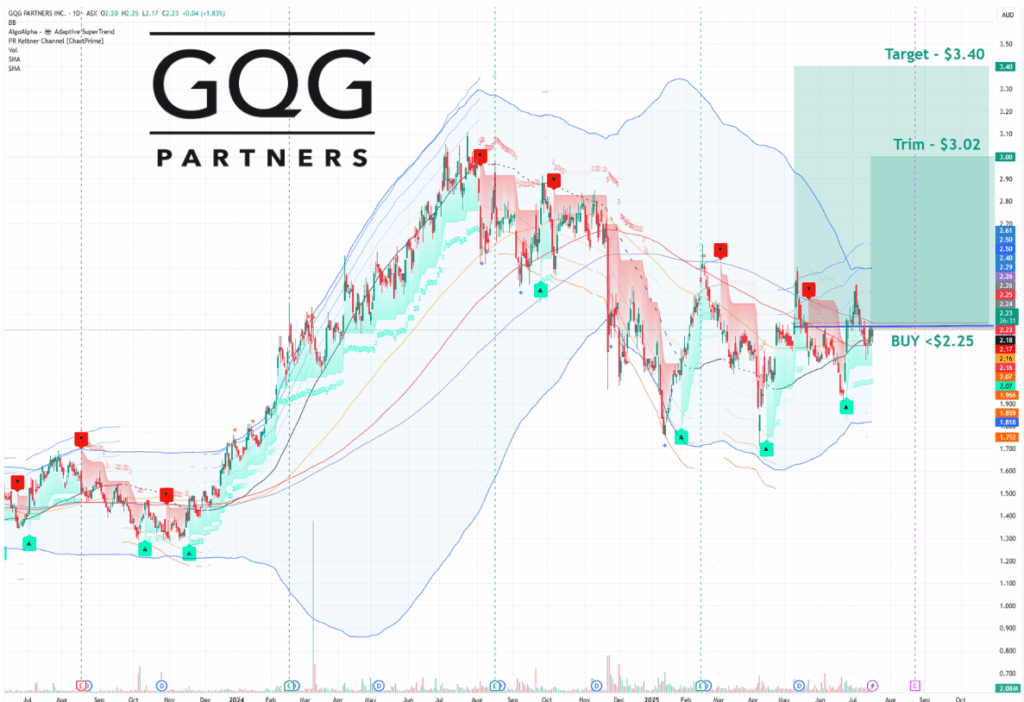
Target Price: A$3.02 (implying ~35% upside from current A$2.23, aligned with analyst fair value estimates)
Position Update: We initiated a holding in GQG on May 9, 2025, at A$2.26, based on the company’s exceptional FY2024 results and strong momentum in Funds Under Management (FUM). Since then, the stock has experienced volatility, dipping to a low of A$1.945 amid broader market fluctuations before recovering partially. As of July 17, 2025, it trades at A$2.23 (down ~1.3% from our entry), which we view as an attractive opportunity to add to the position. Recent US bank earnings highlight sustained market volatility—a key tailwind for GQG’s strategies—while consistent FUM inflows and undervalued metrics reinforce our conviction for long-term outperformance.
Reiterating Core Strengths from Initial Recommendation
GQG offers exceptional value and growth metrics:
- 📈 Revenue growth of 46.9% in FY2024 shows strong business momentum
- 💪 Stellar ROE of 111.2% demonstrates efficient capital allocation
- 💰 Attractive 9.3% dividend yield provides substantial income
- 🔑 P/E ratio of just 9.6x despite strong growth indicates undervaluation
- ⭐ Strong Buy consensus from analysts (1.56 rating) with 25.1% upside to target
- 💵 Excellent ROIC of 118% shows management’s ability to generate returns
- 📊 Fair value upside of 52.1% suggests significant potential appreciation
Recent updates:
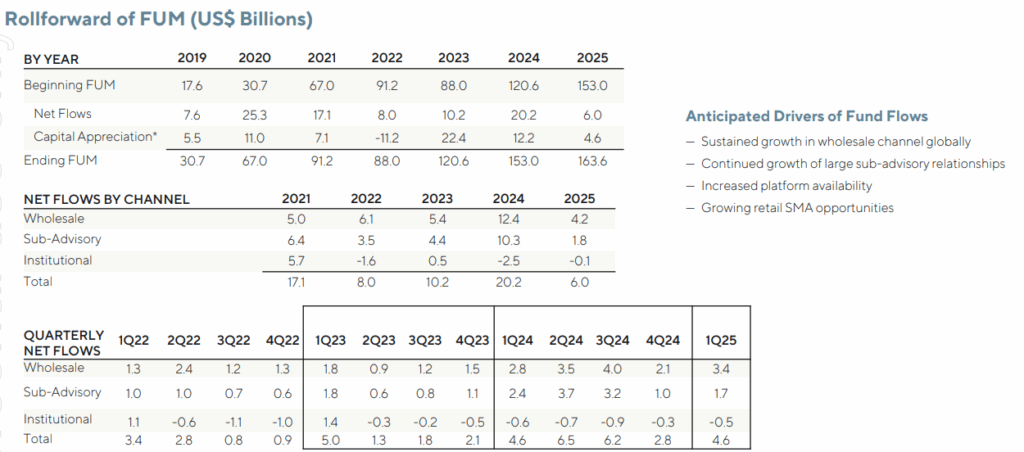
The company reported robust growth in its FY2024 results, with net revenue increasing 46.9% year-on-year to US$760.4 million and net operating income rising 50.4% to US$577.9 million. Their Funds Under Management (FUM) surged to US$153 billion by year-end, driven by strong net inflows of US$20.2 billion and consistent capital appreciation. Their core investment strategies — Global, International, US, and Emerging Markets — have all outperformed their benchmarks over 3-, 5-, and 10-year periods, with a 100% rate of outperformance in rolling 5-year periods, showcasing both skill and consistency in active management.
Additionally, GQG’s competitive edge is reinforced by its capital-efficient operations and shareholder-friendly approach. The firm declared a final dividend with a 90% payout ratio of distributable earnings and expanded its payout range to 50–95%. Strategic initiatives such as the deconsolidation of PCS (Private Capital Solutions), geographic expansion through the Abu Dhabi office, and successful rebranding of their Quality Dividend Income strategy to Quality Value suggest strong future growth and market adaptability. Their recent April 2025 update showed continued momentum, with total FUM growing further to US$163.6 billion and year-to-date net inflows of US$6.0 billion, reflecting sustained demand for their products.
Why Add Now: Volatility Tailwinds from US Bank Earnings and Persistent FUM Growth
The Q2 FY25 earnings from major US banks, released over the past few days, underscore a surge in trading activity fueled by market volatility—precisely the environment where GQG’s strategies excel. Key highlights include:
- Trading Surge Amid Volatility: Goldman Sachs reported its best equity trading quarter in history (up 27% Y/Y to US$4.2 billion), driven by tariffs, interest rate speculation, and hedge fund activity. Morgan Stanley, JPMorgan Chase, Bank of America, and Citigroup echoed this with double-digit trading gains (e.g., Citi’s fixed income up 20% Y/Y). Banks noted “green shoots” in M&A and IPOs, but ongoing uncertainties signal prolonged volatility.
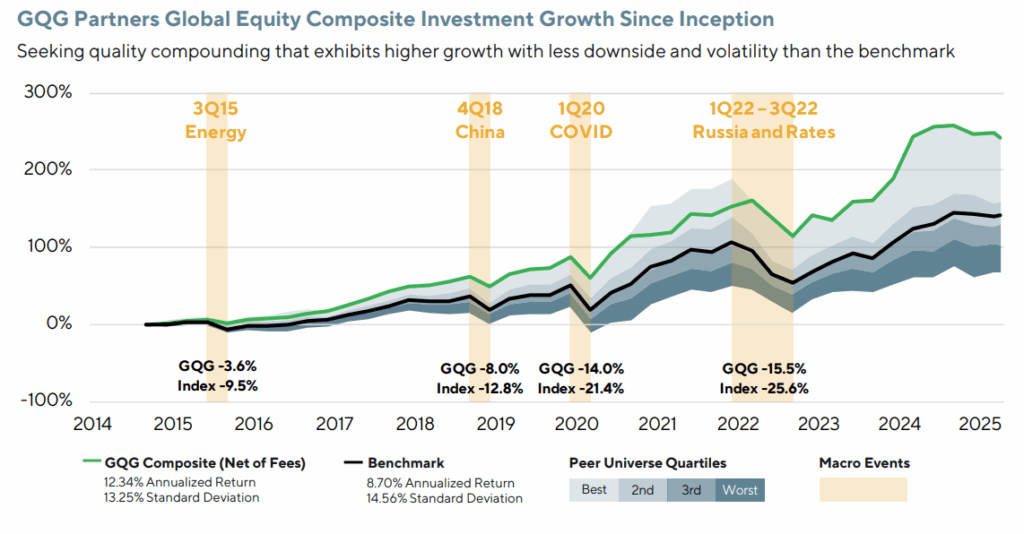
- GQG’s Edge in Choppy Markets: GQG’s Global Equity strategy delivers “all-weather alpha,” with higher growth, less downside, and lower volatility than benchmarks. Since inception, it has outperformed in 100% of rolling 5-year periods. In 2024, the investment team added US$500 billion in asset returns atop market gains, and this setup positions GQG to attract inflows as clients seek protection in volatile conditions.
FUM inflows remain a cornerstone of stability:
- June quarter FUM hit US$172.4 billion (up 2.3% Q/Q), driven by 6.4% net inflows and 4.5% market appreciation. 2025 YTD monthly averages ~US$170 billion, building on 2024’s US$20.2 billion net flows.
- This consistency supports revenue growth (projected +10.9% ahead) via management fees (49.6 bps average), with 76.1% EBITDA and 56.0% net income margins underscoring efficiency.
At A$2.23, GQG trades at a forward P/E of 9.6x (PEG 1.67), free cash flow yield of 9.7%, and shareholder yield of 8.8%—undervalued for its growth. Consensus remains “Strong Buy,” with targets supporting our A$3.02.
Risks and Outlook
Volatility could pressure FUM if markets downturn sharply, and high payouts (96.5%) limit buffers. However, low beta (0.1), resilient ROE (111.2%), and bank earnings’ upbeat tone on consumer strength mitigate this. Add to holdings for income (9.6% yield) and growth in uncertain times.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns