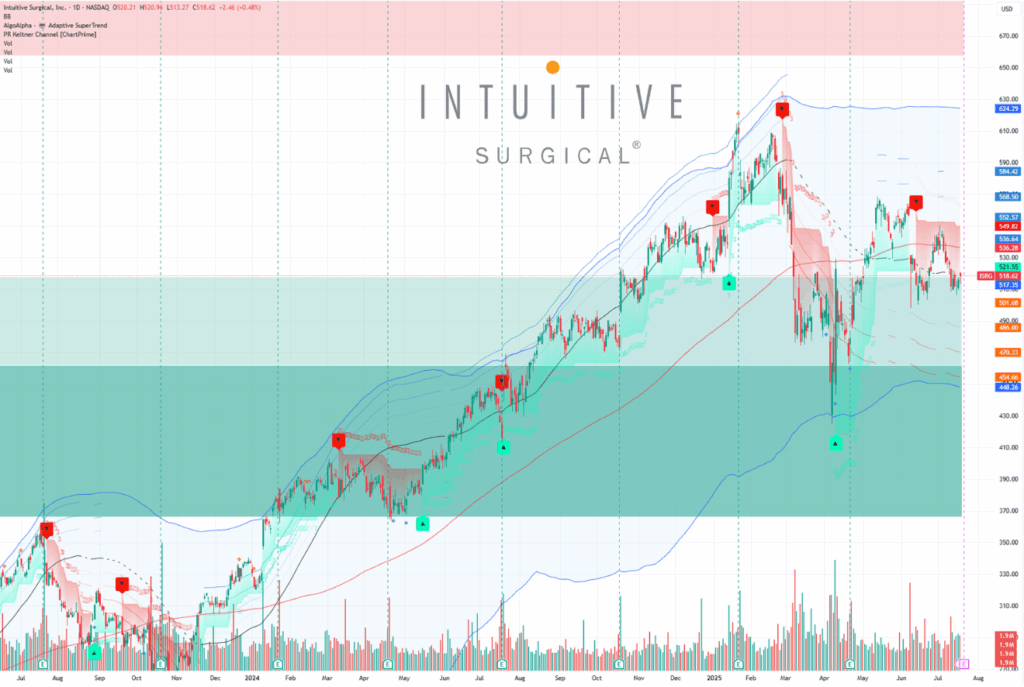
Intuitive Surgical (NASDAQGS:ISRG) heads into earnings riding a wave of high expectations, with analysts forecasting Q2 revenue of $2.35B and EPS of $1.93—both sharp jumps from last year’s levels. But here’s where it gets interesting: at a current price of $518.62, ISRG trades at a forward P/E of 65.3x and EV/EBITDA of 45.7x, a premium that demands near-flawless delivery.
 Strong Growth, High Bar
Intuitive Surgical’s projected 2025 revenue growth of 15.9% and EPS growth of 23.7% outpace most medtech peers, fueled by international expansion and the adoption of the new DV5 system. The company’s EBITDA growth forecast of 37.0% is eye-popping, and return metrics—ROIC at 14% and ROE at 15.6%—signal operational strength.
 Innovation Driving the Story
Recent headlines spotlight Intuitive’s pioneering moves, including a transatlantic telesurgery demo and FDA clearance for the Vessel Sealer Curved instrument (Read more, 16 Jul 2025). With nearly 17 million da Vinci procedures performed and 90,000 surgeons trained, Intuitive’s lead in robotic surgery is a massive moat.
 Valuation: Sky-High, for Now
Here’s the tension: While analysts’ consensus target sits at $590, proprietary fair value models peg ISRG closer to $406.44—a -21.6% downside. The stock’s premium multiples reflect both its dominant position and the market’s faith in continued innovation. But with competition intensifying and tariff risks looming (potentially trimming 200bps off gross margin), the margin for error is razor-thin.
 Bull vs. Bear: Who Wins?
- Bull case: Momentum from the DV5 launch, robust procedure growth, and expanding international sales could justify the premium, especially if Q2 results beat expectations (as they did in Q1: $1.81 EPS vs. $1.74 forecast).
- Bear case: Any stumble—on regulatory, pricing, or margin fronts—could trigger sharp multiple compression. Deutsche Bank’s recent downgrade and a $440 price target highlight this risk (Read more, 10 Jul 2025).
 Snapshot: ISRG Earnings & Valuation
| Metric | Value | WarrenAI Take |
|---|---|---|
| Price (7/18/25) | $518.62 | At high end of 52w range |
| Fwd P/E | 65.3x | Premium, innovation priced in |
| 2025 Rev. Growth | 15.9% | Outpacing sector |
| 2025 EPS Growth | 23.7% | Strong, but priced for perfection |
| Analyst Target | $590.00 | 7.4% implied upside |
Insights 
- No dividend: All returns must come from price appreciation.
- Beta 1.65: Expect volatility, not stability.
- Analyst split: Most bullish, but key bears remain.
 Verdict
ISRG’s innovation engine and global footprint make it a medtech juggernaut, but at these valuations, the company must keep executing flawlessly. If you believe in continued robotic surgery adoption and Intuitive’s ability to out-innovate, the long-term case stays strong—but risk is as high as the reward.