Our analysis indicates PLS demonstrated solid operational execution in Q1 FY26, achieving a 2% production increase to 224.8kt and a significant 24% jump in realized spodumene price to US$742/t. This, coupled with disciplined cost management resulting in a 9% year-on-year decrease in CIF costs to US$422/t, drove 30% revenue growth to A$251 million, exceeding analyst expectations on price and cost metrics. These fundamentals validate our earlier entry point and current valuation.
PLS maintains a strong competitive position through cost leadership and operational stability post-Pilgangoora expansion. The company is well-placed to navigate near-term lithium price volatility, supported by robust long-term demand fundamentals driven by electric vehicle and battery storage growth. While market sentiment remains mixed, reflected in divergent broker targets, PLS’s execution demonstrates resilience.
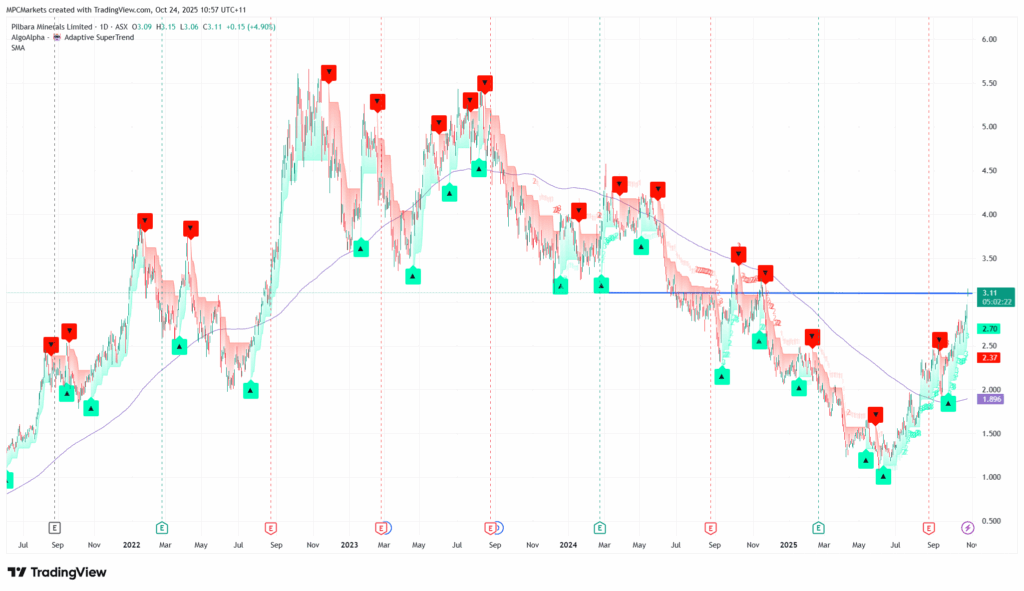
Given the substantial recent share price appreciation, coinciding with hitting key technical resistance near 3.1, we recommend taking profit at 0.01. This action locks in gains from strong fundamentals and favorable market positioning. However, investors should remain mindful of ongoing lithium market dynamics, particularly Chinese supply developments and price sustainability in the second half of CY2025.
Market Environment:
Lithium demand continues robust growth driven by electric vehicle and battery storage expansion, evidenced by demand tripling since 2020. However, significant near-term price volatility persists, with spodumene trading between 600 and 1000 dollars per tonne in CY2025. This environment creates opportunities but also exposes producers to sharp price inflections, particularly around Chinese regulatory actions and supply dynamics. PLS operates within this heightened sensitivity, where broker price targets for 2026 range significantly, reflecting divergent views on sustainability.
Financial Performance:
PLS demonstrated strong operational and financial execution in the September 2025 quarter. Production increased 2 per cent quarter on quarter to 224.8 kilotonnes, with sales stable at 214.0 kilotonnes post-expansion. Crucially, the realized spodumene price surged 24 per cent to 742 dollars per tonne, significantly beating analyst forecasts, driving a 30 per cent revenue increase to 251 million dollars. Unit operating costs (CIF) fell 9 per cent year on year to 422 dollars per tonne, outperforming consensus expectations and demonstrating strong cost discipline, though cash reserves decreased 13 per cent to 852 million dollars due to capital deployment.
Competitive Position & Catalysts:
PLS maintains a competitive edge through its Pilgangoora operation, achieving cost leadership in a volatile market. The strong Q1 results, particularly the significant price and cost beat versus major analysts, highlight operational resilience. Key near-term catalysts include the Colina resource update expected in 4Q26, which could unlock further value, and ongoing Pilgangoora optimisation. Additionally, lithium’s recent classification as a rare earth element provides a supportive macro backdrop for the sector, although the primary catalyst for action here is technical.
Risk Considerations & Technical Action:
While structural demand supports the long-term thesis, near-term risks remain pronounced. Persistent oversupply concerns and significant lithium price volatility are primary headwinds, with forecasts indicating potential price weakness. Our analysis confirms PLS has executed well operationally and financially. However, the share price has reached a significant technical resistance level near 3.1. Given this achieved target and the inherent near-term risks in the lithium market, we believe it is prudent to take profit and lock in gains from this highly successful entry. This action mitigates downside risk while preserving capital to redeploy.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.