Balanced Portfolio & Growth Recommendation
Date: 14/11/2024
*** GENERAL ADVICE ONLY***
Summary of GrainCorp’s FY24 earnings results:
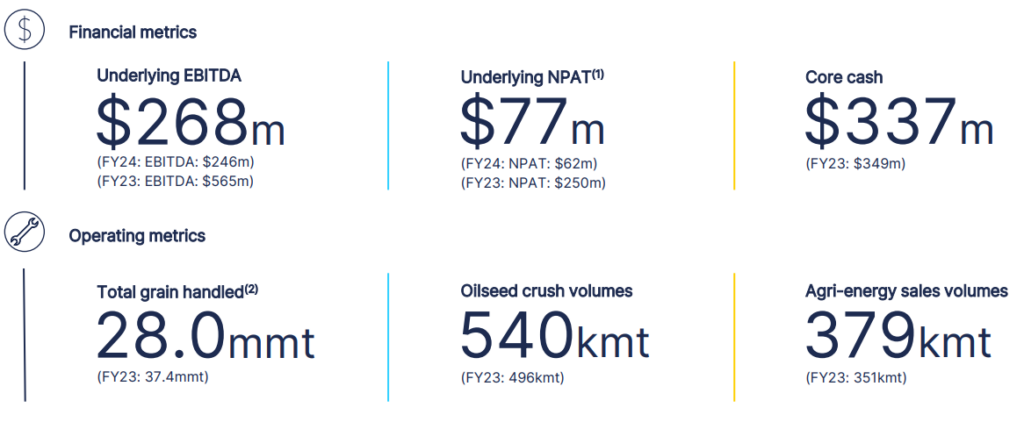
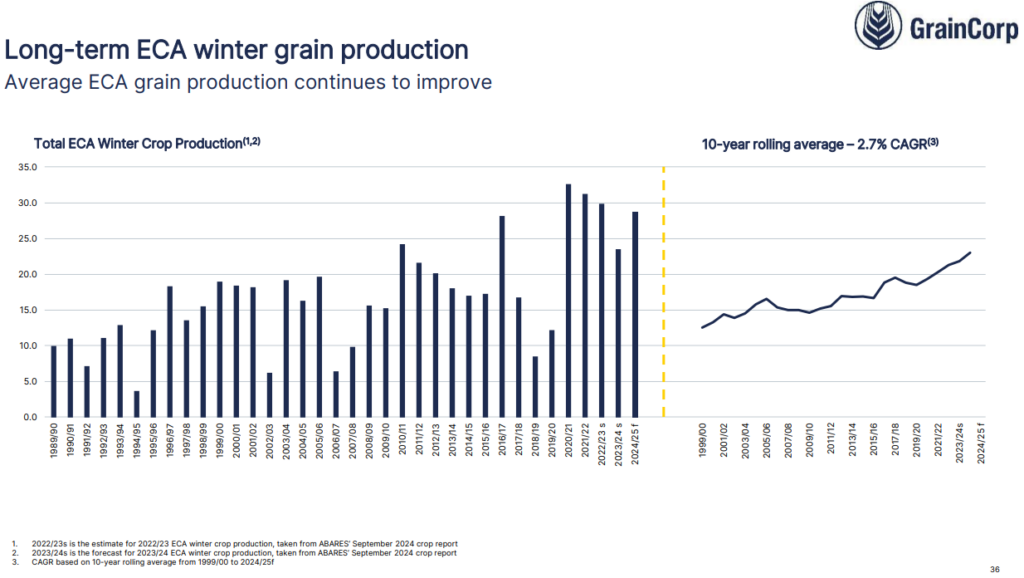
GrainCorp delivered a resilient FY24 performance amid challenging market conditions, with underlying EBITDA of $268 million, down from $565 million in FY23. The decline was primarily due to lower grain production volumes in East Coast Australia and Western Australia, as well as compressed margins globally.
Key positives:
- Record oilseed crush volumes of 540,000 tonnes
- Strong balance sheet with $337 million in core cash
- Continued growth in Animal Nutrition and Agri-energy sales volumes
- Strategic acquisition of XF Australia to expand Animal Nutrition portfolio
- Maintained shareholder returns with 48 cents per share in dividends
Challenges:
- Lower grain handling volumes of 28.0 million tonnes, down from 37.4 million in FY23
- Compressed crush margins due to global market conditions
The company’s tone remains cautiously optimistic, highlighting its operational discipline and strategic initiatives. GrainCorp has increased its average earnings through-the-cycle EBITDA target to $320 million, demonstrating confidence in its long-term prospects.
The focus on diversification, operational efficiency, and strategic growth opportunities positions the company well for future performance, despite near-term headwinds in the grain and oilseed markets.
Overall, GrainCorp’s actual dividend of 48 cents per share exceeded all broker forecasts, which ranged from 32.00 to 42.80 cents and EPS* outpaced broker expectations by around 4cps at 33.77
GrainCorp’s FY24 results:
Underlying EBITDA:
- $268 million
- Underlying NPAT: $77 million
- Total dividends: 48 cents per share fully franked
Comparing to broker expectations:
Bell Potter:
- Forecasted FY24 dividend: 32.00 cents (actual was higher at 48 cents)
- Forecasted FY24 EPS: 30.40 cents (actual EPS not provided, but can be calculated from NPAT)
Macquarie:
- Forecasted FY24 dividend: 42.80 cents (actual was higher at 48 cents)
- Forecasted FY24 EPS: 29.80 cents
Ord Minnett:
- Forecasted FY24 dividend: 38.00 cents (actual was higher at 48 cents)
- Forecasted FY24 EPS: 27.70 cents
*EPS: Regarding earnings, without the actual EPS figure, it’s harder to make a direct comparison. However, we can calculate an approximate EPS based on the reported Underlying NPAT of $77 million. Assuming around 228 million shares outstanding (based on recent reports), this would equate to an EPS of about 33.77 cents. Using this calculation, it would mean GrainCorp’s earnings slightly exceeded most broker expectations.
It’s worth noting that Bell Potter had downgraded their rating to Hold from Buy prior to the results, while Macquarie maintained an Outperform rating and Ord Minnett had a Buy rating.
The actual results, particularly the higher-than-expected dividend, seem to align more closely with the more optimistic outlooks from Macquarie and Ord Minnett
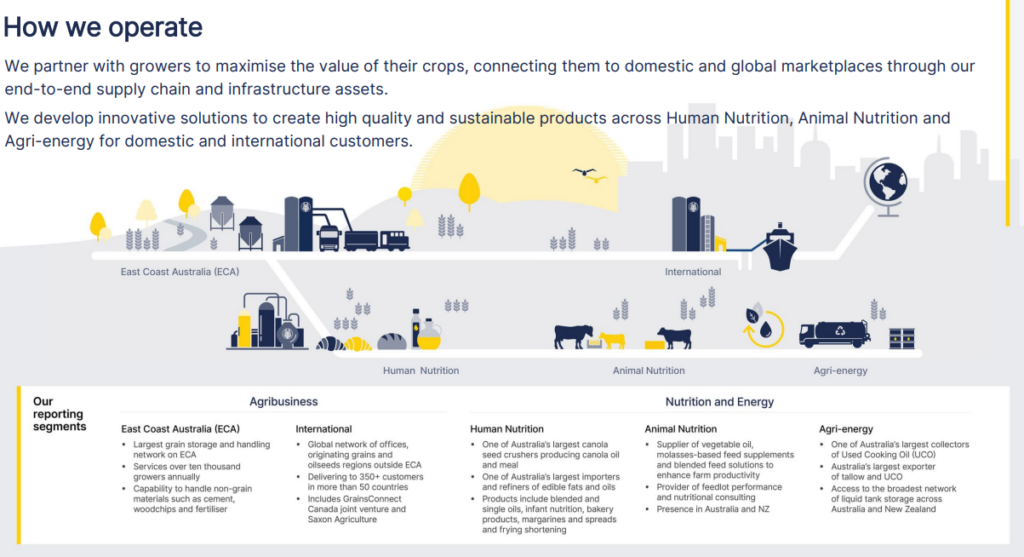
Annual Report Infographics
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.