***GENERAL ADVICE ONLY***
Steadfast Group (ASX: SDF) has delivered a robust 1H25 performance, reinforcing its position as the largest general insurance broker network and underwriting agency group in Australasia. The company achieved double-digit growth across key financial metrics, driven by a disciplined acquisition strategy, organic expansion, and operational efficiencies. With strong premium growth, expanding international operations, and a focus on margin improvement, Steadfast continues to capitalize on its scale and strategic positioning to drive sustainable long-term returns.
Financial Performance
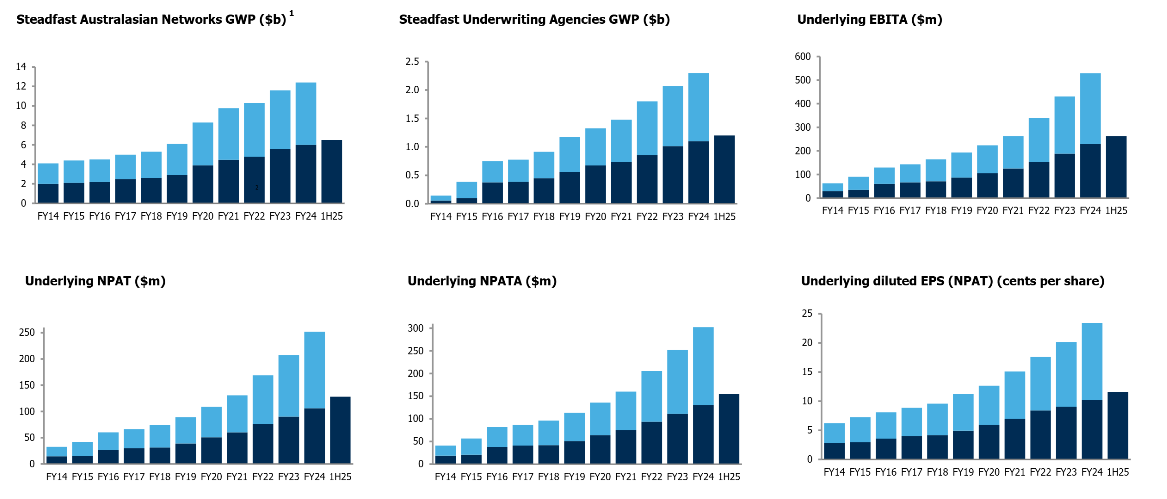
- Underlying NPAT: $128.1M, +20.9% YoY, driven by strong operational execution and acquisitions.
- Underlying NPATA: $154.6M, +19.0% YoY, reflecting growth in core operations and acquisitions.
- Underlying EBITA: $262.4M, +14.6% YoY, driven by:
- Organic growth: +9.1% (leveraging existing businesses).
- Acquisition growth: +5.5% (new equity stakes in subsidiaries).
- Statutory NPAT: $106.4M, up from $100.4M in 1H24.
- Underlying Revenue: $881.3M, +11.5% YoY, fueled by higher commissions, organic business growth, and premium rate increases.
- Underlying Diluted EPS (NPAT): 11.6c per share, +14.1% YoY, reflecting earnings growth and disciplined capital management.
Growth Breakdown
- Core organic growth: +9.1%, driven by existing businesses, higher commissions, and cost efficiencies.
- Acquisition growth: +5.5%, contributions from strategic acquisitions and increased equity stakes in brokers and underwriting agencies.
Business Segment
Steadfast Australasian Broker Network
- Gross Written Premium (GWP): $6.5B, +7.9% YoY, driven by:
- +5.2% organic growth (premium rate increases & new policies).
- +2.6% growth from AR network.
- +0.1% growth from net new brokers.
Network Expansion
- 5 new brokers joined in 1H25.
- 409 network brokers (up from 342 at IPO).
- 16 new equity stakes acquired in brokers.
Key Trends
- Premium pricing stabilizing at mid-single-digit growth.
- Increased competition in the mid-to-large commercial market, while personal lines and SME remain stable.
Steadfast Underwriting Agencies
- GWP: $1.22B, +11.7% YoY, benefiting from pricing power, strong retention, and new business initiatives.
- Underlying EBITA: $106.4M, +15.8% YoY, driven by:
- +7.0% organic growth (better pricing and retention).
- +4.7% acquisition growth (expanded capacity and market share).
Key Developments
- Increased premium pricing power due to favorable market conditions.
- Investment in automation and data analytics to enhance underwriting efficiency.
- Expansion into the London market via new acquisitions.
Steadfast International Expansion
ISU Steadfast (USA)
- Performed ahead of expectations, driven by:
- Higher profit sharing (+15%).
- Strong membership growth (now 235 agencies).
- Better cost control & margin expansion.
London Market Expansion
- Acquired H.W. Wood’s UK & Greece businesses and HWI France.
- Strengthens wholesale broking and binder management.
- Strategic positioning for global expansion.
Acquisition Activity
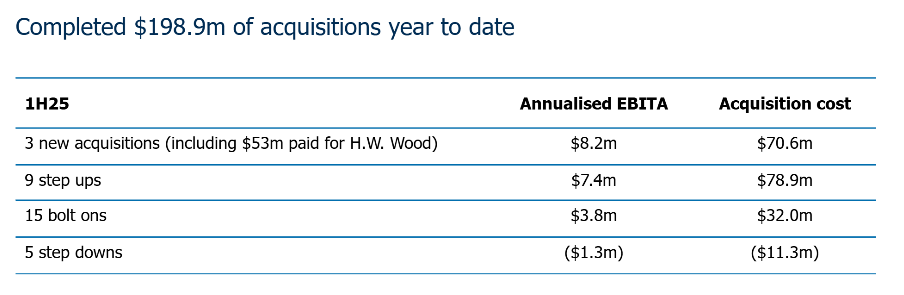
- $198.9M in acquisitions completed YTD, including:
- 3 new acquisitions ($70.6M).
- 9 step-up acquisitions ($78.9M) (increased equity stakes).
- 15 bolt-on acquisitions ($32M).
- $53M spent on H.W. Wood acquisition.
- FY25 target: $300M in acquisitions.
FY25 Guidance & Outlook
Revised Guidance
- Underlying EBITA: $585M – $595M (slightly revised down from $590M – $600M).
- Underlying NPAT: $290M – $300M (unchanged).
- Underlying NPATA: $340M – $350M (unchanged).
- Underlying Diluted EPS Growth (NPAT): 12% – 16% YoY.
Key Assumptions
- Mid-single-digit insurance premium rate increases expected in 2H25.
- $300M in acquisitions targeted for FY25.
- No major regulatory changes impacting commissions.
Market & Regulatory Environment
- Reinsurance market improving: December 2024 renewals were favorable, but catastrophe (CAT) losses remain uncertain.
- Regulatory Risks:
- Treasury Laws Amendment (M&A Reform) Act 2024 – Steadfast engaging with ACCC before full implementation in 2026.
- Strata legislation changes in NSW – Enhanced transparency requirements not expected to materially impact business.