Telix Phama TLX:ASX
GENERAL ADVICE ONLY
21st February 2025
- Overview
Telix Pharmaceuticals Limited has demonstrated remarkable growth in its FY2024 earnings report, showcasing significant improvements across key financial metrics. The company’s strategic initiatives and product pipeline have positioned it strongly within the biopharmaceutical sector, reflecting an optimistic outlook for future performance.
Key Highlights:
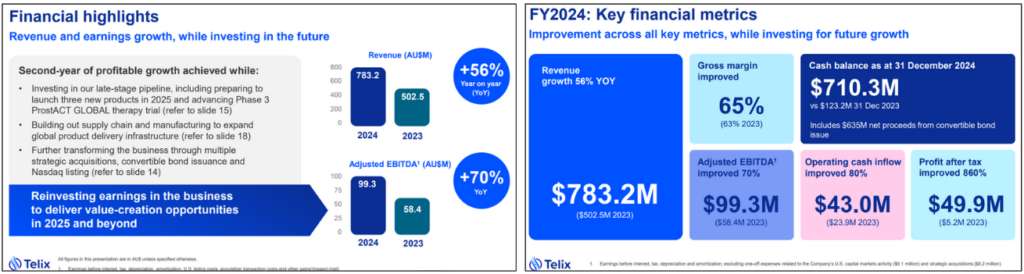
- Revenue increased by 56% year-over-year, reaching AU$783.2 million.
- Adjusted EBITDA surged by 70%, totaling AU$199.3 million.
- Profit after tax skyrocketed by 860%, amounting to AU$49.9 million.
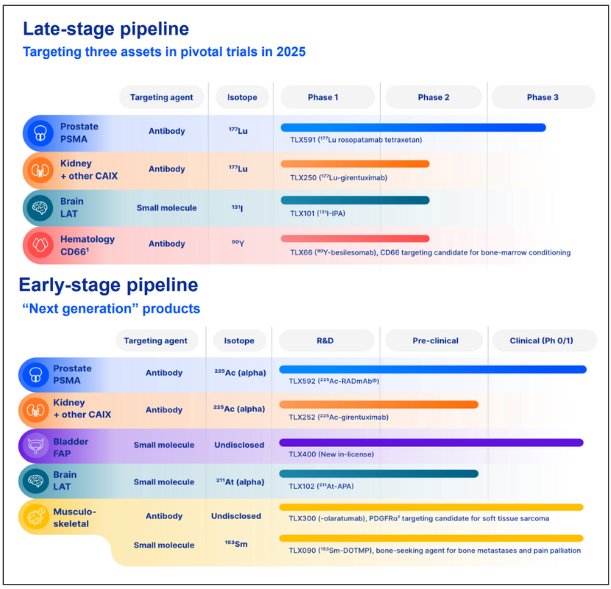
- Preparation underway for the launch of three new diagnostic products in 2025.
Impactful News: The substantial profit growth is primarily driven by the successful execution of strategic projects and the anticipated product launches slated for the next fiscal year.
- Financial Performance
Telix Pharmaceuticals has exhibited robust financial growth in FY2024, outperforming its FY2023 figures across multiple dimensions.
Key Metrics
- Revenue:
- FY2024: AU$783.2 million
- FY2023: AU$502.5 million
- Growth: +56%
- Adjusted EBITDA:
- FY2024: AU$199.3 million
- FY2023: AU$58.4 million
- Growth: +70%
- Profit After Tax:
- FY2024: AU$49.9 million
- FY2023: AU$5.2 million
- Growth: +860%
Revenue & Growth Trends
The 56% increase in revenue signifies Telix’s expanding market presence and effective sales strategies. This growth is likely supported by the successful commercialization of existing products and the strengthening of distribution channels.
Margin & Profitability Metrics
The Adjusted EBITDA margin improvement of 70% highlights enhanced operational efficiency and cost management. The dramatic rise in profit after tax by 860% underscores significant net profitability, potentially driven by higher margins and controlled expenses.
Year-over-Year (YoY) Changes
All key financial metrics have shown substantial YoY improvements, reflecting the company’s ability to scale operations and capitalize on market opportunities effectively.
- Guidance and Expectations
Looking ahead, Telix Pharmaceuticals has outlined a promising roadmap centered around the launch of three new diagnostic products in 2025.
Forward Guidance
- Product Launches: Scheduled introduction of TLX007-CDx (Gozellix®), TLX101-CDx (Pixclara®), and TLX250-CDx (Zircaix®).
- Revenue Projections: Anticipated revenue growth driven by new product adoption and market expansion.
- Investment in R&D: Continued focus on research and development to foster innovation and sustain competitive advantage.
Management Commentary
The management has expressed confidence in the upcoming product launches, citing robust pipeline development and strong market demand for advanced diagnostic solutions. They anticipate these launches will further accelerate revenue growth and enhance profitability in the subsequent fiscal years.
Operational Initiatives
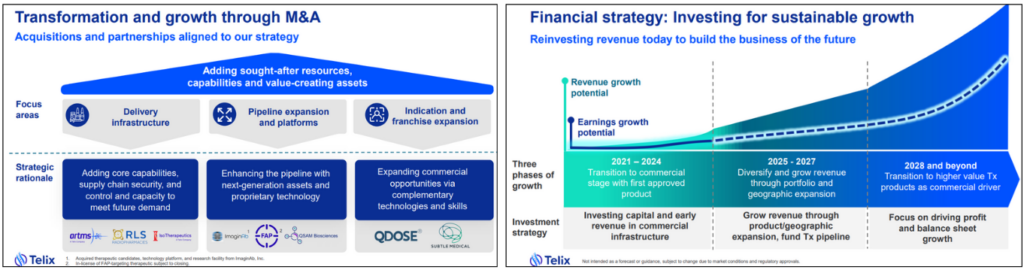
- Streamlining manufacturing processes to reduce costs and increase scalability.
- Enhancing supply chain management to ensure timely delivery of products.
Capital Allocation Plans
- Research & Development: Significant investments in R&D to support product innovation and development.
- Capital Expenditures (CapEx): Expansion of production facilities to meet rising demand.
Impact on Outlook
These strategic moves are expected to improve operational leverage, reduce costs, and enhance the company’s ability to capitalize on growth opportunities. In the near term, this will likely translate into sustained revenue growth and improved profitability, while in the long term, it will support Telix’s vision of becoming a dominant player in the diagnostics market.
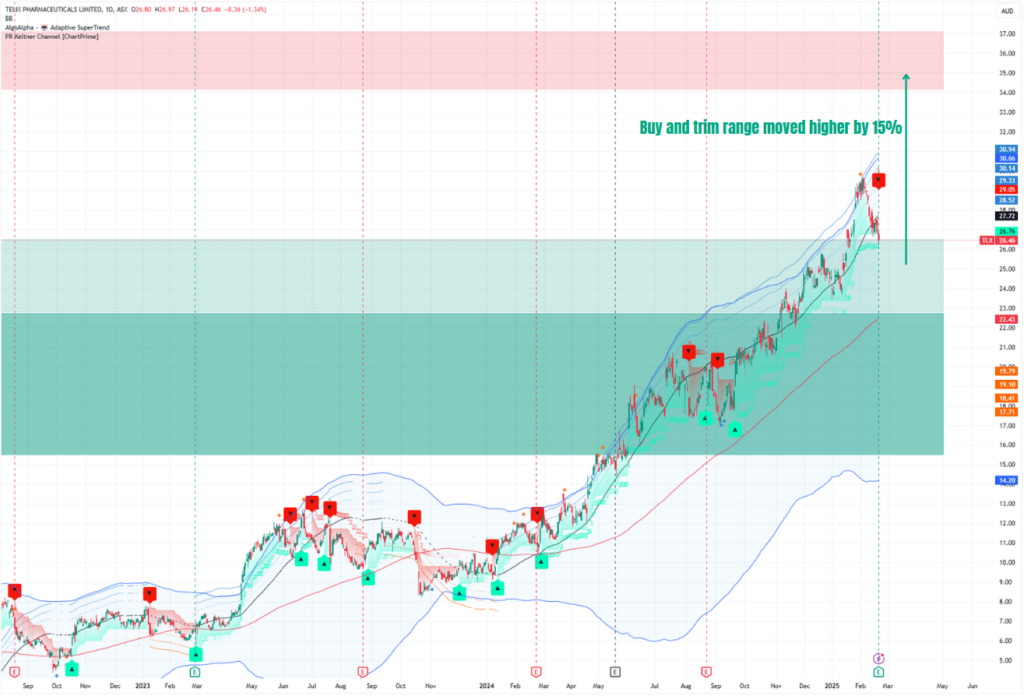
Results vs Broker Consensus
Telix Pharmaceuticals financial results for FY2024, exceeding analysts’ expectations in several key areas:
- Revenue: $783.2 million, up 56% year-over-year, beating full-year guidance.
- Net Profit: $49.9 million, a significant increase from $5.2 million in FY2023, surpassing expectations.
- Adjusted EBITDA: $99.3 million, up 70% from the previous year.
- Gross Margin: Improved to 65% from 63% in FY2023.
- Cash Balance: Grew substantially to $710.3 million from $123.2 million.
The company’s performance was driven by strong sales of Illuccix® in the U.S. and successful strategic acquisitions. Telix also provided FY2025 revenue guidance of $1.18-1.23 billion, indicating continued growth.
Analysts’ reactions were generally positive. UBS maintained a Buy rating with a $32 target price, citing potential catalysts in 2025. However, Bell Potter downgraded to Hold due to share price appreciation, despite acknowledging strong results.
Overall, Telix’s earnings report demonstrated robust growth and exceeded market expectations, positioning the company for further expansion in 2025.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns