Judo Capital Holdings JDO:ASX
Judo Bank (JDO:ASX) has released its earnings report for the first half of fiscal year 2025 (1H25), demonstrating strong growth and improved financial performance. Here are the key highlights:
Financial Performance
- Underlying profit before tax (PBT) grew by 33% compared to 2H24, reaching $56.7 million.
- Statutory net profit after tax (NPAT) increased by 70% to $40.9 million.
- Return on equity (ROE) improved to 5.1%, up 200 basis points from 3.1% in 2H24.
Lending and Growth
- Gross loans and advances (GLA) grew to $11.65 billion, a 9% increase from 2H24.
- Gross originations for 1H25 increased to $2.3 billion, up from $1.8 billion in 1H24.
- The company expanded into new regions and segments, with 10 new locations and 20 additional bankers targeted for FY25.
Net Interest Margin (NIM) and Funding
- 1H25 NIM was 2.81%, slightly down from 2.85% in 2H24.
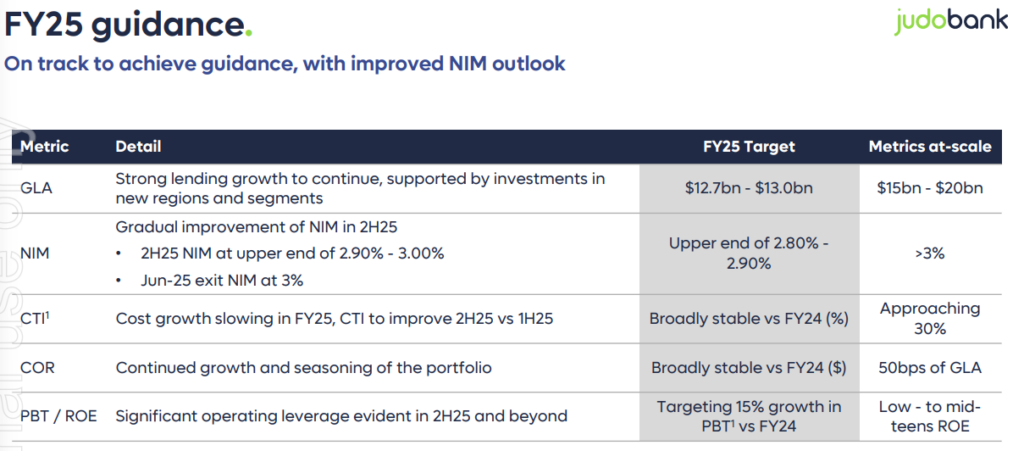
- The company expects NIM improvement in 2H25, with guidance for FY25 at the upper end of 2.80% – 2.90%.
- Deposit funding increased, expected to reach ~70% of total funded assets.
Asset Quality and Provisions
- 90+ days past due and impaired assets remained stable at 2.30% of GLA.
- Cost of risk improved, with impairment expense decreasing by 33% compared to 2H24.
- Total provision coverage remained stable at 1.37% of GLA.
Capital and Efficiency
- Common Equity Tier 1 (CET1) ratio remained strong at 13.8%.
- Cost-to-income ratio (CTI) increased slightly to 57.4% from 56.3% in 2H24.
- The company is targeting 15% growth in PBT for FY25 compared to FY24.
Outlook
Judo Bank expects continued strong lending growth, improved NIM, and emerging operating leverage in 2H25. The company is on track to achieve its FY25 guidance and is progressing towards its at-scale metrics, including a target ROE in the low-to-mid teens.
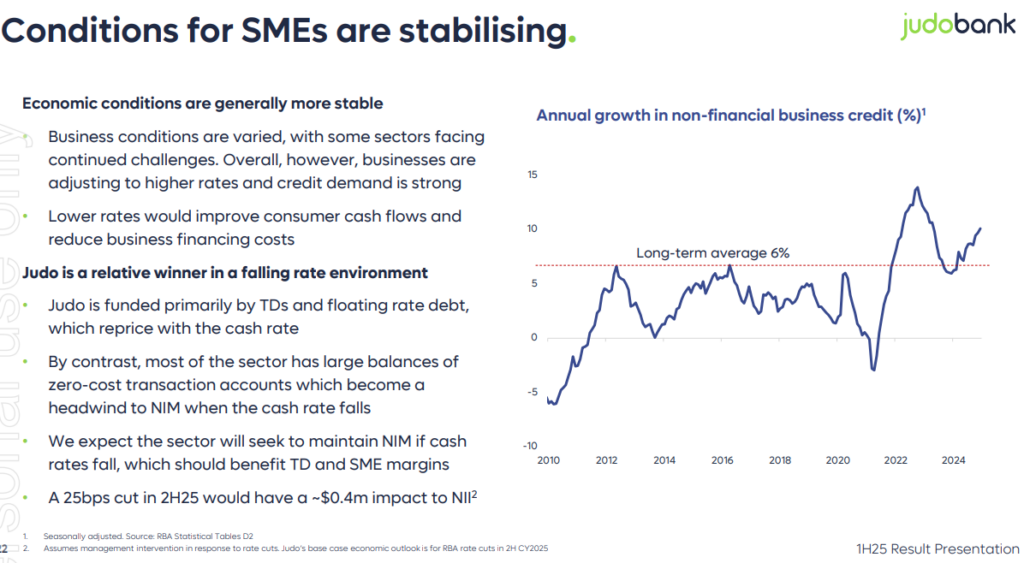
It will be difficult for major banks to hold back rate cuts in mortgages, given ongoing competition, Bayliss suggested, predicting the majors would look to reduce the pass-through to small business, where pricing is less transparent, to protect margins.
“We expect the sector will seek to maintain [lending margins] if cash rates fall, which should benefit term deposit and [small business] margins,” the company said. Its term deposits reprice with the cash rate.
Rate cuts “may further support the environment [for Judo] in the near term,” Macquarie analyst Jason Shao said.
Still, competition is increasing. The major banks – along with Macquarie, AMP and ING – are chasing small and medium businesses.
Judo, which runs a traditional relationship banking model, has 159 bankers, and will hire a further 20 in the next six months. Each runs an average of 28 customers, compared to the industry average of more than 100. The bank says this helps monitor credit quality, which was stable over the half with 2.3 per cent of the book 90 days past due or impaired.
Milford senior investment analyst Minh Pham said Judo’s result pointed to “the strength of the underlying SME economy as demand for credit remains robust and businesses continue to invest”.
Broker Consensus on Judo Capital’s Earnings
The recent earnings report from Judo Capital (JDO) has generated mixed reactions from brokers, though most view the results positively. Here’s a summary of their perspectives:
Positive Aspects
- Better-than-expected results: Most brokers noted that Judo’s 1H25 earnings beat market expectations.
- Strong growth: Morgans highlighted the company’s strong FY26-27 growth potential as a key attraction.
- Margin improvement: UBS and Morgan Stanley were encouraged by the net interest margin (NIM) trends.
- Reaffirmed guidance: Management reiterated FY25 guidance for 15% pre-tax profit growth12.
Areas of Concern
- Asset quality: Citi expressed concerns about rising non-performing loans and declining provision coverage.
- Competition risks: Macquarie sees potential risks to longer-term margins from lending and deposit competition2.
- Reliance on capital growth: Morgans pointed out that investors are entirely dependent on capital growth due to the absence of dividends1.
Outlook and Ratings
Broker | Rating | Target Price | Key Focus |
Morgans | Hold | $2.08 | Long-term growth potential |
Macquarie | Neutral | $1.85 | Competition risks |
Citi | Sell | $1.60 | Asset quality concerns |
UBS | Buy | $2.55 | Scaling and operating leverage |
Morgan Stanley | Overweight | $2.30 | FY26 outlook |
Ord Minnett | Buy | $2.50 | NIM expansion potential |
Consensus View
While there is no unanimous consensus, the majority of brokers maintain a positive to neutral outlook on Judo Capital. The company’s ability to scale, demonstrate operating leverage, and manage asset quality will be crucial factors in its future performance. The upcoming FY26 guidance, expected in August, is seen as a potential catalyst for a step change in profitability.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns