
Macquarie Group (ASX:MQG) SELL take 15%+ Profit
While Macquarie will remain a long-term pick, the current valuation appears stretched with several red flags:
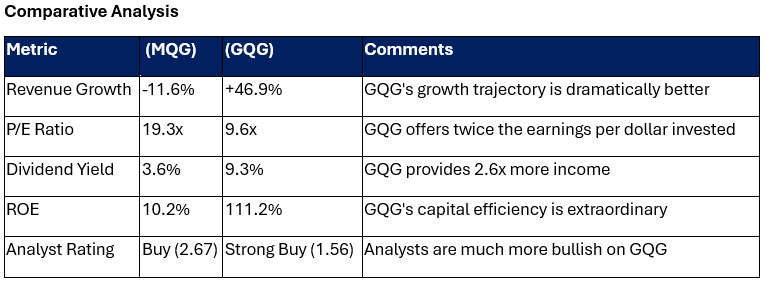
- 📉 Revenue declined 11.6% in FY2024, showing business contraction
- ⚠️ Regulatory troubles mounting – ASIC just imposed additional license conditions due to “numerous serious compliance failures” that remained undetected for a decade
- 💸 Cash burn concerns – Context indicates the company is “quickly burning through cash”
- 🔍 Weak profit margins – Suffering from poor gross profit margins
- 💰 Poor free cash flow yield implied by current valuation
- 📊 P/E ratio of 19.3x is relatively high for a financial institution with declining revenue
We would still like to maintain exposure to the Financials sector and GQG is an attractive buy at the moment for several compelling reasons
GQG offers exceptional value and growth metrics:
- 📈 Revenue growth of 46.9% in FY2024 shows strong business momentum
- 💪 Stellar ROE of 111.2% demonstrates efficient capital allocation
- 💰 Attractive 9.3% dividend yield provides substantial income
- 🔑 P/E ratio of just 9.6x despite strong growth indicates undervaluation
- ⭐ Strong Buy consensus from analysts (1.56 rating) with 25.1% upside to target
- 💵 Excellent ROIC of 118% shows management’s ability to generate returns
- 📊 Fair value upside of 52.1% suggests significant potential appreciation
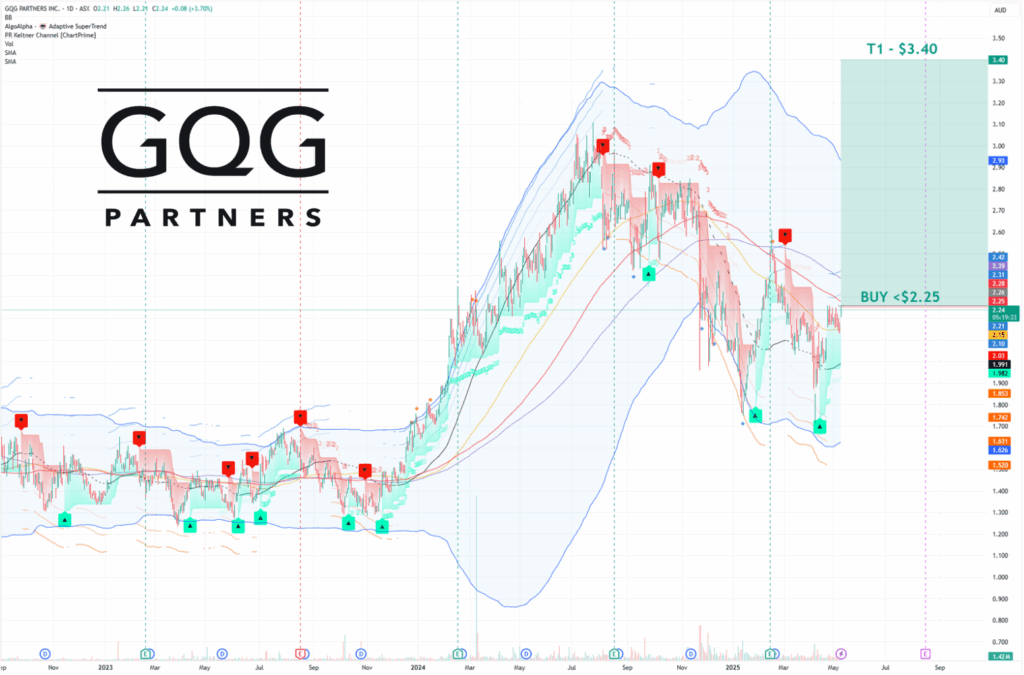
The company reported robust growth in its FY2024 results, with net revenue increasing 46.9% year-on-year to US$760.4 million and net operating income rising 50.4% to US$577.9 million. Their Funds Under Management (FUM) surged to US$153 billion by year-end, driven by strong net inflows of US$20.2 billion and consistent capital appreciation. Their core investment strategies — Global, International, US, and Emerging Markets — have all outperformed their benchmarks over 3-, 5-, and 10-year periods, with a 100% rate of outperformance in rolling 5-year periods, showcasing both skill and consistency in active management.
Additionally, GQG’s competitive edge is reinforced by its capital-efficient operations and shareholder-friendly approach. The firm declared a final dividend with a 90% payout ratio of distributable earnings and expanded its payout range to 50–95%. Strategic initiatives such as the deconsolidation of PCS (Private Capital Solutions), geographic expansion through the Abu Dhabi office, and successful rebranding of their Quality Dividend Income strategy to Quality Value suggest strong future growth and market adaptability. Their recent April 2025 update showed continued momentum, with total FUM growing further to US$163.6 billion and year-to-date net inflows of US$6.0 billion, reflecting sustained demand for their products.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns