Earnings RPM Global RUL:ASX
- Overview
The first half of Fiscal Year 2025 (1H FY2025) has been a record-setting period for RPM, marked by significant revenue growth and improved EBITDA performance. The company successfully surpassed management expectations, achieving a 10% increase in gross revenue and a substantial 21% rise in underlying EBITDA compared to the same period last year. Despite a notable decline in net profit, the overall financial trajectory remains positive, positioning RPM favourably for continued growth in the latter half of the fiscal year.
- Financial Performance
Key Metrics
- Gross Revenue: Increased by 10% to $58.2 million in 1H25 from $53.1 million in 1H24.
- Underlying EBITDA: Rose by 21% to $8.2 million in 1H25 versus $6.8 million in 1H24.
- Net Revenue: Grew by 10% to $53.8 million in 1H25 from $48.8 million in 1H24.
- Net Profit: Decreased by 31% to $4.7 million in 1H25 compared to $6.8 million in 1H24.
- Americas Software Sales: Surged by 79% to $16.1 million in H1 FY2025 from $9.0 million in FY2024.
- Revenue Growth: Overall revenue up 64% to $47.1 million in H1 FY2025 versus $28.8 million in the same period last year.
- Subscription ARR Churn: Increased to 5.6% in FY2025 from 3.0% in 1H24.
Revenue & Growth Trends
RPM achieved a 10% year-over-year (YoY) increase in both gross and net revenues, reaching $58.2 million and $53.8 million respectively in 1H25. The significant 64% rise in revenue for H1 FY2025 underscores robust business expansion, particularly in the software sales segment within the Americas, which saw a substantial 79% growth.
Margin & Profitability Metrics
The underlying EBITDA demonstrated strong improvement, increasing by 21% to $8.2 million in 1H25. However, net profit experienced a decline of 31%, dropping to $4.7 million from $6.8 million in the previous year. This reduction in net profit may be attributed to increased operational costs or investments made during the period.
Year-over-Year Changes
Metric | 1H FY2025 | 1H FY2024 | Change |
Gross Revenue | $58.2M | $53.1M | +10% |
Underlying EBITDA | $8.2M | $6.8M | +21% |
Net Revenue | $53.8M | $48.8M | +10% |
Net Profit | $4.7M | $6.8M | -31% |
- Guidance and Expectations
Management has affirmed the company’s positive trajectory by confirming that RPM set new half-year records for both revenue and underlying EBITDA, aligning with the previously provided guidance. The successful performance in the first half of FY2025 provides a strong foundation for the company’s strategic initiatives and expected outcomes in the remaining fiscal period.
Forward Guidance
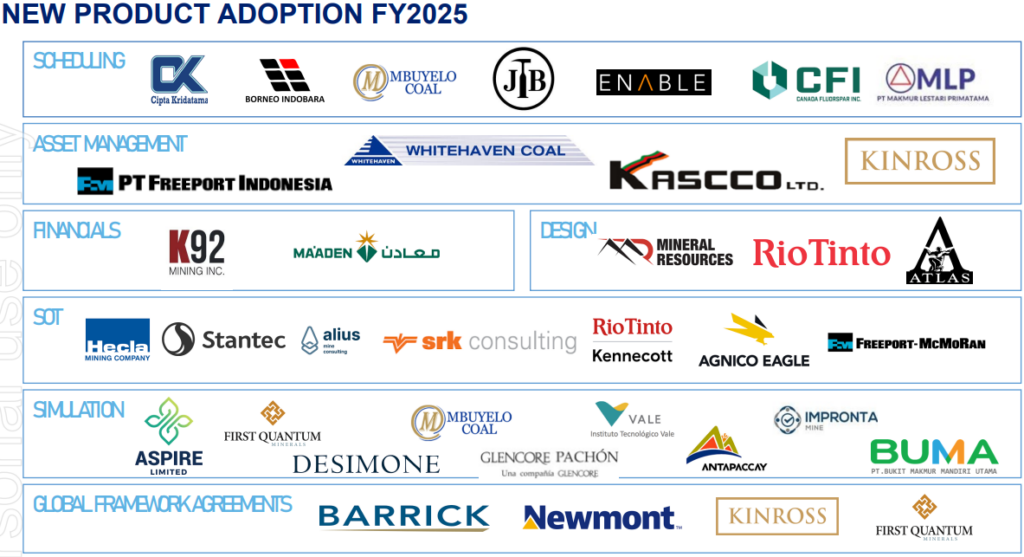
- Completion of three significant software pilot projects—Rio Tinto, Kinross, and Freeport—is on track for FY2025, which is expected to bolster future revenue streams and enhance client relationships.
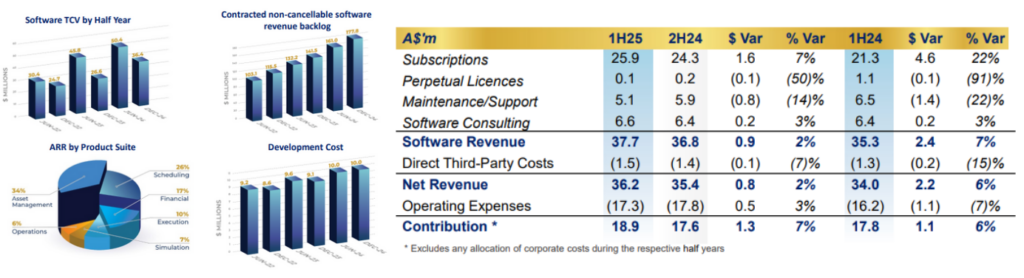
- Pre-contracted non-cancellable software and maintenance revenue has risen by $38.8 million to $182.8 million as of February 14, 2025, providing stability and predictability in revenue forecasts.
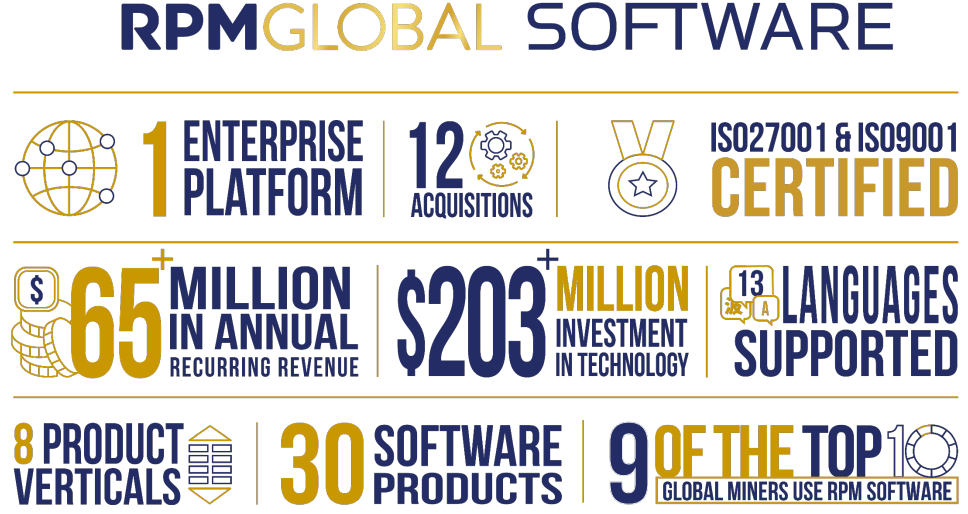
- Annually Recurring Revenue (ARR) stands at $65.0 million as of February 14, 2025, indicating sustained growth in the subscription-based segment.
Variance from Previous Guidance
The company’s performance remains in line with management’s expectations. Revenue growth exceeding previous periods and the successful expansion of the Americas software sales segment highlight RPM’s effective execution of its strategic plans. However, the increase in subscription ARR churn from 3.0% to 5.6% suggests a need for ongoing focus on customer retention strategies.
Guidance and Expectations
The company has realigned its strategic focus by divesting its Advisory division to concentrate solely on the Software business. This move is expected to enhance the company’s appeal to software-focused investors and simplify its operations. Additionally, the ongoing share buyback program indicates management’s confidence in the company’s long-term prospects.
**Management Commentary:**
- Restructuring expenses of $362,000 were incurred, reflecting organizational changes aimed at improving efficiency.
- The divestment of RPM Advisory Services Pty Ltd and related subsidiaries for AUD$63 million is anticipated to close by the end of the 2025 financial year, further streamlining operations.
Competitive Landscape
RPMGlobal operates within the software and advisory services sector, facing competition from both established players and emerging firms. The company’s strategic shift to focus exclusively on software positions it to better compete in a rapidly evolving market.
- Market Share Implications: By prioritizing subscription-based licenses over perpetual licenses, RPMGlobal aligns with industry trends favoring recurring revenue models.
- Peer Comparisons: Compared to industry peers, RPMGlobal’s revenue growth in the Software division (6.5%) is on par with sector averages, while the Advisory division’s growth (15.4%) outperforms typical industry growth rates.
**Potential Opportunities & Threats:**
- Opportunities: Increased focus on software subscriptions can lead to more stable and predictable revenue streams. The divestment of non-core businesses allows for reinvestment in growth areas.
- Threats: The significant decline in perpetual license sales may impact short-term revenue. Additionally, geopolitical risks, such as the loss of control over entities in Russia and South Africa, could pose challenges.
Strategic Considerations
Operational and Cost Initiatives
- Restructuring efforts aimed at reducing operational complexities and focusing on core business areas.
- Reduction in rechargeable expenses by 15.3% demonstrates effective cost management.
Capital Allocation Plans
- Share Buyback: Executed a buyback totaling $6.89 million during the reporting period, signaling confidence in the company’s valuation.
- Divestments: Sale of RPM Advisory Services Pty Ltd and related subsidiaries for AUD$63 million to SLR Consulting Australia Pty Ltd to streamline operations.
Expected Impact on Near & Long-Term Outlook
- Focusing exclusively on the Software division is expected to enhance profitability and market positioning in the long term.
- Share buybacks may lead to improved earnings per share (EPS) metrics and increased shareholder value.
- Divestments will likely reduce the company’s operational scope, allowing for more targeted investments in high-growth areas.
Disclaimer: The recommendation given is general advice only. It does not take into account your personal objectives, financial situation, or specific needs. This information should not be your sole resource when making such decisions. We strongly recommend you to seek the advice of financial, taxation, and legal professionals before finalising any investment decisions.
Past performance is not an indicator of future returns